
Selected Stock Price Target News — July 14, 2026
Three numbers moved on Wall Street this morning, and none of them tell the same story. Netflix ($NFLX) picked up price target cuts from three separate desks. That came two days before its own earnings call. Tesla ($TSLA) drew a $130 to $417 spread from three more analysts. Each one holds a different rating on the stock. And Apple ($AAPL) got a rating call its own analysts rarely make. It’s Underweight, with a $250 target built on a slowing iPhone cycle.
A Blackout On Subscriber Counts Sends Three Desks Trimming Netflix Targets Before Thursday’s Print
Netflix is a subscription streaming service. It sells access to movies, TV shows, and other video content. In its most recent reported quarter, the first of 2026, Netflix posted revenue of $12.25 billion. That’s up 16% year over year. Net income came to $5.28 billion. That figure was lifted by a one-time $2.8 billion termination fee tied to the Warner Bros. deal. Netflix reports its second quarter after the closing bell Thursday, July 16. The call is scheduled for 4:45 p.m. Wall Street’s consensus for that quarter sits at $12.58 billion in revenue, up 13.8% from a year ago. Earnings are expected at $0.79 a share. That’s down sharply from the $1.25 the company posted in the first quarter. Seasonality and heavier content amortization drove the drop. Netflix stopped reporting regular membership counts after that first quarter print.
The Signals Behind The Early Cuts
Thursday’s call turns on other signals instead. One is whether the ad supported tier keeps pace with its own $3 billion revenue target for the year. Another is whether operating margin holds near the 32.6% level management guided to for the quarter. That’s inside a 31.5% full year target the company already reaffirmed. None of that is new information by Thursday morning. That’s exactly why three desks chose to move their numbers before the print instead of after it. Rosenblatt’s Barton Crockett has been the most direct about why. He says the engagement data his firm tracks gives him reason for caution. He’s careful to add that it isn’t tied to any single figure specific to this quarter, though.
Morgan Stanley’s Sean Diffley held his Overweight rating but cut his target to $90 from $115. Barclays’ Kannan Venkateshwar kept Netflix at Equal-Weight and trimmed his own number to $85 from $110. Crockett left his Neutral rating in place at $95. That’s the lowest number on AnaChart’s board of 33 analysts covering the stock. That board’s consensus sits at $118.49, against a $150 high. Venkateshwar has hit 65.77% of his price targets, across a 667 target career spanning 29 stocks. Crockett’s own record runs cooler, 55.97% across 1,256 targets on 50 names.
Where The Netflix Ratings Stand
None of the three touched their rating. So this isn’t a fight over direction into Thursday. It’s a fight over how much to trim before finding out. Diffley’s Overweight is the only one of the three still pointing toward upside from current levels. Venkateshwar’s Equal-Weight and Crockett’s Neutral both predate this week’s countdown. Thursday’s report moves all three positions from here.
Across AnaChart’s full board for Netflix, 70.71% of active ratings are still Buy equivalents against 29.29% Hold. No Sell rating is currently active anywhere in the coverage list. Thursday’s print could pull that mix toward the cautious end. Or it could leave the mix exactly where three separate desks just placed it.
A Robotaxi Timeline Debate Splits Three Desks $287 Apart On Tesla Ahead Of The July 22 Print
Tesla designs, builds, and sells electric vehicles. It also sells energy storage and solar products. Its most recent reported quarter, the first of 2026, brought revenue of $22.39 billion. Net income came to $477 million, with non-GAAP EPS of $0.41. Tesla delivered 480,126 vehicles in the second quarter, up about 25% from a year ago. That’s well past the roughly 406,000 Wall Street had modeled. The company reports second quarter results after the close on July 22, with a Q&A webcast at 4:30 p.m. It has already lifted its 2026 capital spending guidance above $25 billion. That funds AI5 and AI6 chips and the Optimus robot program. It also covers a new Terafab chip line in Texas, plus its energy and battery buildout. Consensus non GAAP earnings for the second quarter sit at $0.47 a share.
The Questions Beyond The Delivery Number
The delivery number is already public. What analysts are still fighting over is what comes after it. Does automotive gross margin excluding credits hold near 20%? How fast does FSD subscription revenue grow, as European regulatory approval inches forward? And do Robotaxi and Optimus start looking like a real business, or stay a research project? Management’s own timeline says no material Robotaxi revenue before 2027. Service expansion to roughly a dozen states is targeted by year end.
Three more desks moved on Tesla the same morning. Wells Fargo’s Colin Langan held Underweight and raised his target to $130 from $125. That’s the second lowest figure on AnaChart’s 27 analyst board. Only GLJ Research’s Gordon Johnson sits lower. His $24.86 Sell case applies a 25 times multiple to his 2027 earnings estimate. It excludes any value from autonomy or robotics. Morgan Stanley’s Andrew Percoco held Equal-Weight and nudged his own number to $417 from $415. Barclays’ Dan Levy, same rating, raised his to $370 from $360. The board’s consensus runs $409.16, with a $600 high. Langan has hit 81.97% of his targets, across 1,028 calls on 22 stocks. Percoco’s own record is cooler, 69.39% across 255 targets on 16 names.
Where The Bull And Bear Cases Diverge
Percoco’s bull case counts on Robotaxi and Optimus doing the heavy lifting. He now models 1.6 million vehicle deliveries for 2026, up from a prior 1.58 million. He expects roughly 1,500 robotaxis on the road by year end, scaling toward 30,000 by 2030. That’s enough, in his view, to reaccelerate FSD attach rates and auto demand through the back half of the decade. Langan isn’t buying the timeline. His Underweight is built on the business Tesla has today, not the one it might have tomorrow. Vehicle demand is decelerating. Competition is intensifying. Repeated price cuts keep pressuring the margin Tesla needs to defend its own valuation.
AnaChart’s full Tesla board runs 62.38% Buy equivalents, 19.8% Hold, and 17.82% Sell. That’s the widest three way split of today’s three tickers. Percoco and Langan sit at opposite ends of that spread, $287 apart on where the number should land. The July 22 print is the next test for both.
A Rare Underweight Call Splits KeyBanc And Morgan Stanley Over Apple’s iPhone Price Hikes
Apple designs and sells consumer electronics, software, and services. The iPhone is its largest single product line. In its most recently reported quarter, fiscal Q2 2026, Apple posted revenue of $111.2 billion. That’s up 17% year over year. Net income came to $29.58 billion, with EPS of $2.01. KeyBanc’s Brandon Nispel downgraded Apple to Underweight from Sector Weight this morning, with a $250 target. It’s a rating his firm rarely puts on the stock. His argument rests on KeyBanc’s own indexed spending tracker. It showed spending down 2% month over month, against a three year average of positive 9%. Nispel points to slowing iPhone builds even as prices rise. He also cites weaker U.S. upgrade activity and shifting device subsidy terms from carriers. He expects fiscal 2027 estimates across Mac, iPad and Wearables to come down.
A Valuation Case, A Chip Deal, And A Lawsuit
He’s modeling Services growth decelerating to 7% next fiscal year, against a Street estimate closer to 12%. He also flags Apple’s valuation. It sits near 24.5 times his fiscal 2027 EV to EBITDA estimate, and 35 times earnings. He pegs that more than two standard deviations above its own premium to the S&P 500 and Nasdaq. The note lands in the same week Apple disclosed a custom silicon agreement with Broadcom. That deal is valued at more than $30 billion. Apple also filed a federal trade secret complaint against OpenAI that same week, over former employees.
On the other side sits Erik Woodring, at Morgan Stanley. His Buy rating and $360 target have stood since July 2022. On AnaChart’s own matrix, his price targets on Apple specifically have landed 46 of 48 times. That’s a 95.83% mark. That’s the strongest scored record of any analyst on the stock. Nispel’s own career figure runs cooler, 62.97% across 518 targets and ratings on 29 stocks at KeyBanc. Apple’s 29 analyst board carries a $307.71 consensus. That’s between a $380 high and a $220 low. Nispel’s new $250 sits well inside that range.
Where Woodring And Nispel Disagree
Woodring reads the same price increases as a straightforward margin play. He argues iPhone buyers have historically shown little sensitivity to price. A $200 to $300 increase works out to just $4 to $6 a month. That’s over a four year replacement cycle. That’s inside a product lineup that keeps customers locked in regardless. Nispel reads the identical hikes as a defensive move. He calls them evidence of soft underlying demand that price alone can’t fix. U.S. carriers, meanwhile, are already pulling back on the subsidies that used to mask the sticker price.
Nispel’s $250 would be the single lowest figure on Apple’s board. That’s only if it registers before the next quarterly refresh. Woodring’s $360 already sits about $52 above the $307.71 consensus. One of the two AnaChart records behind those numbers runs roughly 33 percentage points higher than the other.
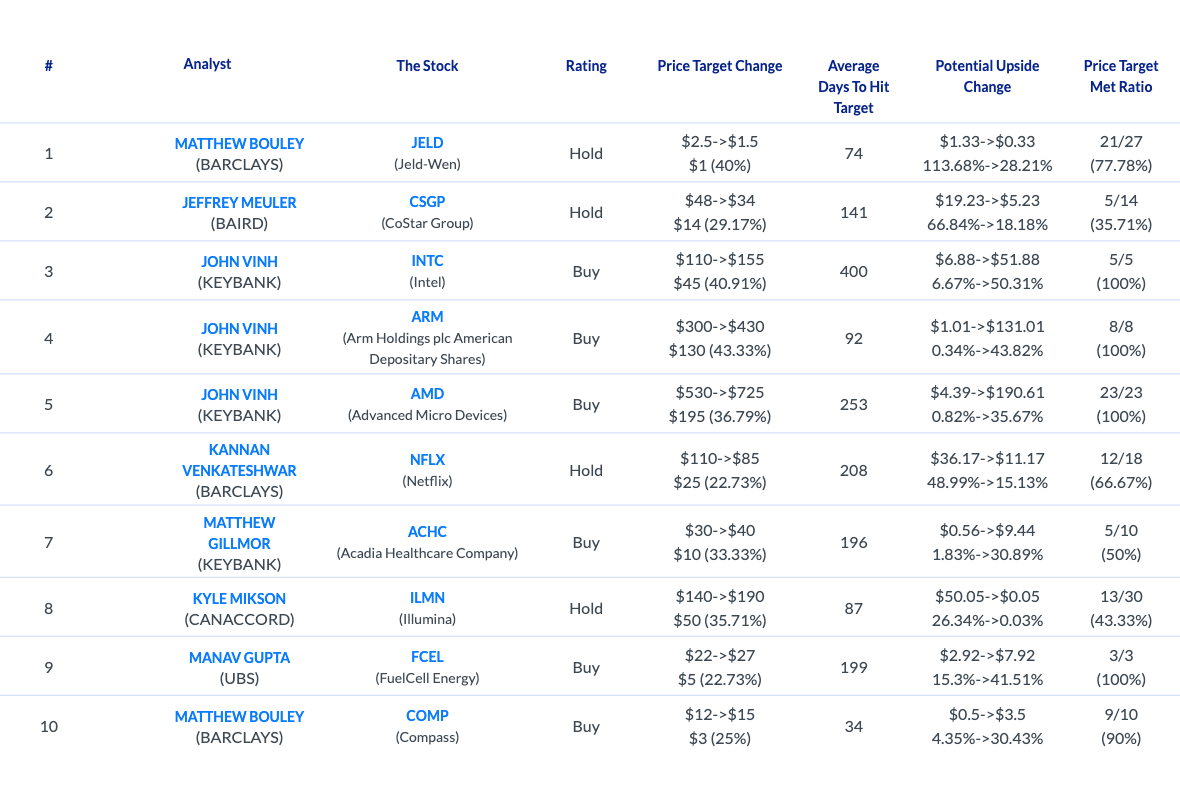
Six different desks weighed in across these three names this morning. KeyBanc, Morgan Stanley, Barclays, Wells Fargo, Rosenblatt and GLJ Research all moved a number or held a line. That’s ahead of two earnings dates and one valuation debate. AnaChart tracks every one of those calls against what happened to the stock afterward. That’s 661,383 price targets and 759,654 ratings across 7,191 analysts and 9,686 tickers, going back to 2008. The full price target history behind today’s calls sits in the analyst price target dataset.