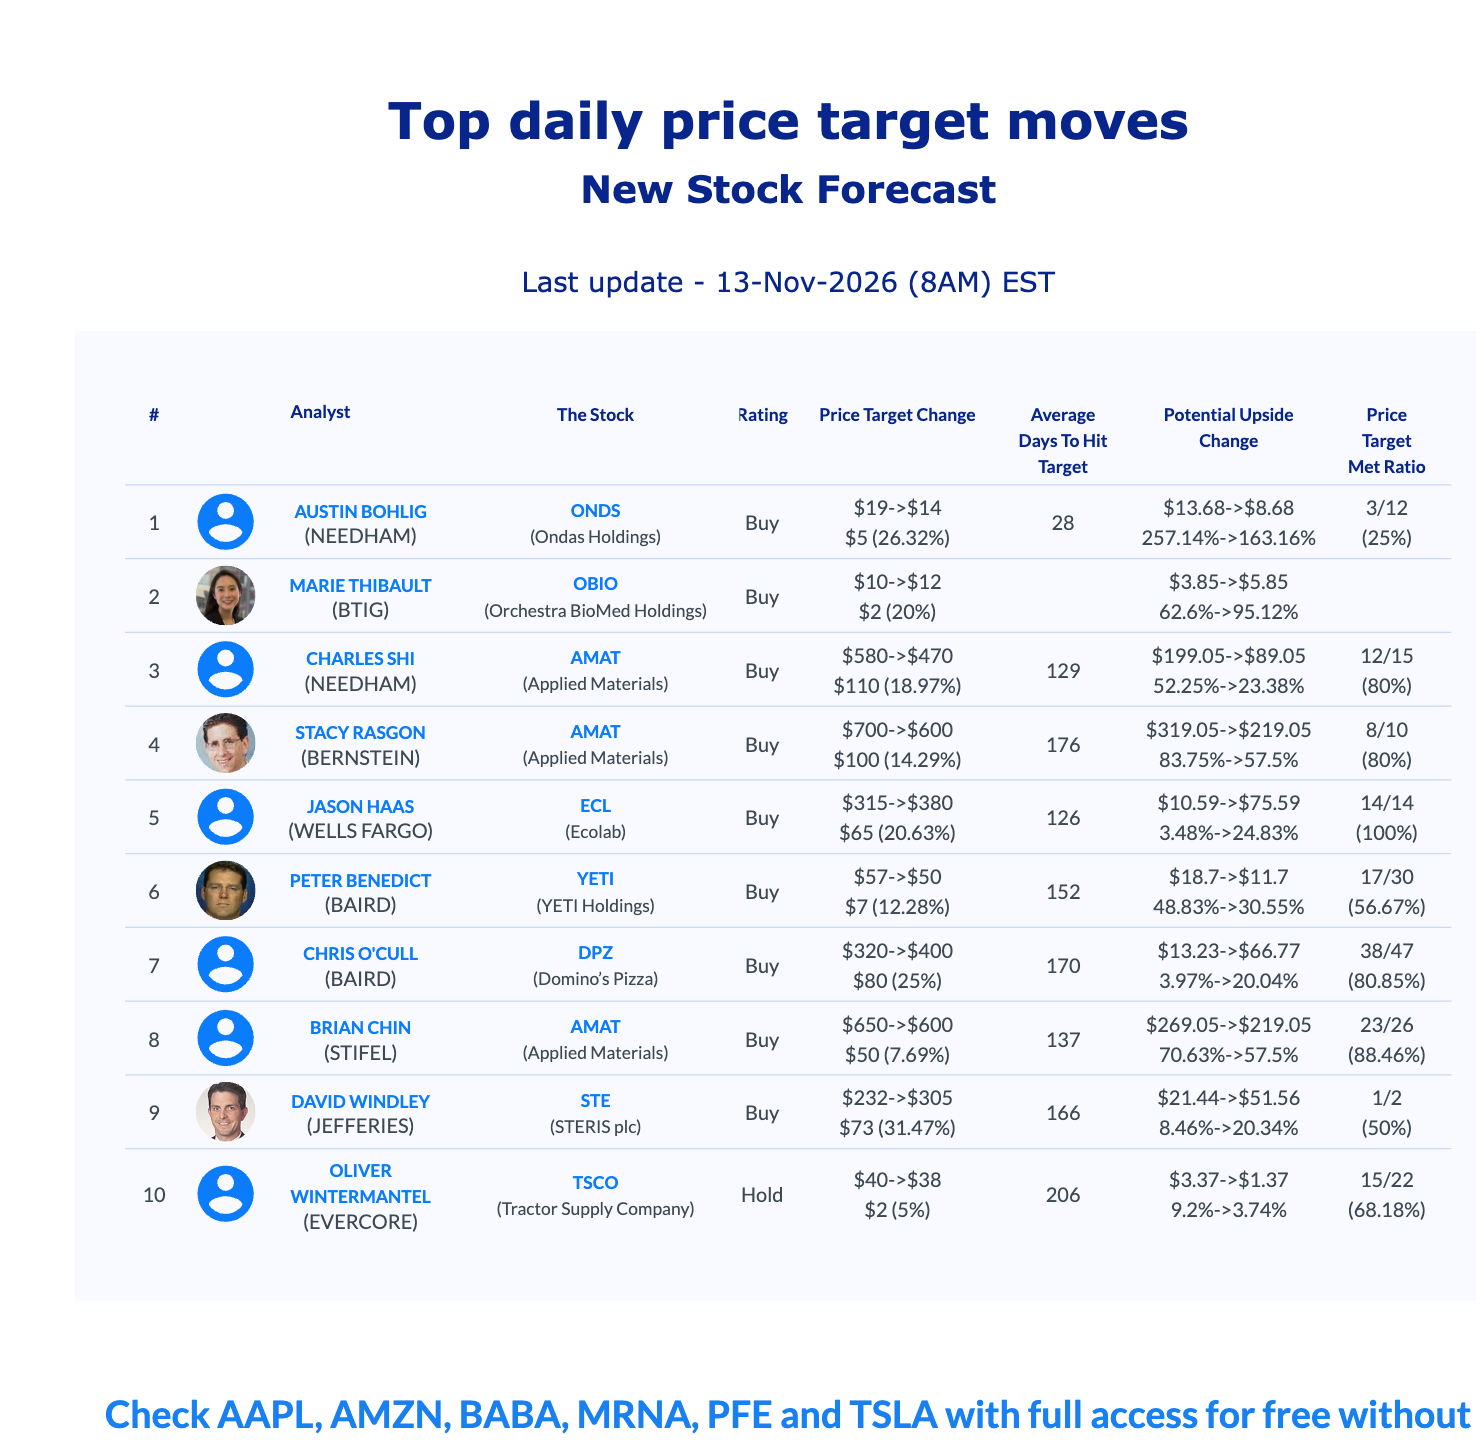
YETI, NeuroPace, Twist Price Targets, November 13 2026
YETI
YETI Holdings designs coolers, drinkware, bags and outdoor gear. It sells through its own website and stores and through retailers. The company is based in Austin, Texas. It reported third-quarter results on Thursday. Revenue, reported as net sales, came to $509.4 million, 2.7% below the $523.58 million consensus. Adjusted earnings were $0.91 a share, 7.1% above the $0.85 expected.
What Drove YETI’s Quarter
Net sales grew 4% from $487.8 million a year earlier. Drinkware sales grew 8% to $284.0 million. Coolers and Equipment sales were flat at $215.6 million. Wholesale sales grew 19% to $237.3 million. Direct-to-consumer sales shrank 6% to $272.2 million. Chief financial officer Scott Bomar said DTC would have been about flat without a shift in the timing of Prime Day.
U.S. sales grew 1% to $390.3 million. International sales grew 19% to $119.1 million. Chief executive Matthew Reintjes called the quarter strong in Europe and in Australia and New Zealand. He said Canadian sales were lower. YETI also opened its first brand stores in Japan and Korea and a first online marketplace presence in China.
The gross margin was 57.7%, against 55.9% a year earlier. The company said lower net tariff costs added 200 basis points. Recall reserves took off 130 basis points. Adjusted operating income grew 35% to $90.0 million. Meanwhile, inventory grew 22% to $394.2 million. YETI bought back $20.0 million of stock in the quarter.
YETI’s New Outlook
YETI now sees adjusted sales growth of about 6% for 2026, against 7% to 8% before. It lowered its adjusted EPS outlook to $2.90 to $2.95, from $2.94 to $3.00. Bomar cited a more cautious view of consumer demand. He said demand has moderated early in the fourth quarter. He said the international growth outlook is now mid-teens, mainly because of Canada.
Five Desks Cut YETI
Peter Keith of Piper Sandler downgraded YETI to Neutral from Overweight and lowered the price target from $58 to $39 today. Noah Zatzkin of KeyBanc lowered his target from $57 to $49. Brian McNamara of Canaccord lowered his target from $46 to $42. Peter Benedict of Baird kept Outperform and lowered his target from $57 to $50. Peter McGoldrick of Stifel kept Buy and lowered his target from $50 to $48.
A day earlier, on Thursday, Dan Wewer of Raymond James reiterated Outperform and a $56 target.
YETI’s Record on AnaChart
YETI draws 15 covering analysts on AnaChart. Their average target is $52.17. Ratings split 68.75% Hold and 31.25% Buy. AnaChart’s tracking shows 72.56% of YETI targets get met. That takes about 124 days on average.
NeuroPace
NeuroPace makes the RNS System, a brain implant for drug-resistant focal epilepsy. It sells the device to epilepsy centers that implant it. The company is based in Mountain View, California. It reported third-quarter results on Thursday. Revenue came to $23.1 million, 14.9% below the $27.16 million consensus. Its loss was $0.10 a share.
What Drove NeuroPace’s Quarter
Total revenue shrank 1.1% from $23.4 million a year earlier. RNS System revenue grew 1.4% to $22.9 million. Chief executive Joel Becker said much of the shortfall came from several of the company’s largest accounts. He pointed to staffing, physician availability and diagnostic capacity at those centers. Becker also cited changes in the sales and field clinical teams in midyear. He said most delayed patients were pushed out, not lost.
The non-GAAP gross margin was 84.8%, against 82.8% a year earlier. Meanwhile, non-GAAP operating expenses shrank to $19.2 million from $20.7 million. Adjusted EBITDA was $0.4 million, against a loss of $1.3 million. The GAAP net loss from continuing operations was $3.3 million. NeuroPace ended September with $49.5 million in cash.
NeuroPace’s New Outlook
NeuroPace cut its 2026 revenue outlook to $91 million to $92 million, from $99.5 million to $101.5 million. It lowered its operating expense outlook to $85 million to $86 million. Chief financial officer Patrick Williams said the outlook does not assume a return to earlier growth rates in the fourth quarter. He expects RNS growth of about 15% in 2027. Becker said the company plans to file an amendment for a generalized epilepsy indication around year-end. He called mid-2027 a reasonable planning assumption for approval.
Three Downgrades on NeuroPace
Larry Biegelsen of Wells Fargo downgraded NeuroPace to Equal Weight from Overweight and lowered the price target from $19 to $9 today. Robbie Marcus of JPMorgan downgraded the stock to Neutral from Overweight, with a $9 target. Mike Kratky of Leerink downgraded it to Market Perform from Outperform, with a $7 target. Brett Fishbin of KeyBanc lowered his target from $18 to $14.
NeuroPace’s Record on AnaChart
Before today’s moves, NeuroPace drew 3 covering analysts on AnaChart. Their average target was $20.67, and all of them rated it Buy. AnaChart’s tracking shows 68.39% of NeuroPace targets get met. That takes about 158 days on average.
Twist
Twist Bioscience makes synthetic DNA on a silicon platform. It sells genes, oligo pools and tools for DNA sequencing to labs and drug developers. The company is based in South San Francisco. It reported fiscal fourth-quarter results on Thursday. Revenue came to $126.6 million, 2.4% above the $123.59 million consensus. Its loss was $0.32 a share, a 15.8% narrower loss than the $0.38 expected.
What Drove Twist’s Quarter
Revenue grew 28% from $99.0 million a year earlier. It was the 15th straight quarter of sequential growth. DNA synthesis and protein solutions revenue grew 33% to $61.0 million. Revenue from sequencing applications grew 24% to $65.7 million. The gross margin was 53.1%, against 51.3%. Adjusted EBITDA was $2.2 million, against a loss of $7.8 million a year earlier.
Also, the net loss narrowed to $20.6 million from $27.1 million. For the full fiscal year, revenue grew 22% to $459.4 million. Twist shipped products to about 4,100 customers in the year. It ended September with about $582 million in cash and short-term investments.
For fiscal 2027, Twist guides to revenue of $550 million to $560 million. That includes an assumed $100 million from AI drug discovery work. It sees first-quarter revenue of $130 million to $132 million and positive adjusted EBITDA for the year. Chief executive Emily Leproust said the company enters the year “with a stronger business.”
Three Desks Cut Twist
Catherine Schulte of Baird kept Outperform and lowered her target from $187 to $135 today. Kyle Mikson of Canaccord lowered his target from $205 to $150. Subbu Nambi of Guggenheim lowered his target to $150.
A day earlier, on Thursday, Matthew Stanton of Jefferies kept Hold and lowered his target from $150 to $125.
Twist’s Record on AnaChart
Twist draws 12 covering analysts on AnaChart. Their average target is $121.93. Ratings split 87.18% Buy, 10.26% Hold and 2.56% Sell. AnaChart’s tracking shows 95.4% of Twist targets get met. That takes about 196 days on average.
What the Performance Matrix Shows
Twist has the best met ratio of the three, and NeuroPace the lowest. A met YETI target lands in about 124 days. By contrast, a met Twist target takes about 196. AnaChart’s first Twist forecast dates to November 2018, and its first NeuroPace forecast to May 2021.
AnaChart tracks every price target against what happened to the stock afterward, desk by desk and analyst by analyst. The ticker pages linked above break out each record by analyst, firm and year. AnaChart’s full data set holds more than 760,000 analyst calls on more than 9,000 tickers, active and delisted. More than 680,000 carry a price target and more than 730,000 carry a rating. It is the second largest database of its kind. The raw file is available through the AnaChart store.
The previous update covered Oddity, enGene and DoubleDown on November 12.