
Selected Stock Price Target News — July 10, 2026
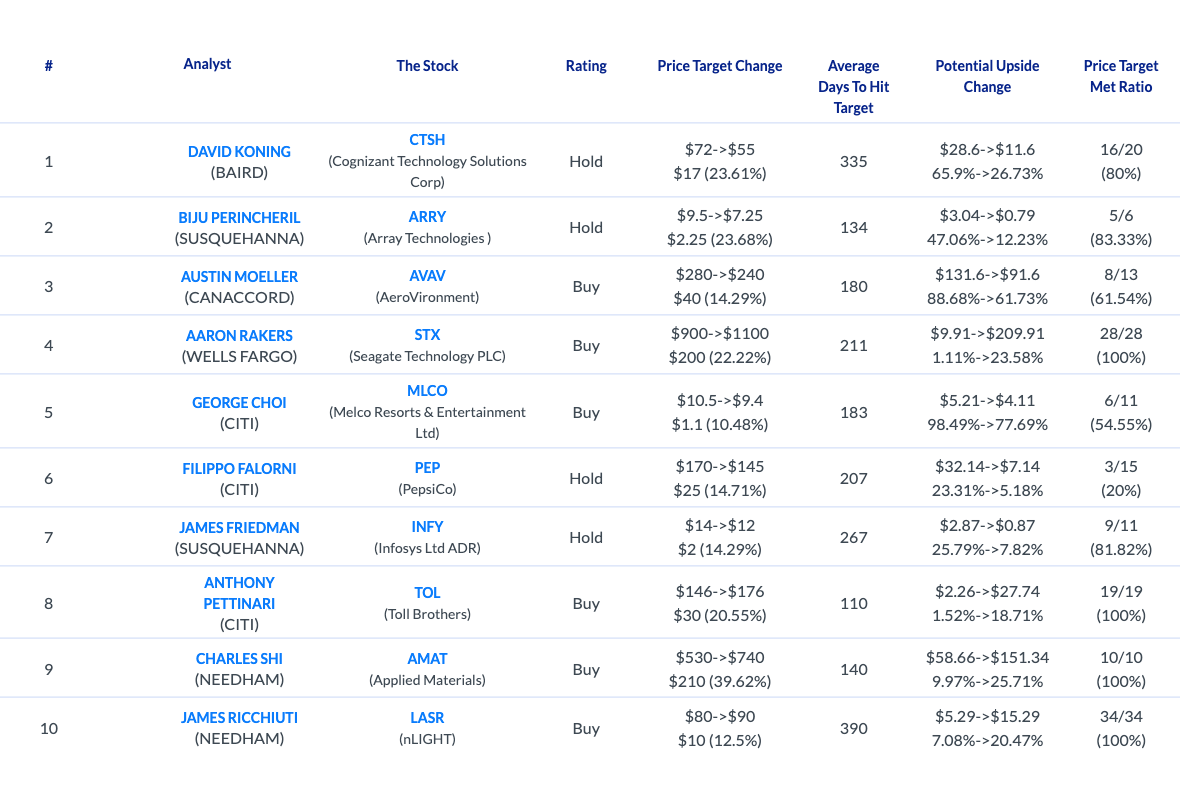
Three rating changes hit the tape this morning. Each one landed after weeks of a desk warming up to it. Wells Fargo’s Aaron Rakers moved Seagate Technology ($STX) to Overweight from Equal-Weight. He raised his target to $1,100 from $900, the fourth increase he has made on the stock since April. David Vernon at Bernstein took J.B. Hunt Transport Services ($JBHT) to Outperform from Market Perform. He lifted his target 71%, to $329 from $192, four days after Morgan Stanley cut the stock the other way. And Brendan Lynch at Barclays swapped his top self storage pick. He upgraded CubeSmart ($CUBE) while downgrading Public Storage on the same note.
Record AI Storage Demand Pushes Wells Fargo Off the Fence on Seagate
Seagate makes the hard disk drives that data centers use to store information at scale. Its fiscal third quarter was reported in early June. It brought non-GAAP EPS of $4.10 per share. Gross margin came in near 47%, the highest in company history. The guide for the fourth quarter: revenue near $3.45 billion, plus or minus $100 million. Non-GAAP earnings are guided near $5.00 a share.
Data center revenue did the heavy lifting. It ran about $2.5 billion in the March quarter alone, roughly 80% of everything Seagate sold. Seagate and Western Digital run the hard drive business as a near duopoly. The AI buildout has shifted what cloud operators want. They now want fewer, bigger drives. Each one is packed with more capacity per unit, exactly the high end of Seagate’s lineup. Exabyte shipments and pricing have both stayed firm through the stretch, per management’s own comments at recent investor conferences.
How Rakers’ Target Has Climbed Since April
Rakers has been walking his own number up for months. He went from $450 to $700 in late April. He moved it again, from $700 to $900, on June 1. Now it’s $900 to $1,100 today, alongside the rating change itself. He’s not the most bullish desk on the stock, either.
Cantor Fitzgerald‘s C.J. Muse holds the Street’s highest target, $1,300, set June 29. Citigroup‘s Asiya Merchant has sat at $1,150 since June 2. BofA‘s Wamsi Mohan raised his own target to $1,150 from $1,000 on July 1. That move extended his record to 30 of 31 past Seagate targets met, a 96.77% rate. Morgan Stanley‘s Erik Woodring raised his target to $1,035 on June 15. He has reached all 28 of his past Seagate targets. Five desks now sit above $1,000. Even so, the 22-analyst consensus sits at $749.27. That’s a full $351 below where Rakers just moved today.
Susquehanna‘s Mehdi Hosseini is the closest thing to a skeptic left standing. He kept his Neutral rating just two days before Rakers flipped. He did raise his own target, to $775 from $615, on July 8. That’s still $325 below where Wells Fargo landed today. One caveat sits alongside all the target increases. Insiders have sold Seagate stock in 201 separate trades over the past six months. They bought none, including CEO William Mosley’s $94 million in sales.
Hosseini’s rating has stayed at Neutral through this entire run of target increases. His own number still climbed, from $615 to $775, in the space of two months. Rakers’ upgrade today is the first rating change on Seagate from any of the desks named in this section. The last one was Woodring’s move to Overweight, back in July 2024.
Record Intermodal Volumes Are Not Enough to Keep Wall Street Aligned on J.B. Hunt
J.B. Hunt is a trucking and logistics company. It moves freight by truck. It also moves shipping containers by combining rail and truck legs into one trip, a business called intermodal. Its first quarter was reported in mid April. Revenue came to $3.06 billion. Net income came to $141.55 million. Record intermodal volumes did most of the work. Intermodal has been getting help from an unlikely source. Tighter federal trucking regulations have squeezed capacity out of the standalone truckload market. That’s pushed some freight onto rail lanes, where J.B. Hunt has spent years building out capacity. Management has used the resulting cash to pay down debt and buy back stock, the first sustained buyback activity in several quarters.
J.B. Hunt was re-added to the Russell 1000 Dynamic Index this month. That’s a technical event, not a fundamental one. Still, it landed in the same stretch as the improving earnings picture. The company reports second quarter results on July 15, five days from now.
Vernon’s Upgrade Against Morgan Stanley’s Downgrade
Vernon’s upgrade takes his target to $329 from $192. That’s a 71% jump, the largest single target move in this morning’s batch of analyst actions. He’s moving against a call Morgan Stanley made just four days ago. On July 6, Morgan Stanley’s Ravi Shanker downgraded the stock to Underweight from Equal-Weight. He still raised his own target, to $200 from $190. That same day, his firm cut its entire freight sector view to In Line from Attractive. Two more desks landed in between. Goldman Sachs‘s Jordan Alliger maintained Neutral at $239 on July 9. Citigroup’s Ariel Rosa maintained Neutral at $278 the same day. Four calls in one week, four different numbers: $200, $239, $278, $329.
Morgan Stanley’s own sector note leaned bullish on the freight cycle. It adopted what had been its optimistic scenario as the new base case for the industry. The catch, in the firm’s own framing: freight stocks have already rallied sharply on that improving outlook. That leaves less room to run even if the fundamentals keep getting better. Vernon’s upgrade points to that same freight upcycle, the one Morgan Stanley just called strengthening. But his call skips Morgan Stanley’s own caution, about how much of that strength the shares already reflect.
Alliger carries the strongest scored record of the four. His career met ratio runs 85.2%, across 378 targets on 20 stocks. Vernon’s career figure sits at 64.88%, across 248 targets on 14 stocks. Shanker’s sits at 61.42%, across 1,665 targets spanning 47 stocks, the broadest coverage list of the group. J.B. Hunt’s own second quarter print is due July 15. It will be the first test of both the new $329 target and the fresh Underweight.
Diverging Entry Rate Trends Flip Barclays’ Top Self Storage Pick to CubeSmart
CubeSmart is a real estate investment trust. It owns and operates self storage facilities across the country. It reported first quarter 2026 revenue of $281.9 million, up 3.3% from a year earlier. Net income attributable to shareholders came to $82.9 million. Its adjusted funds from operations, the REIT industry’s preferred earnings measure, came to $144.2 million, or $0.63 per diluted share.
Barclays tracks entry rates across the self storage sector, the initial rent a landlord charges a new tenant. It’s one of the clearest leading indicators the industry has for where revenue growth is headed a few quarters out. CubeSmart’s and Extra Space Storage’s entry rates improved in the second quarter of 2026, per Lynch’s own data. Public Storage’s entry rates declined over the same stretch. That divergence sits next to a very different year for the shares themselves. Public Storage has gained 24% so far this year. That’s more than double CubeSmart’s 11% and Extra Space’s 11%, and well ahead of the 16% move in the RMZ self storage index. Public Storage now trades near 18 times Barclays’ 2027 funds from operations estimate, close to the firm’s own price target. That leaves less room to climb than either peer.
Lynch’s Paired Upgrade And Downgrade
Lynch upgraded CubeSmart to Overweight from Equal-Weight today. He also raised his target, to $46 from $45. On the same note, he downgraded Public Storage ($PSA) to Equal-Weight from Overweight. He held his target flat there, at $349. Public Storage operates as a self storage REIT too, one of the largest in the country. The pair of calls reverses where Lynch has stood since March 2025. Back then, he opened Overweight on Public Storage and Equal-Weight on CubeSmart. He’s not alone on the CubeSmart side. RBC Capital‘s Brad Heffern has carried a Buy rating and a matching $46 target since September 2024. Most of the rest of the coverage list sits below Lynch’s new number. Wells Fargo’s Eric Luebchow holds Equal-Weight at $39. Mizuho‘s Ravi Vaidya holds Hold at $42. UBS‘s Michael Goldsmith holds Hold at $43.
Why Entry Rates Matter More Than Occupancy
Entry rates matter more than headline occupancy in self storage. Tenants sign short leases and roll over often. A landlord charging less to fill a unit today is trading away revenue that shows up in same store growth a few quarters later. A landlord holding rates firm is betting the market can absorb it. Extra Space Storage is the third name in the group, also a self storage REIT. It kept its Overweight rating from Lynch. It got a target bump too, to $172 from $170 on the same note, sitting on the same side of the ledger as CubeSmart.
None of Lynch’s four price targets on CubeSmart have been met yet. None of his five on Public Storage have either. Both sets date to March 2025. Heffern’s CubeSmart target has sat unmet even longer, since September 2024, seven targets in. Vaidya’s record on the stock is stronger by comparison. Two of his last four targets have been met, with the current $42 figure set May 27.
Friday’s batch ran across a dozen desks: Wells Fargo, Morgan Stanley, Susquehanna, Cantor Fitzgerald, Citigroup, BofA, Bernstein, Goldman Sachs, Barclays, RBC Capital, Mizuho, and UBS. AnaChart’s dataset holds 661,383 price targets and 759,654 ratings. That’s from 7,191 analysts, 3,754 of them still active, across 9,686 tickers dating back to 2008. The full history behind every hit rate cited above sits in the analyst price target dataset.