
Selected Stock Price Target News — July 13, 2026
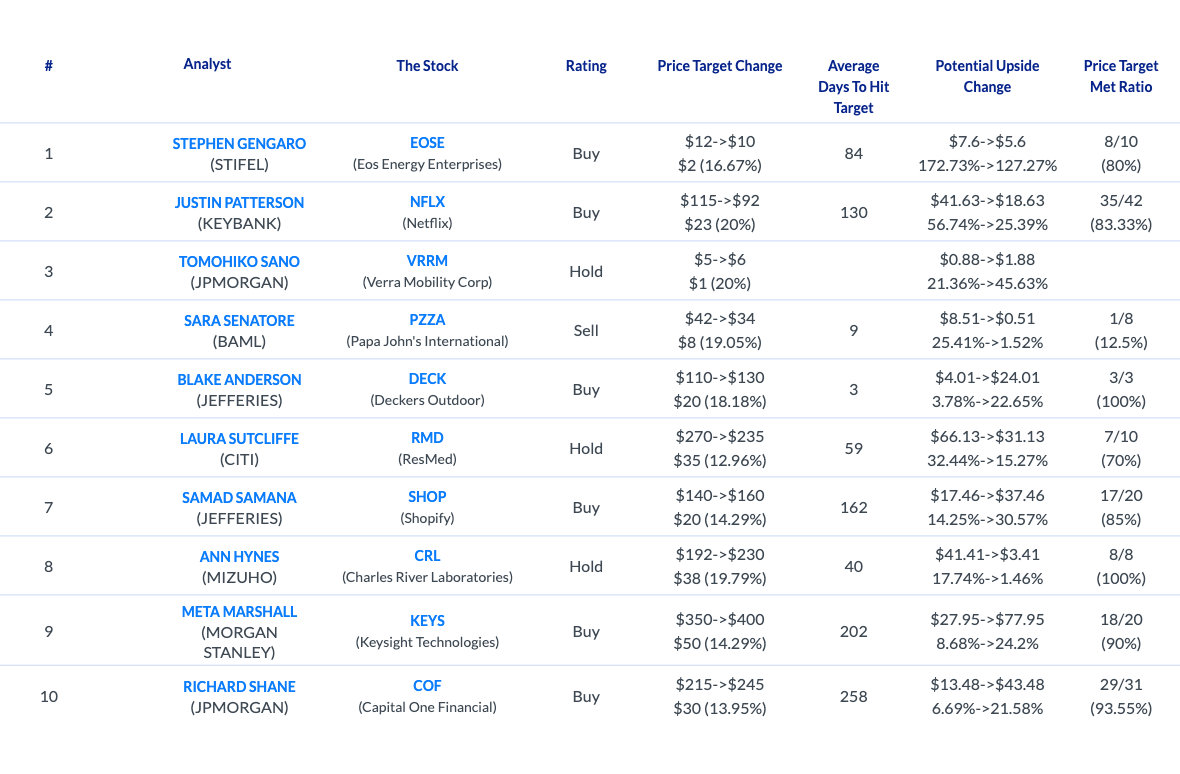
Three rating changes topped today’s list of the biggest price target moves. Each one came from an analyst switching sides, not just nudging a number. Truist’s Srikripa Devarakonda took Biogen ($BIIB) to Buy. New data on its Alzheimer’s drug had just crossed a stage in London. JPMorgan’s Richard Shane pushed American Express ($AXP) to Overweight. He set a $400 target, eleven days ahead of the company’s next earnings report. Jefferies’ Blake Anderson put Deckers Outdoor ($DECK), the maker of HOKA and UGG, back on Buy. It’s the first upgrade on the stock since a run of downgrades in May.
New Leqembi Data From a London Conference Lifts Truist’s Call on Biogen to Buy
Biogen is a biotechnology company. It develops and sells drugs for neurological diseases, including multiple sclerosis and Alzheimer’s. It reported first quarter 2026 revenue of $2.48 billion, up sharply from a year earlier. GAAP diluted EPS came to $2.15, up 31% year over year. Net income reached $319.5 million for the quarter. Biogen and its Japanese partner Eisai presented new data on the subcutaneous version of Leqembi. The venue was the Alzheimer’s Association International Conference in London, on July 12. That’s the day before Truist Securities analyst Devarakonda upgraded the stock.
The data showed something notable. The once weekly, at home injection produces drug exposure within about 4% of the intravenous version. That’s the version patients have used since Leqembi’s original approval. Real world results from two U.S. treatment centers backed that up. Patients on the shot held up on cognitive testing. Their results were about as well as expected from the drug’s original trials. Leqembi has always required either an infusion chair or, more recently, a maintenance only version of the shot. That’s why this matters. A version patients can start on right away removes a real barrier to new prescriptions. Patients would never have to visit an infusion suite at all. Biogen also has an immunology deal working in the background. The RayThera acquisition is expected to close in the third quarter. It adds a pipeline outside neurology entirely.
Devarakonda’s Upgrade And The Analysts Around It
Devarakonda raised her price target from $190 to $235. She also moved her rating, from Hold to Buy, the sharpest target change on Biogen this week. She rates 92% of her active names Buy. Her price targets across her 24 stock healthcare book have landed 56.26% of the time. Just five days earlier, Matthew Harrison of Morgan Stanley had reiterated a Hold at $222. Devarakonda’s new target clears that by $13. Harrison’s own record on Biogen runs deep. 38 of his 66 targets on the stock have been reached, a 57.58% rate. At RBC, Brian Abrahams has held a Buy at $242 since March 2022. That was the highest number on the stock before today. That’s backed by a 57.83% hit rate across 83 targets. Across Biogen’s 21 active analysts, AnaChart’s consensus sits at $213.44. That’s an upside of about 7% from Friday’s $199.15 close.
The Regulatory Path Behind Today’s Data
The FDA had already approved a subcutaneous maintenance dose of Leqembi, branded Iqlik, back in August 2025. That let patients already stable on the IV version switch to a once weekly shot at home. The AAIC data goes a step further. It supports a fully subcutaneous pathway from day one. A new patient could now skip the infusion chair entirely, rather than starting on IV and switching later. Harrison hasn’t pushed back on that shift. He took his own target from $206 to $224 in June. He then trimmed it slightly, to $222 on July 8, five days before Devarakonda’s call. That tracked the same momentum. He never moved off Hold, though. Abrahams, on the other side, has held a Buy since March 2022. His $242 target already sat above where Devarakonda landed today.
Biogen reports second quarter results on July 29, sixteen days from today. That’s the first real test of whether the SC-AI data changes new patient starts, not just the rating count. Even after today’s move, Biogen’s rating mix runs 36 Hold against 20 Buy and 1 Sell. Needham‘s Ami Fadia set the Street’s highest target on the stock, $256, on June 29. Her own record on Biogen so far is thin. Just 7 of her 37 targets have been reached. Devarakonda’s new $235 now ranks third among the group’s active Buy targets, behind Fadia and Abrahams.
Card Spending Momentum Ahead of Earnings Pushes JPMorgan to Overweight on American Express
American Express is a payments company. It issues credit cards and runs its own card network. Its revenue comes from card fees, merchant fees, and finance charges on cardholder balances. It reported first quarter 2026 revenue of $18.9 billion, up 11% year over year. Net income came to $2.97 billion, with diluted EPS of $4.28. American Express reports second quarter results on July 24. The number Richard Shane is betting on arrived back in April. Billed business is the company’s term for how much cardholders charged. It grew 10% year over year in the first quarter, the fastest pace in three years.
Shane upgraded the card network operator from Neutral to Overweight this morning. He raised his target, from $328 to $400, a 22% increase. That puts JPMorgan well above where the firm had the stock as recently as this spring. Consumer spending data through June showed some cooling in discretionary categories broadly. But American Express’s own base skews toward affluent cardholders. They keep traveling. They keep dining out, even when broader retail growth doesn’t. Gen Z cardholders, just 6% of the total book, grew their spending 38% in the first quarter. To Shane, that’s a sign the growth base is widening rather than aging out.
Where Shane’s New Target Sits Among Peers
Shane’s new $400 is the highest number on the stock. It’s ahead of a wave of other desks that had already been raising targets into the print. Evercore‘s John Pancari lifted his target to $380 on July 6. UBS‘s Erika Najarian went to $386 the next day. Barclays‘ Terry Ma moved to $364 that same July 7 session. All three held steady, sub Buy ratings while the numbers climbed.
TD Cowen‘s Moshe Orenbuch, by contrast, trimmed his target to $338 on July 7. He still held Hold, the only cut in the group. Pancari’s own record on American Express stands at 82% across 11 targets. Ma’s runs 92% across 13. Orenbuch has reached 100% of his 22, the best mark of anyone covering the stock. BTIG‘s Vincent Caintic remains the lone Sell. He’s held that rating since October 2024, even as he raised his own target to $324 on June 30.
The Lone Sell’s Rationale
Caintic’s Sell isn’t new. It doesn’t have anything to do with the July 24 print specifically. He’s held the rating since October 2024. His argument: American Express is priced for revenue growth near double digits forever. His case adds a second worry. The credit mix, as spending moves up through near prime and prime borrowers, won’t support that pace forever. Shane’s own note reads the other side of that same billed business data. It points to the 10% first quarter growth and the Gen Z pickup. Caintic’s price target, even so, climbed to $324 on June 30. That’s the same desk holding a Sell at a higher number than it had three months earlier.
Eleven days from now, American Express reports. Wall Street is penciling in EPS of about $4.39, up roughly 8% from a year ago. Shane’s career record spans 41 stocks and 1,359 price targets, hitting 63.81% overall. On American Express specifically, his last 33 targets have landed 30 times, a 90.91% rate. That’s the best mark on the stock among the analysts named here today. AnaChart’s own consensus across American Express’s 21 covered analysts sits at $360.22. That’s a potential upside of just 2.75% from Friday’s $350.58 close. Shane’s new $400 sits nearly $40 above that consensus, the widest gap of any desk named here.
HOKA and UGG’s Spring Growth Brings Jefferies Back to Buy on Deckers Outdoor
Deckers Outdoor designs and sells footwear. Its two largest brands are HOKA running shoes and UGG boots. Its fourth quarter numbers, reported back in May, showed HOKA sales up 14.5% to $671.2 million. UGG sales were up 9.2%, to $408.6 million. The company raised its full year revenue outlook to $5.4 billion to $5.425 billion on the back of it. That didn’t stop a stretch of downgrades the same month. More than one desk cut its rating on valuation and margin concerns, not a demand problem. Blake Anderson of Jefferies reversed course this morning. He upgraded the stock from Hold to Buy and raised his target from $110 to $130. It’s the first upgrade on the name since that May stretch of cuts.
Anderson’s new $130 still sits well under the Street’s high number. At UBS, Jay Sole has held a Buy at $161 since July 2022, the top target on the stock. His hit rate on Deckers runs to just 32.14% across 28 calls. That’s the softest record of the bulls named here. A $141 Buy from Barclays’ Adrienne Yih carries a stronger 46.67% rate across 15 targets. Better still is Needham’s Tom Nikic, at $138. His 74.07% mark across 27 calls is the best of the bulls. Truist’s Joseph Civello, at $125, has landed 63.64% of his 11 calls. The lone Hold in the group belongs to Wells Fargo‘s Ike Boruchow, at $90, the lowest number on the stock. His call is backed by an 80% hit rate. Across 15 targets, that’s the second best mark of anyone named here.
Where Anderson’s New Target Ranks Among The Bulls
Sole’s case for $161 draws on the same brand data Anderson is reading today. HOKA’s mid teens growth guide and UGG’s mid single digit guide are both holding through a full fiscal year. To Anderson, that points to a company still taking share in running shoes, one that deserves a higher multiple. Boruchow’s Hold argues something narrower. He points to Deckers’ operating margin. It’s been under pressure from freight and promotional costs, even while the top line holds up. He says a premium multiple needs both to work. Anderson’s own best call on record happens to be on this exact stock. It’s a $105 target from January that was reached within three days. His upgrade this morning puts him closer to Sole’s camp than Boruchow’s.
Deckers reports first quarter fiscal 2027 results on July 23. That’s one day before American Express. It will be the first print investors get after four rating changes on the stock. All four landed inside of ten weeks. Anderson’s own coverage book is thin, just 18 price targets across four stocks. But it carries a 75% hit rate. Deckers’ own rating mix runs 34 Buy, 26 Hold, and 7 Sell out of 67. Friday’s close was $105.99, against AnaChart’s consensus target of $122.
Truist, JPMorgan, and Jefferies made today’s calls. They worked alongside nine other desks: Morgan Stanley, RBC, UBS, Evercore, Barclays, TD Cowen, BTIG, Needham, and Wells Fargo. AnaChart’s dataset now runs to 661,383 price targets and 759,654 ratings. That’s from 7,191 analysts, tracking 9,686 tickers back to 2008. For the full record behind every analyst named today, the analyst price target dataset has the complete history.