Nike, Darden, Meta Price Targets, September 25 2026
Nike (NKE)
Nike designs, develops, markets and sells athletic footwear, apparel and equipment. It sells under the Nike, Jordan and Converse names. Sales span North America, Europe, Greater China and beyond. The company employs roughly 73,000 people. Its market cap sits near $53.4 billion, down by nearly half over the past year. The multi-year “Win Now” turnaround is dragging on longer than hoped.
Nike reports fiscal first-quarter results October 1, after the closing bell. Wall Street models $0.44 in earnings per share on $11.35 billion in revenue. That would mark a step down. Nike beat expectations outright last time. EPS came in at $0.20 against a $0.12 consensus, an eight-cent beat. Revenue landed at $11 billion versus $10.85 billion expected. Revenue over the trailing twelve months sits at $46.40 billion, roughly flat against a year ago. Net income came in at $3.11 billion for the same period, a small decline from a year earlier.
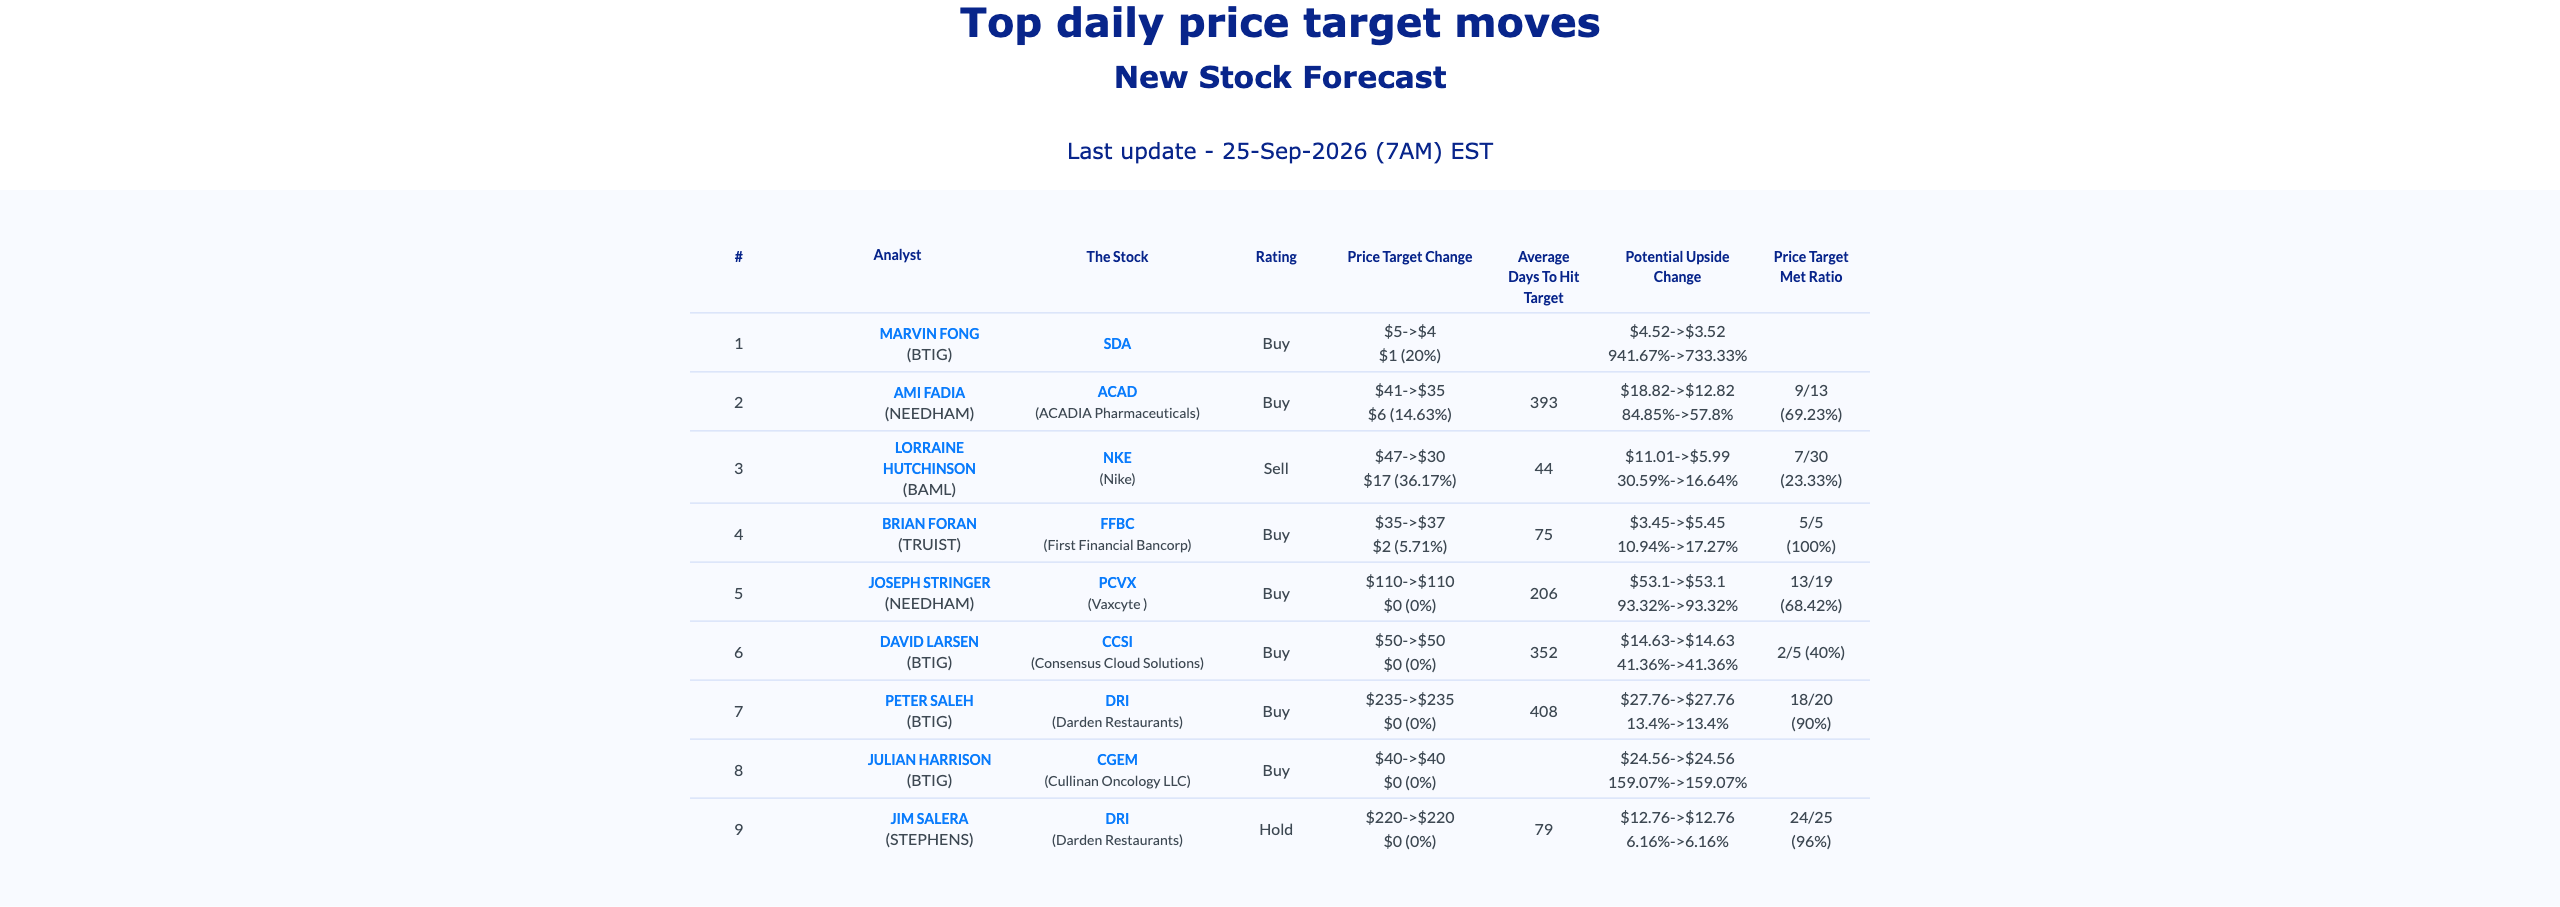
The week has not gone Nike’s way off the field either. Soccer star Kylian Mbappé ended his nearly two-decade partnership with the brand. He signed with rival On Holding instead. It is a symbolic loss during a stretch that has already put Nike’s spot in the Dow Jones Industrial Average in question. Lorraine Hutchinson of BofA Securities downgraded Nike from Neutral to Underperform today, six days ahead of the print. She cut her price target from $47 to $30. That is a reduction of more than a third. It is now the lowest active target AnaChart has on file for the stock.
Hutchinson’s downgrade against BTIG’s $55 target
Hutchinson’s full 38-stock apparel and retail coverage book converts at 68.28%. Her calls have carried an average upside of 22.63%, realized in an average of 312 days, per AnaChart’s database. She has covered Nike since a Buy call in July 2021, one name among 38 on her list. Her new $30 target sits well below Robert Drbul of BTIG. Drbul reiterated a Buy rating and a $55 price target on Nike Wednesday, the highest active number tracked on the stock. His price targets across his 31-stock book have been met 13 of 31 times, a 41.94% rate. That comes over an average 505-day stretch. The $25 gap between his target and Hutchinson’s new one is the widest split logged on Nike in months.
Darden Restaurants (DRI)
Darden owns and operates Olive Garden, LongHorn Steakhouse, Cheddar’s Scratch Kitchen, Yard House and Ruth’s Chris Steak House. It also runs The Capital Grille and several smaller full-service chains. All of it spans the United States and Canada. The company employs more than 209,000 people, with a market cap near $23.5 billion.
Darden reported fiscal first-quarter results Thursday before the opening bell. Earnings per share came in at $2.05, in line with the $2.05 consensus. Revenue landed at $3.2 billion against a $3.21 billion estimate, a slight miss. Same-restaurant sales grew 5.1% and turned positive across every segment. Olive Garden and LongHorn were again the biggest contributors to that growth. Management reaffirmed its full-year earnings guidance on the call. GAAP net income for the quarter came to $233.4 million. That is a step below the $257.8 million booked a year earlier, mostly on higher food and labor costs.
Two analysts weighed in on Darden today without moving their numbers. Peter Saleh of BTIG reiterated his Buy rating and kept his price target at $235. Jim Salera of Stephens & Co. reiterated his Equal-Weight rating and kept his target at $220. Both notes followed the same in-line quarter. They landed on opposite sides of Darden’s Buy-Hold split.
Saleh’s higher hit rate against Salera’s faster one
Saleh’s price targets have been met on 72.66% of his calls, across a 31-stock restaurant and consumer book. His average realized upside runs 27.25% over 379 days. His full 20-stock coverage list converts at 45.43%, achieved in an average of 42 days when it does hit. That’s a far faster turnaround than Saleh’s. The $15 gap between their two Darden targets has held for weeks now.
Meta Platforms (META)
Meta operates through two segments, Family of Apps and Reality Labs. Family of Apps runs Facebook, Instagram, WhatsApp and Threads. Reality Labs builds the company’s VR headsets and AI-enabled glasses. The company employs nearly 79,000 people. It carries a market cap near $1.98 trillion. Second-quarter revenue reached $60.80 billion, a 28% increase from a year earlier and above Wall Street’s model. EPS missed on the same report. Meta also introduced camera-free Ray-Ban Meta Audio glasses and a pocket-sized companion device called Muse Charm this week. That hardware push sits alongside roughly $145 billion in planned AI infrastructure spending this year. Much of the recent attention centers on Muse, Meta’s new AI agent. It reached the top of Apple’s app store following last week’s Meta Connect event.
Two more analysts raised their price targets on Meta today. Thomas Champion of Piper Sandler maintained his Overweight rating. He raised his price target from $785 to $875. Maria Ripps of Canaccord Genuity kept her Buy rating and raised hers from $930 to $950, citing strengthening momentum behind Muse.
Meta is Ripps’ best-performing call
Champion’s full 43-stock internet and communications book converts at 67.4%. His average realized upside runs 19.12% inside 180 days. His calls on Meta specifically have averaged a 15.05% upside. Ripps runs a smaller, more concentrated list of 35 stocks. She hits at a 62.99% rate. Meta is her single best-performing name by average upside, at 31.58%, well above her book-wide average. Her new $950 target is now the higher of the two active numbers.
Every price target above is scored the same way, across more than 9,600 tickers, reached or not reached. The full file, updated daily, is available for download at the AnaChart store, alongside the underlying ratings history for every analyst named above. Each figure comes from the analyst’s own published note. AnaChart matches it against its own record of whether that call was eventually met, ticker by ticker, analyst by analyst.