
The analyst price target moves we wrote up each trading day in September 2024, 20 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
September 3, 2024: Selected stock price target news of the day: September 3rd, 2024
By: Matthew Otto
Elastic N.V. Surpasses Q1 Earnings Expectations but Issues Conservative Guidance
Elastic N.V. delivered its financial performance for the first quarter of fiscal year 2025, reporting earnings per share (EPS) of $0.35, which outperformed the analyst consensus estimate of $0.25 by $0.10. Revenue for the quarter also exceeded expectations, coming in at $347 million, slightly above the consensus estimate of $344.66 million. Cloud revenue rose by 30% to $157 million, now representing 45% of the total revenue. Additionally, Elastic's non-GAAP operating margin reached 10.7%.
However, despite the Q1 performance, Elastic’s guidance for the second quarter of FY2025 anticipates EPS to range between $0.37 and $0.39, slightly above the analyst consensus of $0.34. On the revenue side, Elastic projects Q2 revenues between $353 million and $355 million, which is below the consensus estimate of $360.8 million.
Looking at the full fiscal year, Elastic provided guidance for EPS to be in the range of $1.52 to $1.56, which beats the consensus estimate of $1.42. Revenue forecast for FY2025 is between $1.436 billion and $1.444 billion, falling short of the analyst consensus of $1.478 billion.
Analysts Lower Price Targets Despite Mixed Q1 Results
- DA Davidson analyst Gil Luria maintained a Neutral rating but lowered the price target from $100 to $75.
- Jefferies analyst Brent Thill maintained a Buy rating; however, reduced the price target from $140 to $110.
- Needham analyst Mike Cikos reiterated a Hold rating.
- Scotiabank analyst Patrick Colville maintained a Sector Outperform rating yet lowered the price target from $135 to $92.
- Barclays analyst Raimo Lenschow kept an Equal-Weight rating while reducing the price target from $117 to $106.
- RBC Capital analyst Matthew Hedberg maintained an Outperform rating but lowered the price target from $135 to $110.
- UBS analyst Austin Dietz held a Buy rating, although cut the price target from $135 to $95.
- Wells Fargo analyst Andrew Nowinski kept an Overweight rating while reducing the price target from $145 to $100.
- Piper Sandler analyst Rob Owens maintained an Overweight rating but lowered the price target from $131 to $100.
- Stifel analyst Brad Reback continued with a Buy rating; however, reduced the price target from $120 to $98.
Which Analyst has the best track record to show on ESTC?
Analyst Brent Thill (JEFFERIES) currently has the highest performing score on ESTC with 17/18 (94.44%) price target fulfillment ratio. His price targets carry an average of $33.81 (44.38%) potential upside. Elastic N.V. stock price reaches these price targets on average within 221 days.
Ulta Beauty Reports Q2 Earnings Miss, Lowers Full-Year Guidance
Ulta Beauty reported its second-quarter financial results, revealing an earnings per share (EPS) of $5.30, which was $0.21 below the analyst estimate of $5.51. Revenue for the quarter came in at $2.55 billion, falling short of the $2.62 billion consensus estimate. Net sales increased by 0.9% to $2.6 billion, while comparable store sales decreased by 1.2%. Despite an increase in e-commerce sales, overall store transactions declined.
Ulta Beauty revised its full-year guidance downward, anticipating full-year EPS to range between $22.60 and $23.50, compared to the previous consensus of $25.26. Similarly, Ulta adjusted its full-year revenue forecast to a range of $11 billion to $11.2 billion, down from the earlier consensus estimate of $11.495 billion.
Analysts Adjust Ratings and Targets Following Q2 Earnings Miss
- Loop Capital analyst Anthony Chukumba maintained a Buy rating; however, lowered the price target from $520 to $450.
- DA Davidson analyst Michael Baker maintained a Buy rating while reducing the price target from $507 to $435.
- Telsey Advisory Group analyst Dana Telsey kept an Outperform rating and lowered the price target from $500 to $450.
- Citigroup analyst Kelly Crago maintained a Neutral rating yet cut the price target from $375 to $345.
- Canaccord Genuity analyst Susan Anderson remained with a Buy rating, but reduced the price target from $500 to $442.
- Barclays analyst Adrienne Yih maintained an Equal-Weight rating, though raised the price target from $328 to $335.
- UBS analyst Michael Lasser continued with a Buy rating, although lowered the price target from $550 to $505.
- BMO Capital analyst Simeon Siegel kept a Market Perform rating but reduced the price target from $500 to $385.
- Piper Sandler analyst Korinne Wolfmeyer reiterated a Neutral rating and lowered the price target from $404 to $356.
- Wells Fargo analyst Ike Boruchow maintained an Underweight rating, and reduced the price target from $325 to $300.
Which Analyst has the best track record to show on ULTA?
Analyst Ike Boruchow (WELLS FARGO) currently has the highest performing score on ULTA with 29/30 (96.67%) price target fulfillment ratio. His price targets carry an average of $-52.84 (-14.98%) potential downside. Ulta Beauty stock price reaches these price targets on average within 109 days.
MongoDB Reports Q2 Revenue and EPS Beat, Raises FY2025 Guidance
MongoDB reported its financial performance for the second quarter of fiscal year 2025, achieving earnings per share (EPS) of $0.70, exceeding the consensus estimate of $0.49 by $0.21. Revenue for the quarter was $478.1 million, exceeding the consensus estimate of $464.94 million. This marked a 13% year-over-year increase.
MongoDB’s cloud-based offering, Atlas, which saw a 27% year-over-year revenue increase, accounting for 71% of total revenue. MongoDB's non-GAAP operating income reached $52.5 million, translating to an 11% operating margin. MongoDB ended the quarter with over 50,700 customers.
Looking ahead, MongoDB expects Q3 2025 EPS to be between $0.65 and $0.68, surpassing the consensus estimate of $0.60. Revenue for Q3 is projected to range from $493 million to $497 million, above the consensus of $478.8 million.
For the full fiscal year 2025, MongoDB anticipates EPS between $2.33 and $2.47, compared to the consensus estimate of $2.26. Revenue for FY2025 is expected to be between $1.92 billion and $1.93 billion, exceeding the consensus of $1.9 billion.
Analysts Boost Price Targets After Q2 Performance
- DA Davidson analyst Rudy Kessinger maintained a Buy rating and raised the price target from $265 to $330.
- Bernstein analyst Firoz Valliji kept an Outperform rating and increased the price target from $358 to $360.
- JMP Securities analyst Patrick Walravens reiterated a Market Outperform rating and a $380 price target.
- Needham analyst Mike Cikos continued to recommend a Buy and raised the price target from $290 to $335.
- Scotiabank analyst Patrick Colville maintained a Sector Perform rating, but lifted the price target from $250 to $295.
- RBC Capital analyst Rishi Jaluria reiterated an Outperform rating and a price target of $350.
- UBS analyst Karl Keirstead kept a Neutral rating and raised the price target from $250 to $275.
- Wells Fargo analyst Andrew Nowinski maintained an Overweight rating and increased the price target from $300 to $350.
Which Analyst has the best track record to show on MDB?
Analyst David Hynes (CANACCORD) currently has the highest performing score on MDB with 11/13 (84.62%) price target fulfillment ratio. His price targets carry an average of $88.94 (37.68%) potential upside. MongoDB stock price reaches these price targets on average within 79 days.
Daily stock Analysts Top Price Moves Snapshot

September 4, 2024: Selected stock price target news of the day: September 4th, 2024
By: Matthew Otto
Zscaler Crushes Q4 Earnings Expectations but Issues Cautious FY2025 Guidance
Zscaler delivered its Q4 performance, reporting earnings per share (EPS) for the quarter of $0.88, surpassing the analyst consensus estimate of $0.70 by $0.18. Revenue for the quarter reached $592.9 million, exceeding the consensus estimate of $567.46 million.
Zscaler achieved $1 billion in quarterly bookings, and billings also rose 27% year-over-year, while operating margins reached approximately 22%. For the full fiscal year, revenue grew by 34%, and free cash flow increased by 75%, with a 27% free cash flow margin. Zscaler also reported $2.5 billion in annual recurring revenue (ARR) in Q4 and expects to achieve $3 billion or more in ARR in fiscal 2025.
Despite the performance, Zscaler's guidance for FY2025 projects EPS to be in the range of $2.81 to $2.87, which falls below the consensus estimate of $3.01. For revenue, Zscaler estimates between $2.6 billion and $2.62 billion, aligning closely with the consensus estimate of $2.62 billion.
Looking ahead to Q1 2025, Zscaler expects EPS to be between $0.62 and $0.63, which is lower than the analyst consensus of $0.73. However, the company anticipates Q1 2025 revenue to be in the range of $604 million to $606 million, slightly above the consensus estimate of $603 million.
Analysts Reacts to Q4 Results with Mixed Price Target Adjustments
- Cantor Fitzgerald analyst Yi Fu Lee maintained a Neutral rating, yet lowered the price target from $200 to $170.
- Loop Capital analyst Yun Kim maintained a Hold rating while reducing the price target from $180 to $165.
- Baird analyst Shrenik Kothari maintained an Outperform rating, although lowering the price target from $260 to $225.
- Needham analyst Alex Henderson kept a Strong Buy rating but revised the price target downward from $290 to $235.
Which Analyst has the best track record to show on ZS?
Analyst Keith Bachman (BMO) currently has the highest performing score on ZS with 16/21 (76.19%) price target fulfillment ratio. His price targets carry an average of $23.78 (12.91%) potential upside. Zscaler stock price reaches these price targets on average within 94 days.
Asana Beats Q2 Estimates, Weak Outlook Overshadows Earnings Call
Asana reported its fiscal second quarter of 2025, posting an EPS of ($0.05), which was $0.03 better than the analyst estimate of ($0.08). Also reported revenue of $179.2 million, slightly above the consensus estimate of $177.68 million.
Looking ahead, For Q3, Asana expects revenue between $180.0 million and $181.0 million, representing 8% to 9% year-over-year growth. A non-GAAP operating loss of $19.0 million to $18.0 million, equating to a 10% operating loss margin at the midpoint. Anticipates a non-GAAP net loss per share of $0.07, based on approximately 227 million shares outstanding.
For the full fiscal year 2025, Asana projects revenue between $719.0 million and $721.0 million, indicating a 10% year-over-year increase. A non-GAAP operating loss of $58.0 million to $55.0 million, with an 8% operating loss margin at the midpoint. Also expects a non-GAAP net loss per share ranging from $0.20 to $0.19.
Analysts Adjust Ratings and Price Targets Following Q2 Earnings
- RBC Capital analyst Rishi Jaluria reiterated an Underperform rating with a $10 price target.
- BofA Securities analyst Michael Funk maintained a Buy rating; however, reduced the price target from $18 to $16.
- Baird analyst Rob Oliver kept a Neutral rating, and cut the price target from $20 to $13.
- Piper Sandler analyst Brent Bracelin maintained a Neutral rating but lowered the price target from $14 to $12.
Which Analyst has the best track record to show on ASAN?
Analyst Brent Thill (JEFFERIES) currently has the highest performing score on ASAN with 12/13 (92.31%) price target fulfillment ratio. His price targets carry an average of $2.95 (22.61%) potential upside. Asana stock price reaches these price targets on average within 17 days.
GitLab Exceeds Earnings and Revenue Expectations for Q2 FY25, Raises Full-Year Guidance
GitLab reported its second quarter of fiscal year 2025, with earnings per share (EPS) of $0.15, surpassing the analyst estimate of $0.10 by $0.05. Revenue for the quarter reached $182.6 million, exceeding the consensus estimate of $176.88 million.
GitLab’s non-GAAP operating margin expanded by over 1,300 basis points year-over-year to 10%. The dollar-based net retention rate (DBNRR) was 126%, driven by 40% seat expansion, 50% increased customer yield, and 10% tier upgrades. GitLab also saw a 51% year-over-year increase in total remaining performance obligations (RPO) to $747.9 million and a 42% rise in current RPO (cRPO) to $475 million. GitLab’s SaaS revenue grew by 46%, now constituting 28% of total revenue.
For the third quarter of FY25, GitLab forecasts EPS of $0.15 to $0.16, exceeding the consensus estimate of $0.11, and expects revenue between $187 million and $188 million, slightly above the consensus of $187 million. Full-year FY25 guidance includes revenue expectations of $742 million to $744 million, surpassing the consensus of $736 million, and an EPS forecast of $0.45 to $0.47, above the consensus estimate of $0.36. Also reported a reduction in non-GAAP expenses related to its China joint venture, JiHu, forecasting approximately $14 million for FY25 compared to $18 million in the prior year.
Analysts Boost Price Targets Following Strong Q2 Earnings
- Wells Fargo analyst Michael Turrin maintained an Overweight rating and raised the price target from $70 to $75.
- Scotiabank analyst Nick Altmann retained a Sector Outperform rating and lifted the price target from $59 to $65.
- BofA Securities analyst Koji Ikeda continued to rate a Buy rating, while increasing the price target from $66 to $68.
- Baird analyst Shrenik Kothari kept an Outperform rating and adjusted the price target up from $59 to $62.
- Needham analyst Mike Cikos reaffirmed a Hold rating.
Which Analyst has the best track record to show on GTLB?
Analyst Matthew Hedberg (RBC) currently has the highest performing score on GTLB with 13/19 (68.42%) price target fulfillment ratio. His price targets carry an average of $11.99 (22.62%) potential upside. GitLab stock price reaches these price targets on average within 163 days.
Daily stock Analysts Top Price Moves Snapshot

September 5, 2024: Selected stock price target news of the day: September 5th, 2024
By: Matthew Otto
Ascendis Pharma Reports Lower Q2 Revenue and Revises Full-Year SKYTROFA Guidance
Ascendis Pharma held its second quarter 2024 earnings call, reporting a net loss per share (EPS) of $(2.06), which was $0.60 worse than the analyst estimate of $(1.46). Revenue for the quarter was $39 million, below the consensus estimate of $91 million.
In terms of financial guidance, Ascendis revised its full-year 2024 SKYTROFA revenue expectations to $240 million to $261 million, down from the previous range of $349 million to $371 million, and below the estimated $382 million. For the second quarter, SKYTROFA generated $28 million in revenue, representing a 27% year-over-year decrease, attributed to higher sales deductions.
Ascendis closed the quarter with $284 million in cash, cash equivalents, and marketable securities and secured an additional $150 million in funding through a synthetic royalty agreement with Royalty Pharma
Analyst Ratings Adjust Amid Q2 Revenue Miss and Revised Guidance
- Oppenheimer analyst Leland Gershell upgraded from Perform to Outperform and set a $180 price target.
- Citigroup analyst David Lebowitz maintained a Buy rating but lowered the price target from $193 to $178.
- JP Morgan analyst Jessica Fye retained an Overweight rating, though reduced the price target from $174 to $165.
- TD Cowen analyst Yaron Werber kept a Buy rating yet decreased the price target from $175 to $157.
- BofA Securities analyst Tazeen Ahmad maintained a Buy rating and raised the price target from $165 to $175.
- Wells Fargo analyst Derek Archila kept an Overweight rating, however adjusted the price target down from $277 to $264.
- Cantor Fitzgerald analyst Li Watsek continued an Overweight rating, while trimming the price target from $173 to $170.
Which Analyst has the best track record to show on ASND?
Analyst Jessica Fye (JPMORGAN) currently has the highest performing score on ASND with 14/17 (82.35%) price target fulfillment ratio. Her price targets carry an average of $37 (27.01%) potential upside. Ascendis Pharma stock price reaches these price targets on average within 120 days.
Dollar Tree Lowers Full-Year Guidance After Disappointing Q2 Results
Dollar Tree now expects its consolidated net sales for the fiscal year 2025 to range between $30.6 billion and $30.9 billion, a reduction from the previous estimate of $31.19 billion. Adjusted earnings per share (EPS) are projected to be between $5.20 and $5.60, compared to the consensus estimate of $6.55. The downward revision reflects ongoing sales struggles and increased costs related to store conversions and legal claims.
For the second quarter ended August 3, Dollar Tree reported an EPS of $0.67, falling short of the analyst estimate of $1.06, and revenue of $7.37 billion, below the consensus of $7.5 billion.
Same-store sales rose by 0.7% during the quarter, with Dollar Tree stores up by 1.3% and Family Dollar experiencing a 0.1% decline. In March, Dollar Tree announced plans to close approximately 1,000 Family Dollar stores and is considering selling the brand.
Analysts Cut Targets Following Q2 Results and Revised Guidance
- Evercore ISI Group analyst Greg Melich maintained a rating of In-Line and lowered the price target from $128 to $78.
- Morgan Stanley analyst Simeon Gutman kept a rating of Equal-Weight but reduced the price target from $130 to $80.
- Loop Capital analyst Anthony Chukumba downgraded from Buy to Hold and set a new price target of $65.
- Keybanc analyst Bradley Thomas maintained an Overweight rating, yet lowered the price target from $145 to $84.
- Piper Sandler analyst Peter Keith remained Neutral but decreased the price target from $112 to $67.
- BMO Capital analyst Kelly Bania downgraded from Outperform to Market Perform and adjusted the price target from $130 to $68.
- JP Morgan analyst Matthew Boss downgraded from Overweight to Neutral and the price target from $111 to $70.
Which Analyst has the best track record to show on DLTR?
Analyst Joseph Feldman (TELSEY ADVISORY) currently has the highest performing score on DLTR with 8/26 (30.77%) price target fulfillment ratio. His price targets carry an average of $35.51 (42.03%) potential upside. Dollar Tree stock price reaches these price targets on average within 105 days.
Couchbase Falls Short of Revenue and ARR Expectations Despite Strong Q2 Performance
Couchbase reported results for the second quarter of 2025, with an earnings per share (EPS) of ($0.06), surpassing the analyst estimate of ($0.09) by $0.03. Achieved revenue of $51.6 million for the quarter, exceeding the consensus estimate of $51.11 million. This revenue figure represents a 20% increase year-over-year.
The annual recurring revenue (ARR) stood at $214 million, reflecting an 18% increase from the previous year and a 19% rise in constant currency. However, the non-GAAP operating loss was $4.1 million, resulting in an 8% operating margin that was above the company’s guidance range.
Couchbase’s Capella platform also demonstrated its performance, with Capella ARR reaching $28.9 million, up 20% and representing 13.5% of total ARR. Capella’s customer base grew by 37 during the quarter.
Looking ahead, Couchbase has provided guidance for the third quarter of 2025, forecasting revenue between $50.3 million and $51.1 million, which is below the consensus estimate of $50.687 million. For the full fiscal year 2025, Couchbase anticipates revenue to be in the range of $205.1 million to $209.1 million, compared to the consensus estimate of $207.3 million.
Analysts Slash Price Targets After Q2 Performance
- UBS analyst Austin Dietz maintained a Neutral rating, but lowered the price target from $24 to $19.
- Morgan Stanley analyst Sanjit Singh kept an Equal-Weight rating, but reduced the price target from $29 to $27.
- Stifel analyst Brad Reback retained a Buy rating and revised the price target from $25 to $20.
- Baird analyst Rob Oliver maintained an Outperform rating while adjusting the price target from $32 to $27.
- Needham analyst Mike Cikos reaffirmed a Buy rating and a $22 price target.
- Piper Sandler analyst Brent Bracelin kept an Overweight rating, but lowered the price target from $22 to $21.
Which Analyst has the best track record to show on BASE?
Analyst Kash Rangan (GOLDMAN SACHS) currently has the highest performing score on BASE with 3/6 (50%) price target fulfillment ratio. His price targets carry an average of $-0.41 (-2.23%) potential downside. Couchbase stock price reaches these price targets on average within 59 days.
Daily stock Analysts Top Price Moves Snapshot

September 6, 2024: Selected stock price target news of the day: September 6th, 2024
By: Matthew Otto
Dick's Sporting Goods Reports Strong Q2 Performance and Updates Full-Year Outlook
Dick’s Sporting Goods reported its financial results for the second quarter of 2024, with an earnings per share (EPS) of $4.37, surpassing the analyst estimate of $3.83 by $0.54. Net sales for the quarter came in at $3.47 billion, slightly above the consensus estimate of $3.44 billion.
Comparable-store sales rose 4.5%, driven by a 3.5% increase in average ticket size and a 1% rise in transactions. Gross profit for the quarter was $1.28 billion, or 36.73% of net sales, supported by a 169 basis point improvement in merchandise margins and 83 basis points from reduced inventory shrinkage. Dick’s Sporting Goods ended the quarter with $1.7 billion in cash and no borrowings on its $1.6 billion unsecured credit facility.
Looking forward, Dicks’ Sporting Goods now expects fiscal year 2025 EPS to be between $13.55 and $13.90, compared to the consensus estimate of $13.79. Revenue is anticipated to be between $13.1 billion and $13.2 billion, slightly below the consensus of $13.23 billion.
Analysts Adjust Price Targets Following Q2 Performance and Outlook
- Citigroup analyst Paul Lejuez Maintained a Neutral rating while lowering the price target from $243 to $230.
- Evercore ISI Group analyst Warren Cheng Maintained an Outperform rating and the price target at $280.
- Loop Capital analyst Anthony Chukumba Kept a Hold rating but raised the price target from $200 to $220.
- BofA Securities analyst Robert Ohmes Kept a Buy rating and increased the price target from $240 to $250.
- Barclays analyst Adrienne Yih Maintained an Overweight rating while raising the price target from $247 to $254.
- DA Davidson analyst Michael Baker Held a Buy rating and a $265 price target.
- Wedbush analyst Seth Basham Reiterated a Neutral rating and the price target at $250.
- Telsey Advisory Group analyst Joseph Feldman Retained an Outperform rating and the price target at $260.
Which Analyst has the best track record to show on DKS?
Analyst Seth Basham (WEDBUSH) currently has the highest performing score on DKS with 19/20 (95%) price target fulfillment ratio. His price targets carry an average of $15.03 (6.40%) potential upside. Dick’s Sporting Goods stock price reaches these price targets on average within 192 days.
C3.ai Misses Q1 Subscription Revenue Estimates, Guidance Below Analyst Expectations
C3.ai missed its quarterly subscription revenue estimates for the first quarter, reporting $73.5 million in subscription revenue, falling short of the $79.1 million forecasted by analysts, according to LSEG data. However, it exceeded revenue expectations, posting total revenue of $87.2 million compared to the consensus estimate of $86.94 million. Additionally, it reported a Q1 EPS of ($0.05), which was $0.08 better than the analyst estimate of ($0.13).
Looking ahead, C3.ai has provided guidance for the second quarter of fiscal year 2025, expecting revenue to range between $88.6 million and $93.6 million, which is slightly below the consensus estimate of $91 million. For the full fiscal year 2025, it forecasts revenue between $370 million and $395 million, below the consensus estimate of $383.4 million.
Analyst Ratings Diverge After Q1 Revenue and Lowered Guidance
- Oppenheimer analyst Timothy Horan maintained an Outperform rating and a $40 price target.
- JMP Securities analyst Joe Goodwin reiterated a Market Outperform rating and a $40 price target.
- BofA Securities analyst Brad Sills retained an Underperform rating, but reduced the price target from $24 to $20.
- DA Davidson analyst Gil Luria kept a Neutral stance and lowered the price target from $30 to $20.
- Wedbush analyst Daniel Ives continued with an Outperform rating, though adjusted the price target from $40 to $30.
- Morgan Stanley analyst Sanjit Singh maintained an Underweight rating and decreased the price target from $23 to $21.
- Needham analyst Mike Cikos reiterated a Hold rating.
- Piper Sandler analyst Arvind Ramnani kept a Neutral rating, while lowering the price target from $29 to $24.
Which Analyst has the best track record to show on AI?
Analyst David Hynes (CANACCORD) currently has the highest performing score on AI with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $1.43 (5.01%) potential upside. C3.ai stock price reaches these price targets on average within 40 days.
Sprinklr Reports Q2 FY 2025 Earnings: Revenue Exceeds Expectations, EPS Falls Short of Estimates
Sprinklr reported its second-quarter fiscal year 2025 earnings with total revenue of $197.2 million, surpassing the consensus estimate of $194.51 million. However, earnings per share (EPS) of $0.06 fell short of the analyst estimate of $0.07.
Subscription revenue for the quarter increased by 9% year-over-year to $177.9 million, contributing to an 11% overall revenue growth. The non-GAAP operating income was $15.2 million, equating to an 8% non-GAAP operating margin, though results were affected by a $10.1 million credit loss charge. Free cash flow remained at $16.5 million, and cash and equivalents stood at $468.5 million with no debt.
For the third quarter of fiscal year 2025, Sprinklr has projected revenue between $196 million and $197 million, slightly above the consensus of $193.8 million. Anticipates EPS of approximately $0.08, which is below the consensus estimate of $0.12.
For the full fiscal year, Sprinklr expects revenue in the range of $785 million to $787 million, compared to the consensus of $780.4 million. EPS guidance for FY 2025 is between $0.32 and $0.33, falling short of the consensus estimate of $0.41.
Analysts Adjust Targets After Q2 Earnings Miss and Revenue Beat
- Citigroup analyst Tyler Radke maintained a Neutral rating, while reducing the price target from $11 to $9.
- JMP Securities analyst Patrick Walravens reiterated a Market Outperform rating and the price target at $17.
- Wells Fargo analyst Michael Berg held an Equal-Weight rating, but lowered the price target from $9 to $8.
- Barclays analyst Raimo Lenschow maintained an Overweight rating, although adjusted the price target from $11 to $10.
- DA Davidson analyst Gil Luria kept a Neutral rating and revised the price target from $9 to $8.
- Cantor Fitzgerald analyst Brett Knoblauch maintained a Neutral stance and reduced the price target from $10 to $9.
- Keybanc analyst Jason Ader retained an Overweight rating, yet lowered the price target from $16 to $12.
- Morgan Stanley analyst Elizabeth Porter maintained an Equal-Weight rating and reduced the price target from $12 to $10.
Which Analyst has the best track record to show on CXM?
Analyst Michael Turrin (WELLS FARGO) currently has the highest performing score on CXM with 9/11 (81.82%) price target fulfillment ratio. His price targets carry an average of $0.27 (3.09%) potential upside. Sprinklr stock price reaches these price targets on average within 63 days.
Daily stock Analysts Top Price Moves Snapshot

September 9, 2024: Selected stock price target news of the day: September 9th, 2024
By: Matthew Otto
Samsara Reports Q2 Results, Exceeds EPS and Revenue Estimates, and Raises Q3 Guidance
Samsara reported financial results for the second quarter of fiscal 2025, posting earnings per share (EPS) of $0.05, which was $0.04 higher than the consensus estimate of $0.01. Additionally, Samsara’s quarterly revenue reached $300.2 million, exceeding the analyst estimate of $289.53 million.
Samsara’s annual recurring revenue (ARR) increased 36% year-over-year to $1.26 billion. It also expanded its large customer base, adding 169 customers with more than $100,000 in ARR and 14 customers generating over $1 million in ARR. Gross margin tied its quarterly record at 77%, while the non-GAAP operating margin reached a quarterly record of 6%.
Looking ahead, Samsara expects EPS in the range of $0.03 to $0.04, in line with the consensus estimate of $0.03. It also projects revenue between $309 million and $311 million, slightly higher than the consensus estimate of $308.83 million.
Samsara's ongoing product innovations, such as the industrial-grade Asset Tag, contributed approximately $1 million in net new annual contract value (ACV) in Q2, and its international expansion remains with 16% of net new ACV coming from overseas markets. For Fiscal Year 2025, total revenue is expected to range between $1.224 billion and $1.228 billion, representing a year-over-year growth of 33% to 34%.
Analysts Raise Targets Following Q2 Earnings and Upbeat Guidance
- JP Morgan analyst Alexei Gogolev maintained a Neutral rating, while raising the price target from $37 to $40.
- Loop Capital analyst Mark Schappel kept a Buy rating and increased the price target from $42 to $46.
- TD Cowen analyst J. Derrick Wood continued with a Buy rating and boosted the price target from $45 to $46.
- Truist Securities analyst Joel Fishbein kept a Hold rating, but lifted the price target from $35 to $40.
- Morgan Stanley analyst Keith Weiss maintained an Equal-Weight rating and raised the price target from $38 to $40.
- Wells Fargo analyst Michael Turrin retained an Overweight rating and adjusted the price target upward from $42 to $46.
- RBC Capital analyst Matthew Hedberg sustained an Outperform rating and increased the price target from $47 to $49.
- Evercore ISI Group analyst Kirk Materne held an In-Line rating, yet raised the price target from $40 to $42.
- Piper Sandler analyst James Fish kept a Neutral rating, while raising the price target from $36 to $40.
Which Analyst has the best track record to show on IOT?
Analyst Matthew Hedberg (RBC) currently has the highest performing score on IOT with 11/15 (73.33%) price target fulfillment ratio. His price targets carry an average of $4.98 (11.31%) potential upside. Samsara stock price reaches these price targets on average within 134days.
UiPath Exceeds Q2 Expectations and Raises FY2025 Guidance Despite Market Decline
UiPath reported its financial results for the second quarter of fiscal 2025 posting earnings per share (EPS) of $0.04, surpassing the analyst estimate of $0.03. Revenue for the quarter reached $316 million, exceeding the consensus forecast of $303.69 million.
UiPath’s annual recurring revenue (ARR) grew by 19% year-over-year to $1.551 billion. The financial results were also bolstered by its cloud-first approach, with over $850 million in cloud ARR. In addition, UiPath’s board approved a $500 million share repurchase program to enhance shareholder value.
Looking ahead, UiPath expects Q3 revenue between $345 million and $350 million, aligning with analyst estimates of $347.2 million. For full fiscal year 2025, UiPath raised its revenue outlook to a range of $1.42 billion to $1.425 billion, compared to the prior consensus estimate of $1.41 billion.
Analyst Ratings Adjusted Following Q2 Results and Revised Guidance
- DA Davidson’s Gil Luria maintained a Neutral rating and increased the price target from $13 to $15.
- TD Cowen’s Bryan Bergin retained a Hold rating, yet lowered the price target from $17 to $16.
- Morgan Stanley’s Keith Weiss initiated coverage with an Equal-Weight rating and a price target of $15.
- RBC Capital’s Matthew Hedberg continued to rate as Sector Perform and a $16 price target.
- Barclays’ Raimo Lenschow kept an Equal-Weight rating and raised the price target from $14 to $15.
- Wells Fargo’s Michael Turrin maintained an Equal-Weight rating and increased the price target from $14 to $15.
- Evercore ISI Group’s Kirk Materne upheld an In-Line rating and raised the price target from $13 to $16.
Which Analyst has the best track record to show on PATH?
Analyst Kirk Materne (EVERCORE) currently has the highest performing score on PATH with 7/9 (77.78%) price target fulfillment ratio. His price targets carry an average of $4.03 (33.67%) potential upside. UiPath stock price reaches these price targets on average within 126 days.
Smartsheet Exceeds Q2 Expectations with Revenue Growth and Updated FY 2025 Guidance
Smartsheet delivered results for the second quarter of fiscal year 2025, with an earnings per share (EPS) of $0.44, surpassing the consensus estimate of $0.29 by $0.15. Revenue for the quarter was $276.4 million, exceeding the consensus estimate of $274.29 million.
Smartsheet's annual recurring revenue (ARR) stood at $1.093 billion, reflecting a 17% increase year-over-year. Smartsheet saw enterprise growth, with 75 customers expanding their ARR by over $100,000 and three transactions exceeding $1 million. The number of customers with ARR over $1 million grew by 50% to 77, including five government agencies.
Looking ahead, Smartsheet provided guidance for the third quarter of FY 2025, forecasting an EPS range of $0.29 to $0.31, aligning with the consensus of $0.29, and revenue between $282 million and $285 million, slightly below the consensus of $287 million. For the full fiscal year, Smartsheet anticipates an EPS range of $1.36 to $1.39, surpassing the consensus of $1.25, and revenue between $1.116 billion and $1.121 billion, slightly below the consensus of $1.12 billion.
Analysts Upgraded Ratings and Price Targets Following Q2 Report
- Citigroup analyst Tyler Radke maintained a Buy rating and raised the price target from $55 to $63.
- Guggenheim analyst John Difucci continued with a Buy rating and lifted the price target from $60 to $62.
- Canaccord Genuity analyst David Hynes kept a Buy rating and increased the price target from $52 to $60.
- DA Davidson analyst Robert Simmons maintained a Buy rating and the price target steady at $55.
- Truist Securities analyst Terry Tillman remained with a Buy rating and raised the price target from $55 to $60.
- Morgan Stanley analyst Josh Baer maintained an Overweight rating and boosted the price target from $55 to $57.
- RBC Capital analyst Rishi Jaluria continued with a Sector Perform rating and increased the price target from $43 to $51.
- Barclays analyst Ryan Macwilliams maintained an Equal-Weight rating and raised the price target from $45 to $50.
Which Analyst has the best track record to show on SMAR?
Analyst Rishi Jaluria (RBC) currently has the highest performing score on SMAR with 17/19 (89.47%) price target fulfillment ratio. His price targets carry an average of $-1.27 (-2.43%) potential downside. Smartsheet stock price reaches these price targets on average within 19 days.
Daily stock Analysts Top Price Moves Snapshot
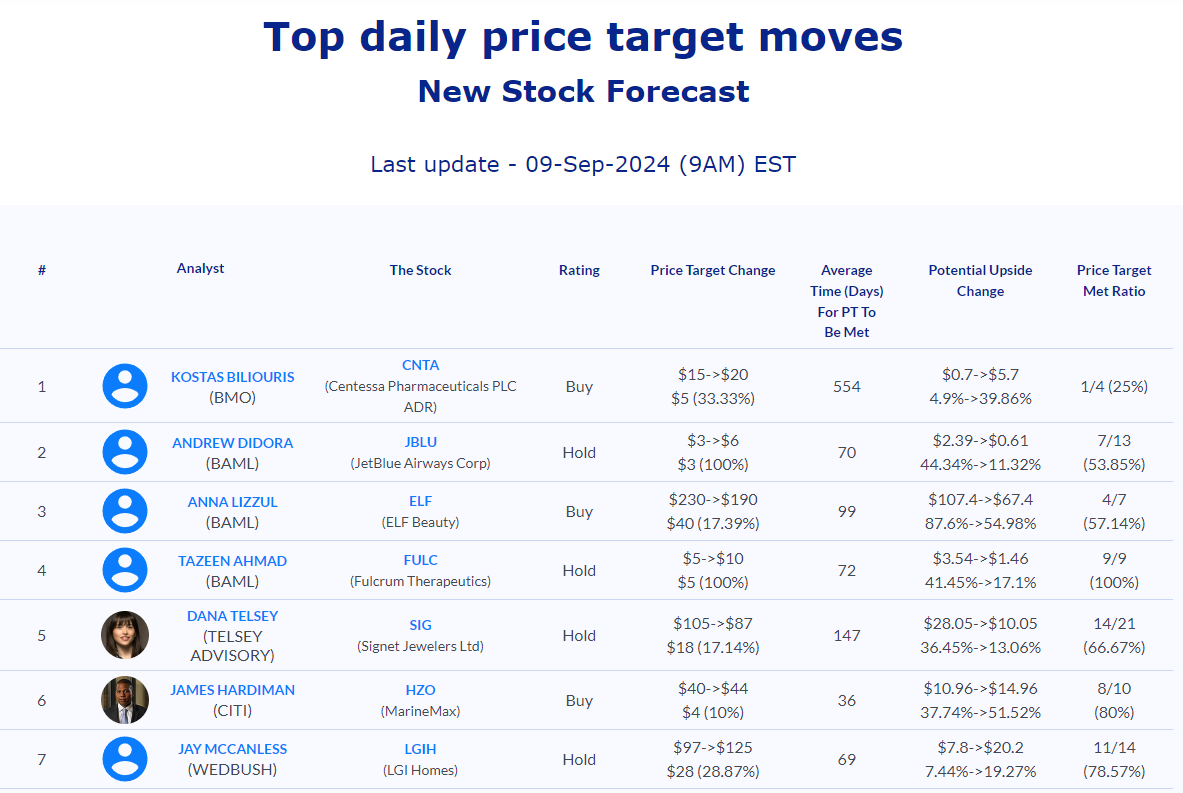
September 10, 2024: Selected stock price target news of the day: September 10th, 2024
By: Matthew Otto
Oracle Surpasses Earnings Expectations, and Secures Key AWS Partnership
Oracle Corporation reported its fiscal first-quarter 2025 earnings, posting adjusted earnings per share (EPS) of $1.39, beating the consensus estimate of $1.33. Total revenue for the quarter was $13.3 billion, slightly ahead of expectations at $13.2 billion.
Oracle’s cloud infrastructure business experienced growth, with revenue rising 45% to $2.2 billion. Additionally, Oracle saw a 10% increase in cloud application revenue, reaching $3.5 billion. These results were driven by AI training capacity on Oracle Cloud Infrastructure (OCI), which grew 49% compared to the previous year. Oracle's recent multi-cloud partnership with Amazon Web Services is expected to further bolster its cloud offerings.
The results have been favorable by Analysts, with D.A. Davidson’s Gil Luria raising the price target from $105 to $140 while maintaining a neutral rating, and Morgan Stanley’s Keith Weiss highlighting Oracle’s outperformance compared to software peers, particularly due to the scarcity in AI hardware.
Looking ahead, the company anticipates total revenue growth of 7% to 9% for the next quarter, with cloud revenue expected to increase by 23% to 25%.
Analysts Boost Price Targets After Strong Q1 Performance
- TD Cowen analyst Derrick Wood maintained a Buy rating and raised the price target from $165 to $180.
- KeyBanc analyst Jason Ader maintained an Overweight rating and lifted the price target from $165 to $175.
- BMO Capital analyst Keith Bachman kept a Market Perform rating while increasing the price target from $160 to $173.
- Morgan Stanley analyst Keith Weiss reiterated an Equal-Weight rating but raised the price target from $125 to $145.
- BofA Securities analyst Brad Sills maintained a Neutral rating and pushed the price target up from $155 to $175.
- JMP Securities analyst Patrick Walravens upgraded from Market Perform to Market Outperform and set a new price target at $175.
- Piper Sandler analyst Brent Bracelin held an Overweight rating while raising the price target from $150 to $175.
Which Analyst has the best track record to show on ORCL?
Analyst Tyler Radke (CITI) currently has the highest performing score on ORCL with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $-0.38 (-0.27%) potential downside. Oracle Corporation stock price reaches these price targets on average within 104 days.
ABM Industries Exceeds Q3 Earnings Expectations and Raises 2024 Outlook
ABM Industries reported third-quarter 2024 earnings, with an EPS of $0.94, beating the analyst estimate of $0.86 by $0.08. Generated $2.1 billion in revenue for the quarter, surpassing the consensus estimate of $2.04 billion.
The Aviation segment saw a 13% revenue boost, while Technical Solutions grew by 25%, supported by microgrid project activity.Despite a slight decline in its Business & Industry (B&I) segment, ABM's diversified portfolio and geographical spread helped maintain its resilience.
Following these results, ABM raised its outlook for fiscal year 2024 adjusted EPS to a range of $3.48 to $3.55, up from its previous guidance of $3.40 to $3.50. Anticipates maintaining adjusted EBITDA margins around 6.3% for the year and expects free cash flow to approach the higher end of its forecasted range of $240 million to $270 million.
Analysts Adjust Price Targets Amid Q3 Results and Upgraded Outlook
- UBS analyst Joshua Chan maintained a Neutral rating and raised the price target from $51 to $55.
- Truist Securities analyst Jasper Bibb Kept a Hold rating but increased the price target from $49 to $55.
- Baird analyst Andrew Wittmann kept a Neutral stance while raising the price target from $49 to $56.
- Deutsche Bank analyst Fawne Alwy set a new price target of $55.
Which Analyst has the best track record to show on ABM?
Analyst Andrew Wittmann (BAIRD) currently has the highest performing score on ABM with 19/20 (95%) price target fulfillment ratio. His price targets carry an average of $-1.09 (-2.18%) potential downside. ABM Industries stock price reaches these price targets on average within 573 days.
BRP Sees Revenue Plunge 33.7% in Q2 FY 2025 Amid Inventory Cutbacks
BRP reported its second-quarter results for fiscal year 2025, with revenues dropping by 33.7% to $1,841.9 million from $2,778.0 million in Q2 2023. Gross profit for the quarter decreased by 46.0% to $376.5 million, with the gross profit margin falling to 20.4% from 25.1% year-over-year.
Normalized EBITDA dropped 58.0% to $198.5 million, and net income fell by $331.5 million to $7.2 million. Normalized diluted earnings per share (EPS) were $0.61, down from $3.21, and diluted EPS was $0.09, down from $4.26.
In terms of retail performance, BRP's North American Powersports sales declined by 18% from the previous year. BRP experienced mixed results across its markets, with Latin America showing an 18% increase in retail sales, while other regions like North America, EMEA, and Asia Pacific saw declines. Additionally, BRP has reduced its network inventory by 13% so far this year, working towards a target reduction of 15% to 20% by the end of fiscal 2025.
Looking ahead, BRP revised guidance for the remainder of the year anticipates revenues between $7.8 billion and $8 billion, with normalized EBITDA expected to be between $890 million and $940 million.
Analysts Downgrade and Adjust Price Targets Amid Q2 Results
- CIBC analyst Mark Petrie downgraded from Outperformer to Neutral and the price target from $100 to $92.
- Citigroup analyst James Hardiman maintained a Buy rating but lowered the price target from $80 to $75.
- RBC Capital analyst Sabahat Khan kept an Outperform rating and decreased the price target from $108 to $99.
- BMO Capital analyst Tristan Thomas-Martin lowered the price target to $100 from $115.
- Baird analyst Craig Kennison reduced the price target to $68.
- Desjardins analyst Benoit Poirier downgraded from Buy to Hold and set a price target of $94.
- Scotiabank analyst Jonathan Goldman downgraded to Sector Perform.
Which Analyst has the best track record to show on DOOO?
Analyst James Hardiman (CITI) currently has the highest performing score on DOOO with 2/4 (50%) price target fulfillment ratio. His price targets carry an average of $9.11 (12.85%) potential upside. BRP stock price reaches these price targets on average within 151 days.
Daily stock Analysts Top Price Moves Snapshot
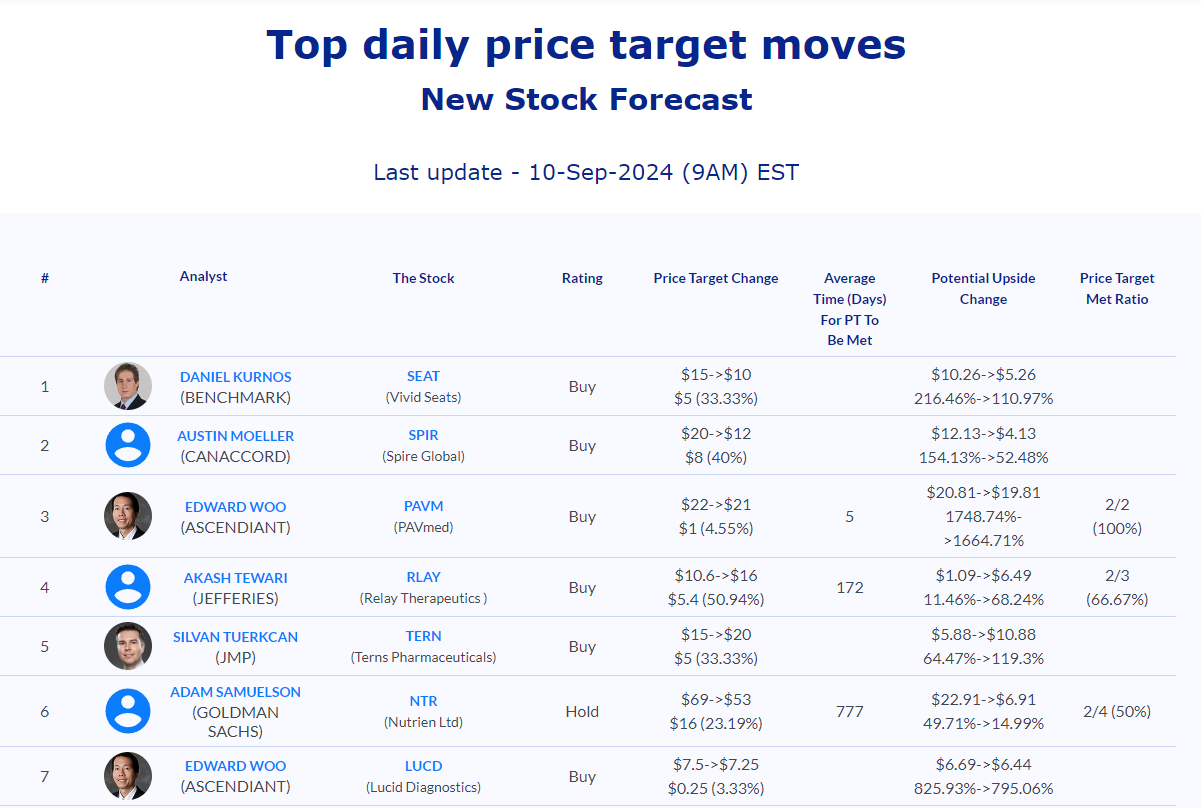
September 11, 2024: Selected stock price target news of the day: September 11th, 2024
By: Matthew Otto
Academy Sports Exceeds Q2 Earnings Expectations Despite Revenue Miss
Academy Sports and Outdoors reported Q2 2024 earnings, posting earnings per share (EPS) of $2.03, just above the analyst estimate of $2.02. Also reported total revenue of $1.55 billion, which came in lower than the consensus estimate of $1.58 billion.
Total sales reached $1.55 billion, down 2.2% compared to the same period last year. Comparable sales were also down by 6.9%, driven primarily by a 7.4% drop in store traffic.
Academy Sports and Outdoors faced several challenges, including economic pressures on its core customer base of young families. Additionally, severe weather events negatively affected operations, with the company estimating these disruptions cost them approximately $16 million in sales.
On the other hand, footwear and outdoor divisions both reported 1% sales growth. Academy Sports’ online sales also grew, accounting for 9.7% of total sales.
Academy Sports and Outdoors revised its full-year sales forecast to between $5.9 billion and $6.07 billion, down 1% to 4% from the previous year.
Analysts Boost Price Targets and Reaffirm Ratings
- Wedbush analyst Seth Basham reiterated an Outperform rating and a $65 price target.
- Truist Securities analyst Joseph Civello kept a Buy rating and raised the price target from $60 to $63.
- Telsey Advisory Group analyst Joseph Feldman continued with an Outperform rating and a $65 price target.
- Evercore ISI analyst Greg Melich increased the price target to $65.
- Loop Capital analyst Anthony Chukumba reaffirmed a Buy rating and a $77 price target.
- Wells Fargo analyst Will Gaertner raised the price target to $61.
Which Analyst has the best track record to show on ASO?
Analyst Christopher Horvers (JPMORGAN) currently has the highest performing score on ASO with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $4.24 (8.70%) potential upside. Academy Sports and Outdoors stock price reaches these price targets on average within 160 days.
Avid Bioservices Reports Q1 FY2025 Results with Increased Revenue and Record Backlog
Avid Bioservices reported its financial results for the first quarter of fiscal 2025, with revenues reaching $40.2 million. This reflects a 6% increase from $37.7 million in the prior year. Gross profit increased to $5.7 million, with a gross margin of 14%, compared to $4.1 million or an 11% margin in the first quarter of fiscal 2024.
However, net loss widened to $5.5 million, or $0.09 per share, from a net loss of $2.1 million, or $0.03 per share, in the same period last year. Selling, general, and administrative expenses increased by 30%, reaching $8.2 million, driven by higher compensation, benefits, and professional fees.
Operationally, Avid reported $66 million in net new orders during the quarter, bringing its backlog to $219 million, a 16% increase from the same quarter in 2023 and a 13% rise from year-end fiscal 2024.
Analysts Boost Ratings and Price Targets Following Q1 FY2025
- RBC Capital analyst Sean Dodge maintained an Outperform rating and raised the price target from $8 to $12.
- Stephens & Co. analyst Jacob Johnson reiterated an Overweight rating and the price target at $12.
- William Blair analyst Max Smock continued with a Market Perform rating.
Which Analyst has the best track record to show on CDMO?
Analyst Sean Dodge (RBC) currently has the highest performing score on CDMO with 8/12 (66.67%) price target fulfillment ratio. His price targets carry an average of $0.3 (3.90%) potential upside. Avid Bioservices stock price reaches these price targets on average within 32 days.
Apple iPhone 16 Launch: Analysts Weigh In on Incremental Upgrades and Future Prospects
Apple's recent iPhone 16 launch event, held on Monday, did not generate the excitement many investors had anticipated. Analysts had hoped for significant advancements in Apple's generative artificial intelligence capabilities, which were expected to drive a major upgrade cycle for the iPhone. However, the event's focus on new accessories, such as a redesigned Apple Watch and AirPods Pro 2 with basic hearing-aid functionalities, overshadowed the iPhone updates.
Oppenheimer analyst Martin Yang noted that the iPhone 16's improvements are relatively incremental compared to the major upgrades seen in Apple's accessories. The most notable change to the iPhone 16 is a new camera control button, while no groundbreaking AI features were introduced.
Yang maintains an Outperform rating for Apple with a $250 price target, suggesting that significant iPhone upgrades may not materialize until next year when Apple Intelligence is more widely available.
Needham analyst Laura Martin also remains optimistic, holding a Buy rating with a $260 price target, but acknowledged that while the iPhone 16 did not introduce major features, Apple’s strategic focus may shift towards more significant advancements later in the year.
Melius Research's Ben Reitzes, who also rates Apple stock as Buy with a $265 price target, believes that the upgrade cycle could accelerate in the coming year with further AI enhancements.
Overall, analysts suggest that while the iPhone 16 did not generate immediate excitement, future developments and broader AI rollouts could positively impact Apple’s stock performance.
Analyst Reflect Cautious Optimism and Mixed Reactions Following iPhone 16 Launch
- JP Morgan analyst Samik Chatterjee maintained an Overweight rating and a price target of $265.
- Oppenheimer analyst Martin Yang continued with an Outperform rating and a price target of $250.
- Piper Sandler analyst Matt Farrell reiterated a Neutral rating and a price target of $225.
- Wedbush analyst Daniel Ives maintained an Outperform rating and raised the price target from $285 to $300.
- BofA Securities analyst Wamsi Mohan kept a Buy rating, along with a price target of $256.
- Needham analyst Laura Martin reiterated a Buy rating and a price target of $260.
Which Analyst has the best track record to show on AAPL?
Analyst Krish Sankar (TD COWEN) currently has the highest performing score on AAPL with 30/31 (96.77%) price target fulfillment ratio. His price targets carry an average of $31.76 (14.55%) potential upside. Apple stock price reaches these price targets on average within 183 days.
Daily stock Analysts Top Price Moves Snapshot
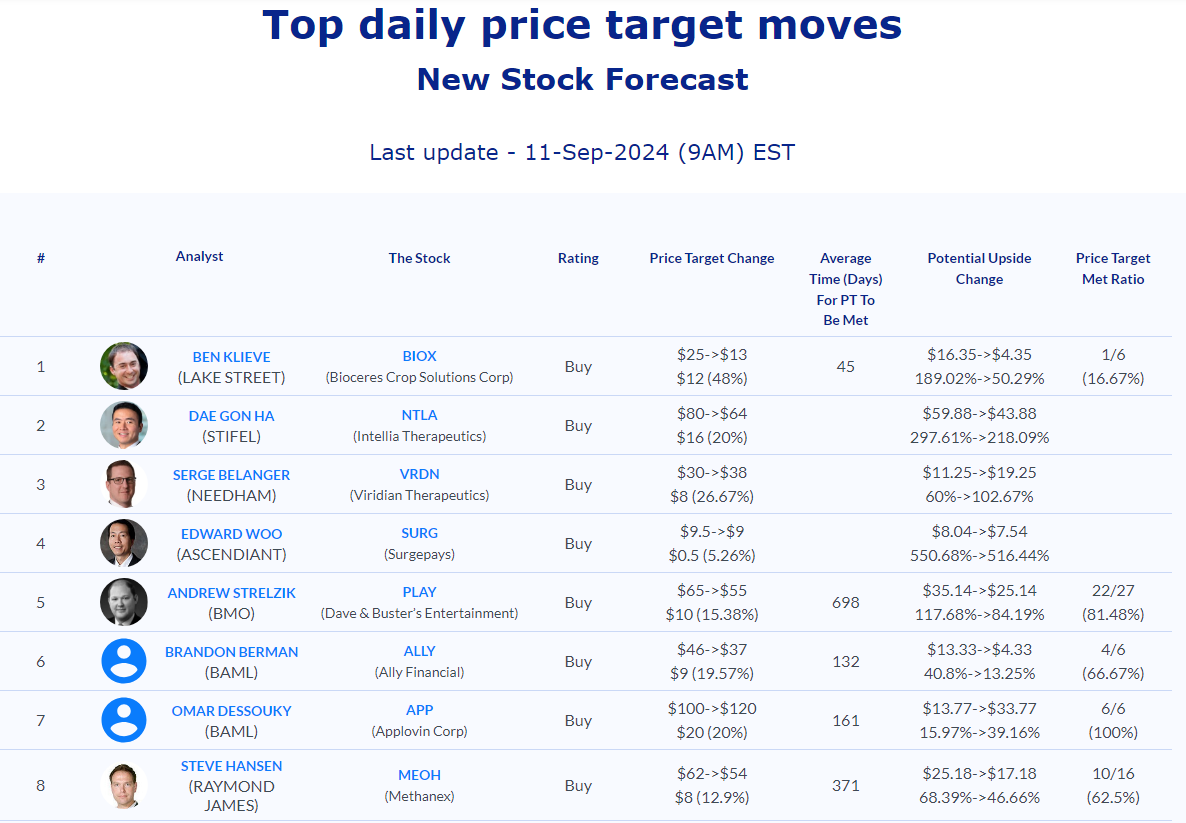
September 12, 2024: Selected stock price target news of the day: September 12th, 2024
By: Matthew Otto
Bioceres Sees Q4 Revenue Growth, But Full-Year Profits Decline Amid Challenging Conditions
Bioceres Crop Solutions reported an 18% year-over-year revenue growth in Q4 FY24, with revenues reaching $124.0 million. Total revenues for FY24 amounted to $464.8 million, an 11% increase compared to the previous year.
Bioceres' GAAP net income for FY24 was $6.2 million, down from $20.2 million in FY23, while adjusted EBITDA remained at $81.4 million. The Seed and Integrated Products segment saw growth, with a 70% annual increase in revenues, reaching $96.4 million. However, the Crop Nutrition segment experienced a 10% decline due to reduced fertilizer sales.
In Q4 FY24, Bioceres' gross profit rose to $47.4 million, an 18% increase compared to Q4 FY23, with gross margins at 38.3%. Adjusted EBITDA nearly doubled for the quarter, reaching $19.9 million. Bioceres received regulatory approval for HB4 wheat cultivation in the U.S., further expanding its market reach.
Analysts Lower Price Targets Amidst Market Uncertainty
- Canaccord Genuity analyst Austin Moeller maintained a Buy rating while lowering the price target from $17 to $12.5.
- Roth MKM analyst Scott Fortune kept a Buy rating, yet reduced the price target from $15 to $13.
- Lake Street analyst Ben Klieve reaffirmed a Buy rating but cut the price target sharply from $25 to $13.
- Oppenheimer analyst Kristen Owen held an Outperform rating, though trimmed the price target from $17 to $16.
Which Analyst has the best track record to show on BIOX?
Analyst Ben Klieve (LAKE STREET) currently has the highest performing score on BIOX with 1/6 (16.67%) price target fulfillment ratio. His price targets carry an average of $14 (127.27%) potential upside. Bioceres Crop Solutions stock price reaches these price targets on average within 45 days.
Ally Financial Faces Severe Credit Pressures as Inflation and Interest Rates Drive Loan Delinquencies
Ally Financial is facing increasing credit challenges, as borrowers struggle with high inflation and rising interest rates. According to Chief Financial Officer Jenn LaClair, Ally Financial has seen a noticeable increase in loan delinquencies this quarter, particularly in its auto lending portfolio, which accounts for a significant portion of its business.
In Q2, Ally's charge-off rate reached 1.9%, up from 1.4% in the previous quarter. Loan loss provisions also surged to $540 million, compared to $318 million in Q1. These factors highlight the growing financial strain on consumers, exacerbated by inflationary pressures.
Goldman Sachs analyst Ryan Nash maintained a Buy rating on Ally Financial, setting a price target of $42.00 despite recent volatility. Nash noted that while Ally’s recent conference update, which included higher credit loss expectations and a lower near-term net interest margin trajectory, contributed to a dramatic drop in share prices, the long-term outlook remains positive. He acknowledged that while estimates for 2025 are being adjusted downward, shares might face short-term fluctuations similar to past instances.
Analyst Ratings Cut as Credit Issues and Stock Decline Persist
- RBC Capital analyst Jon Arfstrom maintains an Outperform rating, though he has reduced the price target from $49 to $40.
- Morgan Stanley analyst Betsy Graseck continues to hold an Overweight rating, but lowers the price target from $49 to $45.
- B of A Securities analyst Brandon Berman maintains a Buy rating while adjusting the price target from $46 to $37.
- TD Cowen analyst Moshe Orenbuch has reiterated a Hold rating with a price target of $45.00, noting that the company faces ongoing challenges.
- Goldman Sachs analyst Ryan Nash reiterates a Buy rating, setting a price target of $42.00, despite recent volatility.
Which Analyst has the best track record to show on ALLY?
Analyst Richard Shane (JPMORGAN) currently has the highest performing score on ALLY with 17/21 (80.95%) price target fulfillment ratio. His price targets carry an average of $4.5 (11.11%) potential upside. Ally Financial stock price reaches these price targets on average within 219 days.
Dave & Buster's Q2 2024 Results: EPS Beats Estimates, Revenue Falls Short
Dave & Buster's Entertainment reported its financial results for the second quarter of 2024, achieving a revenue of $557.1 million. This is below the consensus estimate of $567.33 million. However, exceeded earnings expectations with an EPS of $1.12, surpassing the analyst estimate of $0.91 by $0.21.
Adjusted EBITDA for the quarter was $152 million, reflecting an 8% year-over-year increase, with a margin expansion of 130 basis points to 27.2%. Net income for the quarter was $40 million, or $0.99 per diluted share. Generated $102 million in operating cash flow and ended the quarter with a net cash balance of $13 million, alongside $481 million available on its revolving credit facility, resulting in total liquidity of $494 million.
Dave & Buster's remodeled 18 stores and plans to complete an additional 26 by the end of fiscal 2024. Same-store sales decreased by 6.3% on a calendar basis. During the quarter, Dave & Buster's opened two new locations and anticipates opening a total of 15 stores in fiscal 2024. Capital expenditures for the quarter reached $112 million. Additionally, Dave & Buster's is poised to open four to five international locations in the next 12 months.
Analyst Ratings Adjusted Following Q2 2024 Results
- Loop Capital analyst Alton Stump maintained a Buy rating but lowered the price target from $63 to $59.
- BMO Capital analyst Andrew Strelzik kept an Outperform rating, though reduced the price target from $65 to $55.
- Truist Securities analyst Jake Bartlett reiterated a Buy rating with a $59 price target.
- William Blair analyst Sharon Zackfia upheld an Outperform rating.
Which Analyst has the best track record to show on PLAY?
Analyst Jake Bartlett (TRUIST) currently has the highest performing score on PLAY with 36/47 (76.6%) price target fulfillment ratio. His price targets carry an average of $26.21 (79.93%) potential upside. Dave & Buster's Entertainment stock price reaches these price targets on average within 341 days.
Daily stock Analysts Top Price Moves Snapshot

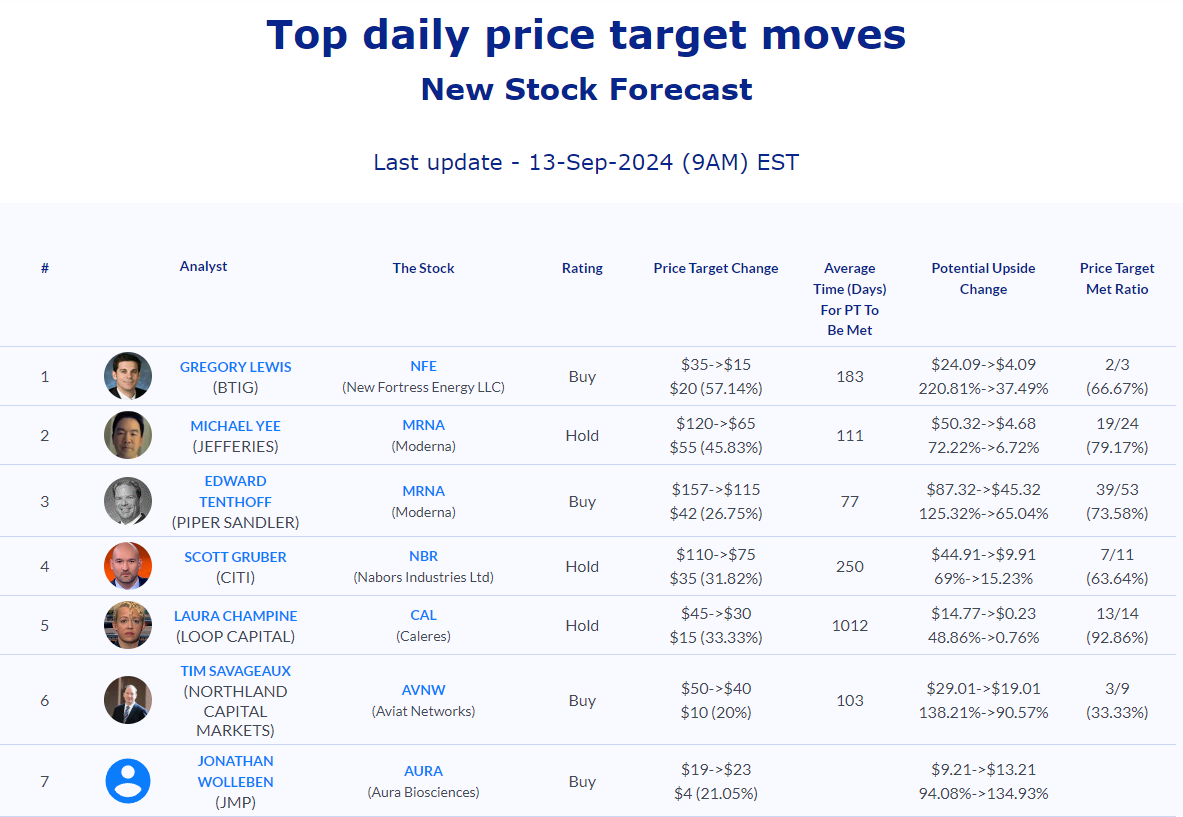
September 13, 2024: Selected stock price target news of the day: September 13th, 2024
By: Matthew Otto
Petco Reports In-Line Q2 2024 Earnings, Sets Focus on Profitability and Growth for Q3 2025
Petco Health and Wellness reported its second-quarter 2024 earnings, delivering an earnings per share (EPS) of ($0.02), which was in line with analyst estimates. Revenue for the quarter stood at $1.52 billion, meeting the consensus estimate of $1.52 billion.
Despite a slight year-over-year decline in net revenue by 50 basis points, comparable sales increased by 30 basis points. Consumables saw a modest 1% growth, though discretionary categories faced a 5% decline. Services, including vet hospitals and grooming, grew by 10%, contributing to a 3% increase in the overall Services and Other segment.
Gross profit came in at $581 million, down 210 basis points, with a gross margin of 38.1%, lower by 60 basis points year-over-year. Adjusted EBITDA for the quarter was $83.5 million, with an adjusted EBITDA margin of 5.5%. Adjusted earnings per share was negative $0.02, compared to $0.06 in the previous year.
Petco provided guidance for the upcoming third quarter of 2025, forecasting an EPS of ($0.03) to ($0.04), compared to the consensus estimate of ($0.03). Q3 revenue expected to be around $1.5 billion, below the consensus of $1.51 billion. Petco's liquidity remains robust at $655 million, with free cash flow of $42 million for the quarter.
Analysts Adjust Price Targets Following Q2 2024 Earnings
- Citigroup analyst Steven Zaccone maintained a Neutral rating and raised the price target from $4 to $4.50.
- Goldman Sachs analyst Kate McShane maintained a Buy rating but lowered the price target from $5 to $4.
- RBC Capital analyst Steven Shemesh maintained an Outperform rating and raised the price target from $3 to $3.50.
- Wells Fargo analyst Zachary Fadem reiterated an Equal-Weight rating and increased the price target from $2.75 to $3.
- Wedbush analyst Seth Basham reiterated an Outperform rating and a $5 price target.
Which Analyst has the best track record to show on WOOF?
Analyst Seth Basham (WEDBUSH) currently has the highest performing score on WOOF with 4/12 (33.33%) price target fulfillment ratio. His price targets carry an average of $1.35 (36.99%) potential upside. Petco Health and Wellness stock price reaches these price targets on average within 8 days.
Adobe Reports Strong Q3 Results but Signals Potential Weakness in Q4 Guidance
Adobe reported its third-quarter financial results, achieving revenue of $5.41 billion, exceeding the $5.37 billion forecast. Adjusted earnings per share (EPS) of $4.65, surpassing the $4.53 estimate. This performance reflected an 11% increase in year-over-year revenue, driven primarily by an 11% growth in Adobe’s Digital Media segment, which includes Creative Cloud subscriptions. Adobe reported net income of $1.68 billion, or $3.76 per diluted share, up from $1.40 billion, or $3.05 per share, in the same period last year.
Looking forward, Adobe anticipates fourth-quarter revenue between $5.50 billion and $5.55 billion, below the $5.61 billion forecast, and EPS between $4.63 and $4.68, compared to the $4.67 estimate. Adobe also noted that its subscription revenue for the quarter was $5.18 billion, an 11% increase year-over-year. Adobe’s guidance for net new Digital Media subscriptions was expected to be flat with the $550 million achieved in the August quarter, falling short of the $565 million anticipated by analysts.
Analysts Adjust Targets After Q3 Report and Weaker Q4 Guidance
- Bernstein analyst Mark Moerdler maintained an Outperform rating but reduced the price target from $660 to $644.
- Piper Sandler analyst Brent Bracelin kept an Overweight rating and the price target at $635.
- Citigroup analyst Tyler Radke upheld a Neutral rating and increased the price target from $550 to $621.
- UBS analyst Karl Keirstead lowered the price target to $550.
- Oppenheimer analyst Brian Schwartz reiterated an Outperform rating with a $625 price target.
- HSBC analyst Stephen Bersey maintained a Hold rating and raised the price target from $519 to $536.
Which Analyst has the best track record to show on ADBE?
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on ADBE with 3/4 (75%) price target fulfillment ratio. His price targets carry an average of $54.69 (10.41%) potential upside. Adobe Systems stock price reaches these price targets on average within 6 days.
Kroger Exceeds Q2 EPS Estimates, Raises Sales Forecast Amid Competitive Landscape and Merger Review
Kroger reported its second-quarter results, with earnings per share (EPS) of $0.93, exceeding the analyst estimate of $0.91. Revenue for the quarter totaled $33.91 billion, below the consensus estimate of $34.08 billion.
Kroger's identical sales, excluding fuel, grew by 1.2% in the second quarter, supported by a rise in customer metrics such as total and loyal households, and increased visits. Digital sales surged, with delivery solutions up by 17% and pickup up by 10%. Despite facing inflationary pressures and evolving consumer behaviors, Kroger maintained a positive FIFO gross margin rate of 22.6% and saw a 10% increase in their quarterly dividend.
Kroger’s initiatives, including promotions and a commitment to lower prices by $1 billion post-merger with Albertsons, aim to maintain its edge. The merger remains under antitrust review by the Federal Trade Commission (FTC), which has raised concerns about potential price increases and reduced bargaining power for workers.
For fiscal 2024, Kroger now expects identical sales, excluding fuel, to grow between 0.75% and 1.75%, up from the previous range of 0.25% to 1.75%. Guidance for fiscal 2025 EPS is projected to be between $4.30 and $4.50, compared to the consensus estimate of $4.43.
Analysts Boost Price Targets Following Q2 Report and Positive Outlook
- Evercore ISI Group analyst Michael Montani maintained an Outperform rating and raised the price target from $62 to $63.
- Morgan Stanley analyst Simeon Gutman retained an Equal-Weight rating with an increased price target from $57 to $58.
- Telsey Advisory Group analyst Joseph Feldman continued with an Outperform rating and a price target of $62.
- JPMorgan analyst Ken Goldman raised the price target to $59.
- CFRA upgrades Kroger from Hold to Buy.
- BMO Capital analyst Kelly Bania reiterated an Outperform rating and set the price target at $60.
Which Analyst has the best track record to show on KR?
Analyst Michael Montani (EVERCORE) currently has the highest performing score on KR with 8/10 (80%) price target fulfillment ratio. His price targets carry an average of $9.72 (19.33%) potential upside. Kroger Company stock price reaches these price targets on average within 255 days.
Daily stock Analysts Top Price Moves Snapshot
September 16, 2024: Selected stock price target news of the day: September 16th, 2024
By: Matthew Otto
RH Reports Q2 Earnings Amid Rising Demand, Lowers Full-Year Revenue Forecast
RH posted its second-quarter 2024 earnings, reporting earnings per share (EPS) of $1.69, surpassing the analyst estimate of $1.62 by $0.07. Revenues came in at $829.66 million, slightly above the consensus estimate of $827.61 million. Demand growth reached 7% in the second quarter, with a further acceleration in the third quarter as July and August demand increased by 10% and 12%, respectively.
Despite these results, RH lowered its full-year revenue growth forecast to 5% to 7%, down from the previous estimate of 8% to 10%. RH now expects to end the year with a backlog of $80 million to $100 million, which will impact adjusted operating and EBITDA margins by approximately 100 basis points. Additionally, international expansion costs are projected to create a 230 basis point drag for 2024. For the third quarter, RH forecasts demand growth between 12% and 14%, revenue growth of 7% to 9%, and an adjusted operating margin of 15% to 16%.
Analysts Raise Price Targets Following Q2 Earnings
- Loop Capital analyst Anthony Chukumba maintained a Hold rating and raised the price target from $230 to $320.
- Stifel analyst W. Andrew Carter maintained a Buy rating on RH while increasing the price target from $315 to $375.
- Citigroup analyst Steven Zaccone kept a Buy rating but lifted the price target from $340 to $355.
- Telsey Advisory Group analyst Joseph Feldman maintained a Market Perform rating and a $290 price target.
- BofA Securities analyst Curtis Nagle retained a Buy rating as well as raised the price target from $310 to $359.
- TD Cowen analyst Max Rakhlenko continued with a Buy rating and increased the price target from $325 to $350.
- Wells Fargo analyst Zachary Fadem upheld an Overweight rating and raised the price target from $325 to $350.
Which Analyst has the best track record to show on RH?
Analyst Zachary Fadem (WELLS FARGO) currently has the highest performing score on RH with 20/28 (71.43%) price target fulfillment ratio. His price targets carry an average of $28.13 (8.74%) potential upside. RH stock price reaches these price targets on average within 87 days.
Signet Jewelers Beats Q2 EPS Estimates, Misses on Revenue, and Reaffirms Strong FY2025 Outlook
Signet Jewelers reported its second-quarter fiscal 2025 earnings, with an EPS of $1.25, $0.07 higher than the estimate of $1.18. However, revenue came in below forecasts at $1.5 billion, compared to the consensus estimate of $1.51 billion.
Despite the revenue miss, Signet highlighted growth in same-store sales and an increase in average transaction value (ATV), particularly in lab-created diamond fashion jewelry, which grew by more than 25%. New merchandise sales also saw a 50% increase, accounting for 25% of total sales in core banners such as Jared, Zales, and Kay.
For the third quarter of fiscal 2025, Signet projects revenue between $1.34 billion and $1.38 billion, in line with the consensus estimate of $1.35 billion. Additionally, reaffirmed its fiscal year 2025 guidance, expecting EPS between $9.90 and $11.52, compared to the analyst consensus of $10.28.
Full-year revenue is forecasted to range from $6.66 billion to $7.02 billion, versus the consensus estimate of $6.77 billion. Signet also reported a gross margin of $566 million, or 38% of sales, and continued to reduce inventory by more than 5%, closing the quarter with a balance just below $2 billion.
Analysts Revise Price Targets After Q2 Performance
- Telsey Advisory Group analyst Dana Telsey maintained a Market Perform rating and the price target at $87.
- UBS analyst Mauricio Serna continued to rate a Buy, and has raised the price target from $132 to $136.
- BofA Securities analyst Lorraine Hutchinson held a Neutral rating, but lowered the price target from $108 to $100.
Which Analyst has the best track record to show on SIG?
Analyst Dana Telsey (TELSEY ADVISORY) currently has the highest performing score on SIG with 16/24 (66.67%) price target fulfillment ratio. His price targets carry an average of $-4.03 (-4.43%) potential downside. Signet Jewelers stock price reaches these price targets on average within 129 days.
Lovesac Reports Q2 Fiscal 2025 Losses Despite Revenue Growth and Expanding Showroom Network
The Lovesac Company reported its financial results for the second quarter of fiscal 2025. Net sales for the quarter increased by $2.1 million, or 1.3%, to $156.6 million, driven by the addition of 31 new showrooms despite a 5.4% decline in omni-channel comparable net sales.
Gross profit remained at $92.4 million, but gross margin decreased by 80 basis points to 59.0%, attributed to higher promotional discounting and increased outbound transportation costs. Total operating expenses rose by 7.9% to $100.7 million, with increases in SG&A expenses, which climbed by 15.4% to $73.7 million.
The operating loss widened to $8.4 million, compared to $1.0 million in the prior year, and net loss reached $5.9 million, or $(0.38) per share, reflecting an increase from the previous year's net loss of $0.6 million, or $(0.04) per share.
For the first half of fiscal 2025, net sales decreased by $6.5 million, or 2.2%, to $289.2 million, primarily due to a 10.0% drop in omni-channel comparable net sales. Gross profit increased slightly by 0.9% to $164.4 million, with a 170 basis point improvement in gross margin to 56.8%. Operating expenses surged by 18.0% to $190.6 million, mainly due to higher payroll and professional fees.
The operating loss for the first half of the year was $26.2 million, worsening from $6.7 million in the previous period. Net loss for the first half amounted to $18.8 million, or $(1.21) per diluted share, compared to $4.8 million, or $(0.31) per diluted share, in the prior year.
Lovesac ended the period with a cash balance of $72.1 million and no outstanding balance on its line of credit. For fiscal 2025, Lovesac expects net sales between $700 million and $735 million and adjusted EBITDA ranging from $52 million to $59 million.
Analysts Remain Bullish with Target Price Increases
- Canaccord Genuity analyst Maria Ripps maintained a Buy rating and the price target at $36.
- Craig-Hallum analyst Alex Fuhrman reiterated a Buy rating and increased the price target from $30 to $35.
- Roth MKM analyst Matt Koranda reiterated a Buy rating and raised the price target from $30 to $31.
Which Analyst has the best track record to show on LOVE?
Analyst Alex Fuhrman (CRAIG HALLUM) currently has the highest performing score on LOVE with 8/12 (66.67%) price target fulfillment ratio. His price targets carry an average of $8.75 (33.33%) potential upside. The Lovesac Company stock price reaches these price targets on average within 153 days.
Daily stock Analysts Top Price Moves Snapshot

September 17, 2024: Selected stock price target news of the day: September 17th, 2024
By: Matthew Otto
Tesla Vehicle Deliveries Decline 7% in First Half of 2024, Analysts Anticipate Q3 Recovery
Tesla delivered approximately 831,000 vehicles in the first half of 2024, a 7% decrease from the 894,000 vehicles delivered during the same period in 2023. In Q2 2024 alone, Tesla delivered around 410,000 vehicles, falling short of expectations, which had been set closer to 420,000.
Despite these setbacks, analysts expect an improvement in the third quarter, with projected deliveries of 460,000 vehicles, marking a 6% increase compared to the 434,000 delivered in Q3 2023.
Tesla's production numbers for 2024 also reflect this trend, with approximately 875,000 vehicles produced in the first half, down 5% year over year from the 921,000 produced in the first half of 2023. Tesla’s Model Y continues to be the company's best-selling vehicle, accounting for over 60% of total deliveries.
Despite the recent dip, analysts remain optimistic about Tesla’s ability to meet its annual delivery target of 1.8 million vehicles.
Analysts Offer Diverging Ratings Amid Mixed Delivery Outlook
- Cantor Fitzgerald analyst Andres Sheppard reiterated a Neutral rating and a $245 price target.
- Canaccord Genuity analyst George Gianarikas maintained a Buy rating and the price target at $254.
- Guggenheim analyst Ronald Jewsikow maintained a Sell rating; however, raised the price target from $134 to $153.
Which Analyst has the best track record to show on TSLA?
Analyst Andres Sheppard (CANTOR FITZGERALD) currently has the highest performing score on TSLA with 9/15 (60%) price target fulfillment ratio. His price targets carry an average of $28.73 (13.28%) potential upside. Tesla stock price reaches these price targets on average within 15 days.
Nuvalent Reports Promising Trial Results for Lung Cancer Drugs, Analysts Highlight Potential
Nuvalent presented updates on two of its experimental lung cancer treatments, zidesamtinib and NVL-655, at the European Society for Medical Oncology Congress in Barcelona. 44% of patients with ROS1-positive non-small cell lung cancer (NSCLC) responded to zidesamtinib in an ongoing trial. Similarly, 38% of patients with ALK-positive NSCLC responded to NVL-655 in a separate trial. Both studies involve patients whose cancers had previously resisted other treatments, and Nuvalent anticipates concluding both trials by next year.
Analysts responded positively to these developments. Leerink Partners’ Andrew Berens noted that the data support a best-in-class profile for NVL-655, which targets ALK gene mutations commonly found in NSCLC. Berens also pointed out that the expedited trial timeline could accelerate the drug's movement into earlier treatment stages. Piper Sandler analyst Christopher Raymond echoed this view, projecting significant market potential for NVL-655 and zidesamtinib. Raymond added that Nuvalent is well on its way to unlocking the multibillion-dollar potential of NVL-655, with zidesamtinib expected to reach several hundred million dollars in value.
Analyst Upgrades and Price Target Revisions Reflect Positive Trial Results
- Guggenheim analyst Kelsey Goodwin maintains a Buy rating on Nuvalent and raises the price target from $99 to $105.
- Wedbush analyst David Nierengarten keeps an Outperform rating on Nuvalent and increases the price target from $99 to $115.
- BMO Capital analyst Etzer Darout holds an Outperform rating for Nuvalent, with the price target rising from $102 to $132.
- Stifel analyst Bradley Canino retains a Buy rating on Nuvalent and lifts the price target from $115 to $135.
Which Analyst has the best track record to show on NUVL?
Analyst Etzer Darout (BMO) currently has the highest performing score on NUVL with 4/5 (80%) price target fulfillment ratio. His price targets carry an average of $16.64 (19.49%) potential upside. Nuvalent stock price reaches these price targets on average within 149 days.
Merit Medical Systems Announces Acquisition of Cook Medical’s Lead Management Portfolio
Merit Medical Systems has entered into a definitive agreement to acquire Cook Medical's lead management product portfolio for a cash consideration of approximately $210 million. The transaction is scheduled to close in the fourth quarter of 2024, subject to customary closing conditions, including regulatory approvals under the Hart-Scott-Rodino Antitrust Improvements Act.
Cook Medical’s lead management business, with a 34-year history, includes a comprehensive range of medical devices and accessories used in procedures for replacing or removing pacemaker and implantable cardioverter-defibrillator (ICD) leads. The acquisition is projected to generate approximately $40 million in additional annual revenue starting from fiscal year 2025. Following the acquisition, Merit expects its combined annualized revenue from electrophysiology and CRM to exceed $100 million.
Analysts Adjust Ratings and Price Targets Following Announcement
- Wells Fargo analyst Larry Biegelsen maintained an Equal-Weight rating, while raising the price target from $85 to $103.
- BofA Securities analyst Craig Bijou continued with a Neutral rating, yet increased the price target from $92 to $103.
- Needham analyst Mike Matson reiterated a Buy rating and the price target at $105.
Which Analyst has the best track record to show on MMSI?
Analyst Mike Matson (NEEDHAM) currently has the highest performing score on MMSI with 21/22 (95.45%) price target fulfillment ratio. His price targets carry an average of $9.19 (9.59%) potential upside. Merit Medical Systems stock price reaches these price targets on average within 273 days.
Daily stock Analysts Top Price Moves Snapshot
September 18, 2024: Selected stock price target news of the day: September 18th, 2024
By: Matthew Otto
Micron Faces Price Target Cuts Amid Supply Concerns and Market Pressures
Micron Technology faced pressure following a price target reduction by Morgan Stanley analyst, Joseph Moore, who cited ongoing uncertainty surrounding the chip maker's near-term prospects.
Moore also highlighted concerns regarding potential declines in Micron’s average selling prices for its memory chips in the coming quarters, noting that unless this trend reverses, the stock may continue to underperform. Moore lowered their price target from $140 to $100 while maintaining an Equal Weight rating.
BNP Paribas analyst, Karl Ackerman, also downgraded Micron earlier this month, lowering the price target to $67 from $140, citing an oversupply of high-bandwidth memory (HBM) chips.
In addition to the lowered price target, Micron’s has been affected by broader market conditions. This includes a shift away from large-cap tech toward smaller-cap companies and concerns over potential new U.S. export restrictions on chipmaking equipment to China.
Analyst Target Cuts Amid Market and Supply Concerns
- UBS analyst Timothy Arcuri maintained a Buy rating but lowered the price target from $153 to $135.
- Citigroup analyst Christopher Danely maintained a Buy rating, yet lowered the price target from $175 to $150.
- Morgan Stanley analyst Joseph Moore kept an Equal-Weight rating and reduced the price target from $140 to $100.
- Exane BNP Paribas analyst Karl Ackerman downgraded from Outperform to Underperform and the price target from $140 to $67.
- Raymond James analyst Srini Pajjuri continued to rate as Outperform though lowered the price target from $160 to $125.
Which Analyst has the best track record to show on MU?
Analyst Brian Chin (STIFEL) currently has the highest performing score on MU with 7/10 (70%) price target fulfillment ratio. His price targets carry an average of $11.55 (7.53%) potential upside. Micron Technology stock price reaches these price targets on average within 30 days.
Capricor Secures $35 Million in Funding and Expands European Partnership with Nippon Shinyaku
Capricor Therapeutics has entered into a binding term sheet with Nippon Shinyaku Co., Ltd. for the commercialization and distribution of its lead asset, deramiocel, in Europe. Under the agreement, Nippon Shinyaku will invest $15 million in Capricor through the purchase of 2,798,507 shares of common stock at a price of $5.36 per share. This is representing a 20% premium to the 60-day volume-weighted average price (VWAP).
Capricor will receive a $20 million upfront payment, subject to the execution of a definitive agreement expected in Q4 2024. The total potential value of the partnership could reach $715 million in development and sales-based milestone payments, with Capricor also receiving a double-digit percentage of product revenue from future sales.The combined total of potential payments from all existing distribution agreements, including this one, now stands at approximately $1.5 billion.
Deramiocel, currently under development for treating Duchenne muscular dystrophy (DMD), is advancing through Phase 3 clinical trials, with Capricor preparing for discussions with the European Medicines Agency (EMA) regarding potential approval in Europe. The funds from Nippon Shinyaku will support the company’s commercial launch preparations, including manufacturing scale-up and product development for Europe, as well as general corporate purposes.
Analyst Rating Boosts Following European Expansion Deal
- Oppenheimer analyst Leland Gershell maintained an Outperform rating and raised the price target from $14 to $15.
- Maxim Group analyst Jason McCarthy reiterated a Buy rating and a $12 price target.
- HC Wainwright & Co. analyst Joseph Pantginis reaffirmed a Buy rating and the price target at $40.
Which Analyst has the best track record to show on CAPR?
Analyst Joseph Pantginis (HC WAINWRIGHT) currently has the highest performing score on CAPR with 1/8 (12.5%) price target fulfillment ratio. His price targets carry an average of $35.28 (747.46%) potential upside. Capricor Therapeutics stock price reaches these price targets on average within 787 days.
Instil Bio and ImmuneOnco Announce Global Development Plans for SYN-2510/IMM2510 in NSCLC and TNBC
Instil Bio and ImmuneOnco Biopharmaceuticals have outlined their global registrational strategy for the PD-L1xVEGF bispecific antibody SYN-2510/IMM2510, targeting first-line non-small cell lung cancer (NSCLC) and triple-negative breast cancer (TNBC).
In China, ImmuneOnco plans to initiate a Phase 1b/2 clinical trial of SYN-2510/IMM2510 in combination with chemotherapy for first-line NSCLC by late 2024. This trial will focus on patients with both non-squamous and squamous subtypes of NSCLC. Additionally, a Phase 1b/2 study in first-line TNBC is anticipated to start in early 2025.
In the United States, Instil Bio aims to submit an Investigational New Drug (IND) application for SYN-2510 by the end of 2024. Following this, a Phase 2 trial of SYN-2510 monotherapy in second-line NSCLC is planned. Should preliminary results from these studies be positive, the companies may proceed with joint global randomized Phase 3 trials for both NSCLC and TNBC.
SYN-2510/IMM2510, a PD-L1xVEGF bispecific antibody, is designed to target multiple VEGF receptor ligands and employ enhanced antibody-dependent cellular cytotoxicity (ADCC) for tumor cell targeting. The clinical development of SYN-2510/IMM2510 is set to address unmet needs in the treatment of NSCLC and TNBC, with regulatory outcomes contingent on trial results.
Analysts Reaffirm Ratings Amid Global Development Strategy
- HC Wainwright & Co. analyst Mitchell Kapoor reaffirmed a Buy rating and a price target of $120.
- Baird analyst Jack Allen maintained an Outperform rating and a price target of $180.
Which Analyst has the best track record to show on TIL?
Analyst Mitchell Kapoor (HC WAINWRIGHT) currently has the highest performing score on TIL with 5/8 (62.5%) price target fulfillment ratio. His price targets carry an average of $-6.46 (-13.90%) potential downside. Instil Bio stock price reaches these price targets on average within 115 days.
Daily stock Analysts Top Price Moves Snapshot
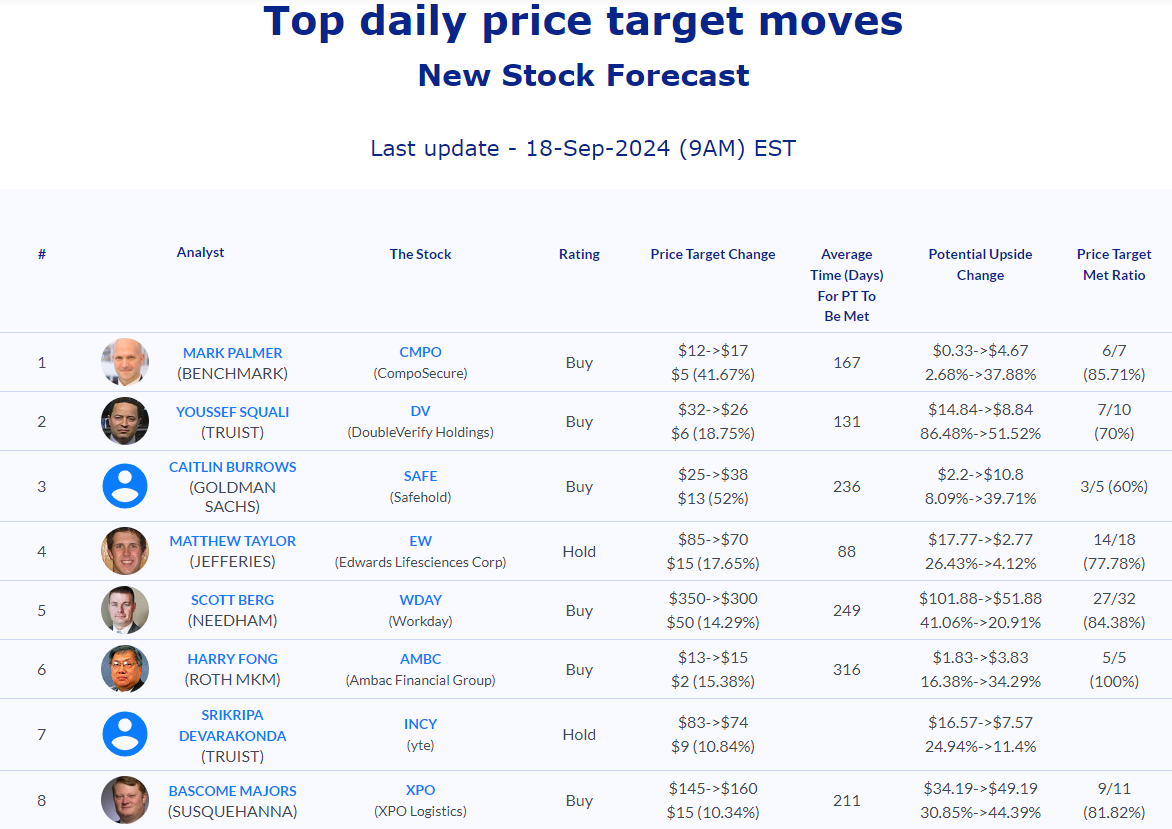
September 19, 2024: Selected stock price target news of the day: September 19th, 2024
By: Matthew Otto
Ferguson plc Reports Q4 Revenue Miss and Full Year EPS Decline
Ferguson plc reported full-year financial results, with net sales totaling $29.6 billion, reflecting a slight decline of 0.3% compared to the previous year. This dip was primarily driven by a 2.4% decline in organic sales, partially offset by a 1.8% increase from acquisitions.
Ferguson achieved a gross margin of 30.5%, an improvement of 10 basis points, and maintained an operating margin of 8.9%. Adjusted operating margin for the year stood at 9.5%, down 30 basis points. Ferguson declared total dividends of $3.16 per share, a 5% increase over the prior year, while repurchasing $634 million worth of shares, leaving a repurchase balance of $900 million.
In the fourth quarter, Ferguson's earnings per share (EPS) of $2.98 exceeded analyst expectations of $2.89 by $0.09. Reported revenue of $7.9 billion, slightly below the consensus estimate of $8.06 billion. Despite a 2% deflation in certain commodity categories, quarterly sales rose by 1.4%.
Operating margin improved to 10.2%, up 20 basis points, while adjusted EPS increased by 7.6%. Ferguson completed four acquisitions during the quarter, contributing to a total investment of $260 million in acquisitions throughout the fiscal year, generating $400 million in annualized revenue. For fiscal 2025, Ferguson anticipates growth, projecting low single-digit sales increases and an adjusted operating margin of 9.0% to 9.5%.
Analysts Adjust Price Targets Following Earnings Beat and Revenue Miss
- Wells Fargo analyst Sam Reid maintained an Overweight rating but lowered the price target from $250 to $225.
- Citigroup analyst Anthony Pettinari maintained a Neutral rating and raised the price target from $203 to $221.
- Barclays analyst Matthew Bouley kept an Overweight rating while increasing the price target from $229 to $245.
- UBS analyst John Lovallo maintained a Buy rating and raised the price target from $228 to $236.
- RBC Capital analyst Mike Dahl held an Outperform rating and increased the price target from $211 to $219.
- Baird analyst David Manthey continued with an Outperform rating and raised the price target from $222 to $225.
Which Analyst has the best track record to show on FERG?
Analyst Zachary Fadem (WELLS FARGO) currently has the highest performing score on FERG with 20/28 (71.43%) price target fulfillment ratio. His price targets carry an average of $28.13 (8.74%) potential upside. Ferguson Plc stock price reaches these price targets on average within 87 days.
Electronic Arts Unveils Long-Term Strategy at First Investor Day in Eight Years
Electronic Arts conducted its first investor day in eight years, where it outlined its long-term strategy and vision. Key highlights from the presentation included plans for The Sims franchise and Battlefield series.
Electronic Arts announced intentions to double annual bookings for The Sims over the next five years, supported by new projects such as a spinoff for a younger audience, a mobile version, and a movie in collaboration with Amazon MGM Studios. The film's production, led by Margot Robbie’s LuckyChap Entertainment, could drive additional game sales.
For Battlefield, Electronic Arts is preparing a large-scale community test for a new installment set in a modern-day setting, scheduled for early next year. This release will be the first under the leadership of Vince Zampella, known for his work on Call of Duty and Modern Warfare.
TD Cowen analyst Doug Creutz estimates that combined bookings from Electronic Arts’ football titles, Madden NFL and College Football, could exceed $1 billion this fiscal year, compared to $600 million from Madden alone last year. Electronic Arts also anticipates future revenue contributions from upcoming releases in the Star Wars and Marvel franchises.
Analyst Ratings Reflect Diverging Views Amid New Strategic Initiatives
- Roth MKM analyst Eric Handler maintained a Neutral rating and set a price target of $154.
- Baird analyst Colin Sebastian kept an Outperform rating with a price target of $170.
- Morgan Stanley analyst Brian Nowak held an Equal-Weight rating and a price target of $150.
- Deutsche Bank analyst Benjamin Soff retained a Hold rating and set a price target of $160.
- Benchmark analyst Mike Hickey reiterated a Buy rating with a price target of $163.
Which Analyst has the best track record to show on EA?
Analyst Michael Ng (GOLDMAN SACHS) currently has the highest performing score on EA with 4/4 (100%) price target fulfillment ratio. His price targets carry an average of $-0.94 (-0.62%) potential downside. Electronic Arts stock price reaches these price targets on average within 82 days.
AspenTech Projects Double-Digit Growth and Reaffirms Financial Outlook at 2024 Investor Day
Aspen Technology hosted its 2024 Investor Day, outlining its strategic priorities and financial outlook. CEO Antonio Pietri emphasized AspenTech's role in assisting customers with the global energy transition and sustainability goals, highlighting ongoing investments in Industrial AI and product adoption.
AspenTech's multi-year financial outlook projects high-single to double-digit annual contract value (ACV) growth, an ACV margin of 45-47%, and mid-teens free cash flow growth for fiscal 2025.
Financially, AspenTech is positioned to leverage a $15-$16 billion addressable market, focusing on expanding software revenue and improving margins. AspenTech's recent partnership with Emerson is expected to drive new opportunities and strengthen its R&D capabilities.
Analysts Boost Price Targets Highlight Growth Prospects
- Loop Capital analyst Mark Schappel maintained a Buy rating and raised the price target from $204 to $260.
- BofA Securities analyst Andrew Obin maintained a Buy rating and increased the price target from $225 to $260.
- Piper Sandler analyst Clarke Jeffries kept a Neutral rating but raised the price target from $200 to $217.
Which Analyst has the best track record to show on AZPN?
Analyst Weston Twigg (PIPER SANDLER) currently has the highest performing score on AZPN with 4/5 (80%) price target fulfillment ratio. His price targets carry an average of $-7.2 (-3.54%) potential downside. Aspen Technology stock price reaches these price targets on average within 60 days.
Daily stock Analysts Top Price Moves Snapshot
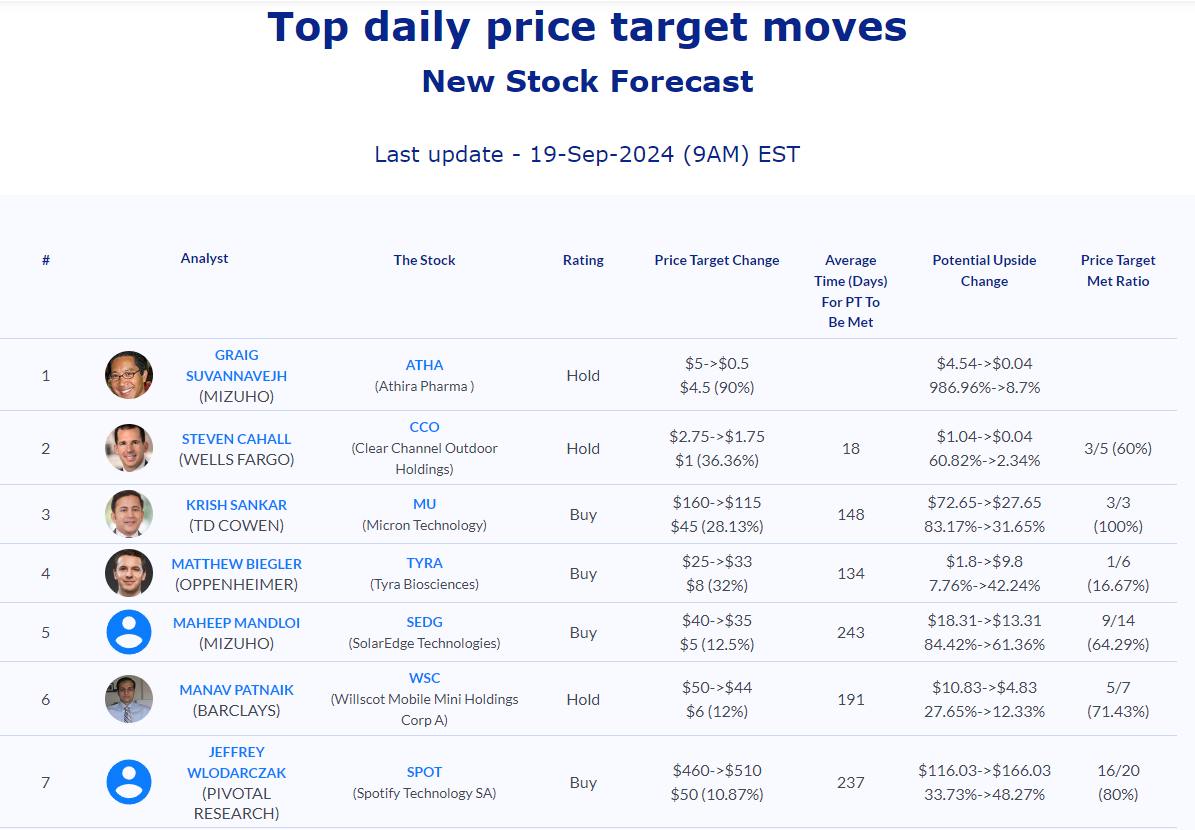
September 20, 2024: Selected stock price target news of the day: September 20th, 2024
By: Matthew Otto
Darden Restaurants Misses Q1 Estimates but Maintains Full-Year Outlook Amid Improving Sales Trends
Darden Restaurants reported its fiscal first-quarter 2025 results, posting adjusted earnings per share (EPS) of $1.75, falling short of the consensus estimate of $1.84. Revenue reached $2.8 billion, slightly under the $2.81 billion projected by analysts but marking a 1% year-over-year increase.
The total sales growth was primarily driven by 42 net new restaurant openings, which helped offset a 1.1% decline in blended same-restaurant sales. Notably, LongHorn Steakhouse posted a 3.7% same-restaurant sales increase, while Olive Garden saw a 2.9% decline.
Despite the softer quarterly performance, Darden reiterated its fiscal 2025 guidance, projecting EPS between $9.40 and $9.60, excluding potential impacts from its pending acquisition of Chuy's.
Analyst Sara Senatore, from Bank of America, noted that while Darden posted a same-store sales decline, the results were in line with trends seen in prior quarters. Barclays analyst, Jeffrey Bernstein, emphasized Darden's improving sales trajectory since July and maintained a positive outlook on the stock. Analysts at Stephens, Jim Salera, however, cautioned that softer results from Olive Garden and the fine dining segment could pressure the broader casual dining market.
Analysts Adjust Ratings and Targets Following Q1 Results and Outlook
- Evercore ISI Group analyst David Palmer upgraded from In-Line to Outperform and the price target from $165 to $205.
- Wedbush analyst Nick Setyan maintained an Outperform rating but raised the price target from $170 to $200.
- Stephens & Co. analyst Jim Salera maintained an Equal-Weight rating while increasing the price target from $159 to $164.
- Bernstein analyst Danilo Gargiulo downgraded from Outperform to Market Perform and the price target from $190 to $180.
- TD Cowen analyst Andrew Charles maintained a Hold rating, yet raised the price target from $150 to $165.
Which Analyst has the best track record to show on DRI?
Analyst John Ivankoe (JPMORGAN) currently has the highest performing score on DRI with 15/16 (93.75%) price target fulfillment ratio. His price targets carry an average of $16.68 (11.25%) potential upside. Darden Restaurants stock price reaches these price targets on average within 273 days.
General Mills Reports Q1 Fiscal 2025 Decline in Sales and Profit, Reaffirms Full-Year Outlook
General Mills reported first-quarter fiscal 2025 results, with net sales declining 1% to $4.85 billion, slightly surpassing analysts' expectations of $4.8 billion. Adjusted earnings per share (EPS) were $1.07, down 2% from the previous year’s $1.09, but $0.02 above Wall Street estimates.
Operating profit dropped 11% to $832 million, while adjusted operating profit in constant currency fell 4% to $865 million. Gross margin decreased by 130 basis points to 34.8%, primarily due to input cost inflation and lower pricing. Despite these declines, General Mills reaffirmed its full-year fiscal 2025 financial guidance.
Segment-wise, North America Retail saw a 2% drop in net sales, and North America Pet sales decreased 1%, though its operating profit rose 7%. The North America Foodservice segment posted flat sales but achieved a 21% rise in operating profit. International segment performance remained flat in terms of sales, but operating profit declined by 58%, primarily due to higher costs.
Looking ahead, General Mills expects organic net sales to range from flat to 1% growth, with adjusted EPS projected between down 1% and up 1%. Also anticipates free cash flow conversion of at least 95% of adjusted after-tax earnings for the fiscal year.
Analyst Ratings Adjustments Reflect Mixed Outlook Following Q1 Results
- Citigroup analyst Thomas Palmer maintained a Neutral rating and lowered the price target from $76 to $75.
- Stifel analyst Matthew Smith held a Buy rating, while raising the price target from $70 to $82.
- RBC Capital analyst Nik Modi reiterated a Sector Perform rating and the price target steady at $70.
- Piper Sandler analyst Michael Lavery maintained an Overweight rating and raised the price target from $74 to $84.
- BofA Securities analyst Bryan Spillane retained a Neutral rating but increased the price target from $75 to $78.
Which Analyst has the best track record to show on GIS?
Analyst Alexia Howard (BERNSTEIN) currently has the highest performing score on GIS with 5/5 (100%) price target fulfillment ratio. Her price targets carry an average of $0.17 (0.24%) potential upside. General Mills stock price reaches these price targets on average within 77 days.
FedEx Corp. Reports First Quarter Fiscal 2025 Results: Revenue Misses, EPS Falls Amid Rising Costs
FedEx reported its financial results for the first quarter of fiscal 2025, generating revenue of $21.6 billion, which was below the consensus estimate of $21.96 billion. Diluted earnings per share (EPS) were $3.60, missing the analyst estimate of $4.86 and decreasing from $4.23 in the same period of fiscal 2024.
Operating income for the quarter was $1.08 billion, resulting in an operating margin of 5.0%, down from an operating income of $1.49 billion and a margin of 6.8% a year earlier. Business optimization costs impacted earnings by $0.39 per diluted share.
In terms of future guidance, FedEx expects its fiscal 2025 EPS to fall between $20.00 and $21.00, slightly below the consensus forecast of $20.71. Anticipates low single-digit percentage revenue growth for the fiscal year, revising earlier projections of low-to-mid single-digit growth. FedEx is focused on implementing cost reductions through its DRIVE transformation program, targeting permanent savings of $2.2 billion, and has planned capital expenditures of $5.2 billion to enhance network efficiency and modernization.
Analyst Price Targets Adjusted Following Q1 Fiscal 2025 Results
- Raymond James analyst Patrick Tyler Brown maintained an Outperform rating, while lowering the price target from $330 to $310.
- Evercore ISI Group analyst Jonathan Chappell kept an Outperform rating, but reduced the price target from $335 to $318.
- Morgan Stanley analyst Ravi Shanker downgraded from Equal-Weight to Underweight, and the price target from $215 to $200.
- Baird analyst Garrett Holland maintained an Outperform rating and decreased the price target from $340 to $320.
- BofA Securities analyst Ken Hoexter retained a Buy rating, yet lowered the price target from $347 to $345.
Which Analyst has the best track record to show on FDX?
Analyst Ken Hoexter (BAML) currently has the highest performing score on FDX with 26/33 (78.79%) price target fulfillment ratio. His price targets carry an average of $50.81 (17.15%) potential upside. FedEx stock price reaches these price targets on average within 367 days.
Daily stock Analysts Top Price Moves Snapshot

September 23, 2024: Selected stock price target news of the day: September 23rd, 2024
By: Matthew Otto
FactSet Surpasses Q4 EPS and Revenue Expectations, Issues FY2025 Guidance Close to Projections
FactSet reported fourth-quarter fiscal 2024 earnings per share (EPS) of $3.74, surpassing the analyst estimate of $3.62 by $0.12. Quarterly revenue reached $562.2 million, exceeding the consensus estimate of $546.76 million. This represents a 4.9% year-over-year increase in GAAP revenues, driven by growth in the wealth, banking, and institutional asset management sectors.
Organic revenues also rose 5.0% to $562.8 million. FactSet’s GAAP operating margin improved by 110 basis points to 22.7%, while the adjusted operating margin increased 240 basis points to 35.8%. GAAP diluted earnings per share grew 38.1% to $2.32.
For fiscal 2025, FactSet expects EPS in the range of $16.80 to $17.40, with the upper end slightly above the consensus estimate of $17.36. FactSet also projects revenues between $2.29 billion and $2.31 billion, closely aligning with the consensus estimate of $2.30 billion. Net cash from operating activities for Q4 2024 was $163.2 million, while free cash flow decreased by 12.2% year-over-year to $137.2 million.
Analysts Adjust Price Targets Following Q4 Results and FY2025 Guidance
- BMO Capital analyst Jeffrey Silber maintained a Market Perform rating, yet raised the price target from $440 to $471.
- Wells Fargo analyst Jason Haas kept an Equal-Weight rating, while increasing the price target from $435 to $503.
- UBS analyst Alex Kramm held a Neutral rating and raised the price target from $455 to $485.
- RBC Capital analyst Ashish Sabadra maintained a Sector Perform rating, and raised the price target from $464 to $503.
Which Analyst has the best track record to show on FDS?
Analyst Shlomo Rosenbaum (STIFEL) currently has the highest performing score on FDS with 13/14 (92.86%) price target fulfillment ratio. His price targets carry an average of $3.09 (0.66%) potential upside. FactSet stock price reaches these price targets on average within 43 days.
Constellation Signs Agreement with Microsoft to Restart Three Mile Island Unit 1, Boosting Clean Energy
Constellation Energy has signed a 20-year power purchase agreement with Microsoft. This agreement will lead to the reopening of the Three Mile Island (TMI) Unit 1 reactor, which will now be called the Crane Clean Energy Center (CCEC).
The restart of TMI Unit 1 is expected to generate approximately 835 megawatts of carbon-free electricity, supporting Microsoft’s efforts to power its data centers with clean energy. The project is also projected to create 3,400 direct and indirect jobs and contribute over $3 billion in state and federal taxes.
TMI Unit 1, which had been shut down in 2019 for economic reasons, will undergo upgrades, including improvements to its turbine, generator, and other critical systems, pending approval from the U.S. Nuclear Regulatory Commission.
According to a study by The Brattle Group, the project could add $16 billion to the state's GDP by 2054. Furthermore, Constellation has committed to investing $1 million in local philanthropic initiatives over the next five years, focusing on workforce development.
Analysts Raise Price Targets Following Power Purchase Agreement
- Morgan Stanley analyst David Arcaro maintained an Overweight rating, and raised the price target from $233 to $313.
- Keybanc analyst Sangita Jain also maintained an Overweight rating, but raised the price target from $230 to $265.
- RBC Capital analyst Shelby Tucker reiterated a Sector Perform rating and the price target at $214.
- Wells Fargo analyst Jason Hass maintained an Equal Weight rating and raised the price target from $435 to $503 Weight rating.
Which Analyst has the best track record to show on CEG?
Analyst Sangita Jain (KEYBANK) currently has the highest performing score on CEG with 7/7 (100%) price target fulfillment ratio. His price targets carry an average of $14.93 (6.94%) potential upside. Constellation Energy stock price reaches these price targets on average within 68 days.
Cracker Barrel Reports Fourth Quarter 2024 Revenue and Provides 2025 Outlook Amid Inflation Pressures
Cracker Barrel Old Country Store announced its financial results for the fourth quarter of fiscal 2024, reporting total revenue of $894.4 million for the quarter. This reflects a 6.9% increase from $836.7 million in the same period last year. This figure includes a $62.8 million benefit from an additional operating week, or 53rd week. However, the revenue fell short of the consensus estimate of $898.09 million. Also reported earnings per diluted share (EPS) of $0.98, which was $0.16 lower than the analyst estimate of $1.14.
Comparable store restaurant sales experienced a slight increase of 0.4%, while comparable store retail sales decreased by 4.2%. GAAP net income for the quarter was $18.1 million, or 2.0% of total revenue, compared to $37.5 million, or 4.5% of total revenue, in the prior year. Adjusted EBITDA was $57.4 million, representing 6.4% of total revenue, down from $70.4 million, or 8.4%, in the previous fourth quarter.
For the entire fiscal year 2024, Cracker Barrel reported total revenue of $3.47 billion, up 0.8% from $3.44 billion in fiscal 2023. Comparable store restaurant sales decreased by 0.1%, and retail sales dropped by 5.5%. GAAP net income for the year was $40.9 million, or 1.2% of total revenue, lower than $99.1 million, or 2.9%, in the prior year. Adjusted net income for fiscal 2024 was $78.5 million, reflecting a decrease from $112.1 million in the prior year.
Looking ahead, Cracker Barrel projects fiscal 2025 revenue between $3.4 billion and $3.5 billion, below the consensus estimate of $3.45 billion. Additionally anticipates commodity inflation of 2% to 3%, hourly wage inflation of 3% to 4%, and adjusted EBITDA in the range of $200 million to $215 million.
Analyst Mixed Reactions Following Q4 Results
- BofA Securities analyst Sara Senatore maintained an Underperform rating, yet raised the price target from $40 to $42.
- Truist Securities analyst Jake Bartlett kept a Hold rating, while increasing the price target from $42 to $44.
- Loop Capital analyst Alton Stump maintained a Hold rating, but lowered the price target from $50 to $45.
Which Analyst has the best track record to show on CBRL?
Analyst Jon Tower (CITI) currently has the highest performing score on CBRL with 18/23 (78.26%) price target fulfillment ratio. His price targets carry an average of $-6.5 (-13.40%) potential downside. Cracker Barrel Old Country Store stock price reaches these price targets on average within 143 days.
Daily stock Analysts Top Price Moves Snapshot
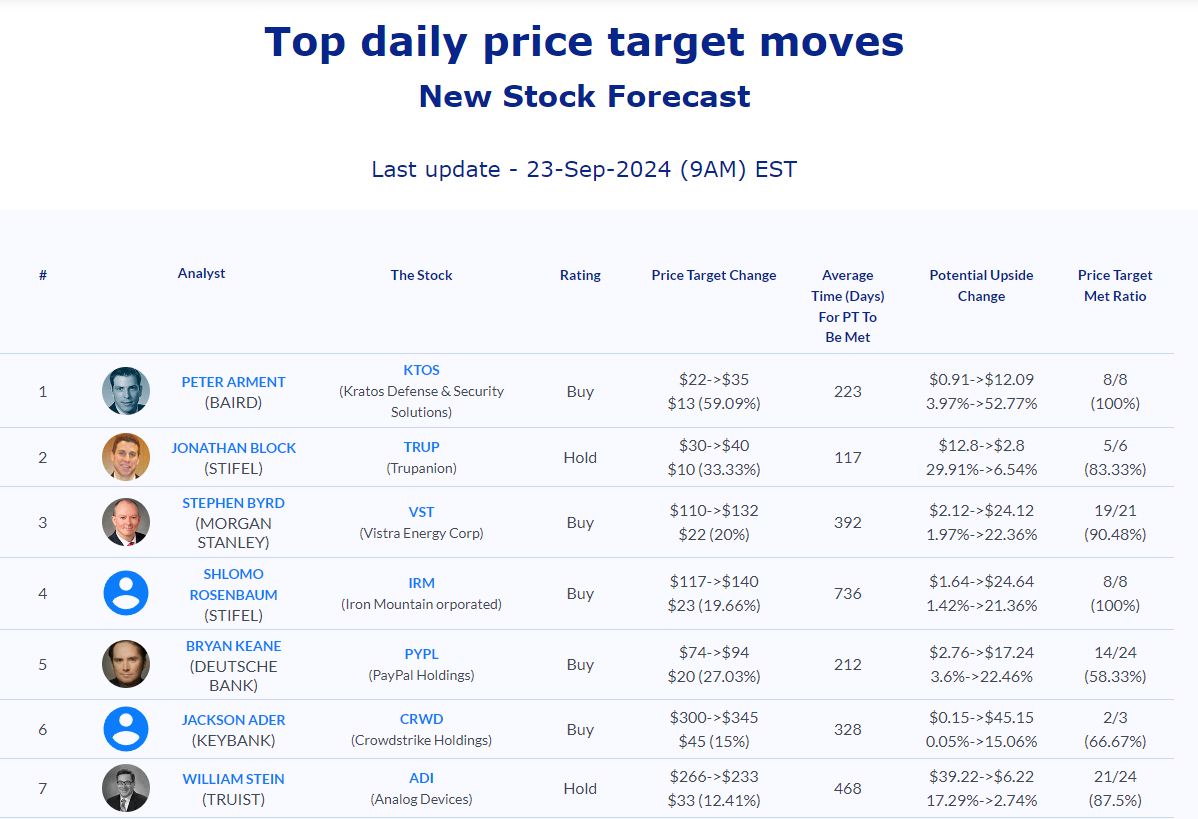
September 24, 2024: Selected stock price target news of the day: September 24th, 2024
By: Matthew Otto
Apple iPhone 16 Launch: AI Features Delayed, Early Demand Mixed
Apple’s iPhone 16 has officially launched, but its anticipated generative artificial intelligence (AI) features will not be available at release. According to Apple, the AI-driven software update, called Apple Intelligence, is scheduled to begin rolling out in October. This update will eventually bring new functionalities such as enhanced Siri capabilities and email editing across iPhones, iPads, and Macs. The initial rollout will be limited to English, with other languages following in the coming months.
Early market indicators show mixed demand for the iPhone 16 compared to previous models. Rosenblatt analyst Barton Crockett reported slightly lower shipment times and Google search volumes, though he noted that the delayed AI features might be influencing early sales. Crockett maintains a Buy rating for Apple, setting a price target of $261.
Evercore ISI analyst Amit Daryanani also observed stronger demand in the U.S. and U.K., markets where Apple Intelligence will be available sooner. Daryanani rates Apple as Outperform with a $250 price target. While iPhone sales decreased in 2023, analysts expect growth to resume by 2025, driven by hardware and software updates available in the iPhone 16.
Analysts Offer Mixed Ratings Amid Delayed AI Features
- Needham analyst Laura Martin reiterated a Buy rating and a $260 price target.
- BofA Securities analyst Wamsi Mohan reiterated a Buy rating, with a $256 price target.
- Barclays analyst Tim Long reiterated an Underweight rating, and set a price target of $186.
- Rosenblatt analyst Barton Crockett maintained a Buy rating and set a price target of $261.
- Evercore ISI analyst Amit Daryanani rated Outperform, with a $250 price target.
Which Analyst has the best track record to show on AAPL?
Analyst Krish Sankar (TD COWEN) currently has the highest performing score on AAPL with 30/31 (96.77%) price target fulfillment ratio. His price targets carry an average of $31.76 (14.55%) potential upside. Apple stock price reaches these price targets on average within 183 days.
Biohaven Reports Trial Results for Spinocerebellar Ataxia Drug, Plans FDA Submission
Biohaven reported that its investigational drug, troriluzole, met the primary endpoint in a clinical trial for Spinocerebellar Ataxia (SCA), a rare genetic disorder affecting the nervous system. Additionally, Biohaven stated that it plans to submit a marketing application to the U.S. Food and Drug Administration (FDA), with a potential market launch anticipated in 2025.
The trial data showed that troriluzole slowed disease progression by 50% to 70% over three years of treatment. The SCA condition, which is caused by the degeneration of brain and spinal cord cells, affects approximately 15,000 people in the U.S., according to company estimates, and currently has no FDA-approved treatments.
Analyst Christopher Raymond of Piper Sandler commented that troriluzole had been largely dismissed by investors after the previous regulatory issue but now forecasts potential U.S. revenues reaching $250 million by 2030.
Analyst Upgrades Following Positive Trial Results
- RBC Capital analyst Leonid Timashev maintained an Outperform rating and raised the price target from $59 to $68.
- Cantor Fitzgerald analyst Charles Duncan reiterated an Overweight rating.
- HC Wainwright & Co. analyst Douglas Tsao reiterated a Buy rating and a $59 price target.
- Piper Sandler analyst Christopher Raymond maintained an Overweight rating and raised the price target from $66 to $76.
- Baird analyst Brian Skorney held an Outperform rating and increased the price target from $58 to $60.
Which Analyst has the best track record to show on BHVN?
Analyst Tessa Romero (JPMORGAN) currently has the highest performing score on BHVN with 7/7 (100%) price target fulfillment ratio. Her price targets carry an average of $8.69 (18.37%) potential upside. Biohaven Pharmaceutical Holding stock price reaches these price targets on average within 56 days.
Lennar Reports Third Quarter Results, Exceeding Analyst Expectations with $1.2 Billion in Earnings
Lennar Corporation announced its third quarter 2024 financial results, reporting net earnings of $1.2 billion, or $4.26 per diluted share, marking a 10% increase in earnings per share from $3.87 in the prior year quarter. Excluding mark-to-market gains and one-time items, adjusted net earnings stood at $1.1 billion, or $3.90 per diluted share, which was $0.26 better than the analyst estimate of $3.64.
Revenues from home sales rose 9% to $9.0 billion, driven by a 16% increase in home deliveries, totaling 21,516 homes. New orders also saw a 5% uptick, reaching 20,587 homes, while the backlog grew to 16,944 homes valued at approximately $7.7 billion. Gross margin on home sales was reported at 22.5%, and net margin at 15.8%.
Lennar maintained its balance sheet with $4.0 billion in cash and cash equivalents and no outstanding borrowings under its $2.2 billion revolving credit facility. Lennar achieved a homebuilding debt-to-total capital ratio of 7.6%.
Looking ahead, Lennar anticipates delivering between 22,500 and 23,000 homes in the fourth quarter of 2024, with new orders projected to range from 19,000 to 19,300. The average sales price is expected to be around $425,000, with gross margins on home sales anticipated to remain flat compared to the third quarter. Additionally, Lennar forecasts financial services operating earnings of approximately $140 million.
Analyst Ratings Shift Following Q3 Results
- Evercore ISI Group analyst Stephen Kim maintained an Outperform rating, yet lowered the price target from $240 to $236.
- Citigroup analyst Anthony Pettinari kept a Neutral rating and raised the price target from $164 to $196.
- JP Morgan analyst Michael Rehaut maintained a Neutral rating while increasing the price target from $154 to $173.
- RBC Capital analyst Mike Dahl continued with an Underperform rating, and raised the price target from $145 to $160.
- Zelman & Associates upgraded from Neutral to Outperform.
Which Analyst has the best track record to show on LEN?
Analyst Susan Maklari (GOLDMAN SACHS) currently has the highest performing score on LEN with 12/12 (100%) price target fulfillment ratio. Her price targets carry an average of $1.5 (0.87%) potential upside. Lennar Corporation stock price reaches these price targets on average within 247 days.
Daily stock Analysts Top Price Moves Snapshot

September 25, 2024: Selected stock price target news of the day: September 25th, 2024
By: Matthew Otto
Smartsheet to Be Acquired by Blackstone and Vista Equity Partners in $8.4 Billion Deal
Smartsheet has entered into a definitive agreement to be acquired by Blackstone and Vista Equity Partners in an all-cash transaction valued at approximately $8.4 billion. Under the terms of the deal, Smartsheet shareholders will receive $56.50 per share, representing a 41% premium to the 90-day volume-weighted average price (VWAP) of the stock prior to media speculation about a potential sale. This offer also represents a 16% premium compared to the highest closing price over the past 12 months.
Smartsheet will continue to operate under its current brand after the transaction is finalized. The merger is anticipated to close by the end of January 2025, pending regulatory approvals and shareholder agreement.
The deal includes a 45-day go-shop period, allowing Smartsheet to explore alternative acquisition proposals. Analysts believe this period gives some flexibility, though it is uncertain whether any superior offers will emerge. Smartsheet's CEO, Mark Mader, expressed confidence that the partnership with Blackstone and Vista will support growth trajectory, highlighting the potential for enhanced innovation and employee satisfaction.
Analysts Adjust Ratings and Targets Following Announcement
- RBC Capital analyst Rishi Jaluria maintained a Sector Perform rating, while raising the price target from $51 to $56.50.
- Canaccord Genuity analyst David Hynes downgraded from Buy to Hold and the price target from $60 to $56.50.
- William Blair analyst Bhavan Suri downgraded from Outperform to Market Perform.
- Needham analyst Scott Berg downgraded from Buy to Hold, yet maintained a price target of $57.
- JP Morgan analyst Pinjalim Bora downgraded from Overweight to Neutral and the price target from $60 to $56.50.
- Wells Fargo analyst Michael Turrin downgraded from Overweight to Equal-Weight and announced a price target of $57.
- Jefferies' Brent Thill downgraded from Buy to Hold and the price target from $60 to $56.50.
- DA Davidson analyst Gil Luria downgraded from Buy to Neutral, although raised the price target from $55 to $56.50.
Which Analyst has the best track record to show on SMAR?
Analyst Rishi Jaluria (RBC) currently has the highest performing score on SMAR with 18/19 (94.74%) price target fulfillment ratio. His price targets carry an average of $-1.27 (-2.43%) potential downside. Smartsheet stock price reaches these price targets on average within 18 days.
Braze Announces Fifth Cohort of Tech for an Equitable Future Program in Partnership with BET+
Braze has announced the opening of applications for the fifth cohort of its Tech for an Equitable Future product grant program, which will run until January 17, 2025. This initiative aims to support 20 companies with underrepresented founders, including Black and women entrepreneurs, by offering 12 months of free access to Braze's technology and resources.
In an extension of the program's previous offerings, Braze has also announced its first partnership with BET+, a streaming entertainment service. BET+ will provide mentorship to five selected participants, along with additional support such as a branding masterclass and inclusion in email advertising campaigns.
To date, Braze has provided more than $900,000 in annualized product value for early-stage startups in FY'25, supporting 31 companies, including 16 founded by women.
In addition to the technology access, the program offers onboarding services, educational content, and access to a dedicated Customer Success Manager. Selected businesses are required to meet certain criteria, including being bootstrapped or having less than $30 million in venture funding, employing fewer than 100 staff, and having compatible software development resources.
Analysts Adjust Price Targets Following Program Expansion
- DA Davidson analyst Gil Luria maintained a Buy rating, but lowered the price target from $65 to $55.
- TD Cowen analyst J. Derrick Wood kept a Buy rating, yet revised the price target down from $52 to $45.
- JMP Securities analyst Patrick Walravens reiterated a Market Outperform rating and a $68 price target.
- Loop Capital analyst Yun Kim reaffirmed a Buy rating and a price target of $75.
- Oppenheimer analyst Brian Schwartz continued with an Outperform rating but adjusted the price target downward from $60 to $51.
- Needham analyst Scott Berg reiterated a Buy rating and a $70 price target.
Which Analyst has the best track record to show on BRZE?
Analyst David Hynes (CANACCORD) currently has the highest performing score on BRZE with 7/13 (53.85%) price target fulfillment ratio. His price targets carry an average of $16.35 (44.61%) potential upside. Braze stock price reaches these price targets on average within 95 days.
Capricor Therapeutics to Submit BLA for Duchenne Cardiomyopathy Therapy
Capricor Therapeutics has revealed its intent to file a Biologics License Application (BLA) for deramiocel, a cell therapy aimed at treating cardiomyopathy associated with Duchenne muscular dystrophy (DMD).
This application will be supported by existing cardiac data from the Phase 2 HOPE-2 and HOPE-2 Open Label Extension trials, along with natural history data obtained from Vanderbilt University Medical Center and Cincinnati Children's Hospital Medical Center.
Deramiocel, an allogeneic cardiac-derived cell therapy, has shown potential immunomodulatory and regenerative effects in clinical trials. To further support its application, Capricor plans to combine Cohorts A and B of the Phase 3 HOPE-3 trial as a post-approval study, without unblinding Cohort A as initially intended.
The therapy has received both Orphan Drug Designation and Regenerative Medicine Advanced Therapy Designation, which could enhance its regulatory prospects. If granted marketing approval, Capricor may be eligible for a Priority Review Voucher (PRV) based on its prior rare pediatric disease designation, potentially facilitating future regulatory submissions.
Analyst Adjustments Reflect Confidence Following BLA Announcement
- Oppenheimer analyst Leland Gershell maintained an Outperform rating and raised the price target from $15 to $43.
- Maxim Group analyst Jason McCarthy maintained a Buy rating while increasing the price target from $12 to $25.
- HC Wainwright & Co. analyst Joseph Pantginis reiterated a Buy rating and a price target of $40.
- Oppenheimer analyst Leland Gershell reiterated an Outperform rating and a price target of $15.
Which Analyst has the best track record to show on CAPR?
Analyst Jason Mccarthy (MAXIM GROUP) currently has the highest performing score on CAPR with 1/4 (25%) price target fulfillment ratio. His price targets carry an average of $6.92 (136.22%) potential upside. Capricor Therapeutics stock price reaches these price targets on average within 86 days.
Daily stock Analysts Top Price Moves Snapshot

September 26, 2024: Selected stock price target news of the day: September 26th, 2024
By: Matthew Otto
AutoZone Reports Q4 Sales Growth but Misses EPS and Revenue Expectations
AutoZone reported fourth-quarter net sales of $6.2 billion, representing a 9% increase year-over-year, but below the consensus estimate of $6.23 billion. Adjusted sales growth, excluding the extra week in this year’s quarter, was 2.6%. Same-store sales saw an increase, with domestic stores growing by 0.2%, and international stores rising 4.9%.
Gross profit margin for the quarter decreased to 52.5%, driven by a 53-basis-point non-cash LIFO impact. Operating expenses as a percentage of sales were 31.6%, up from 31.2% last year, primarily due to increased payroll costs. Operating profit improved by 6.1% to $1.3 billion, while net income rose to $902.2 million, up 4.3%. Despite the growth, AutoZone’s earnings per share (EPS) came in at $48.11, missing the analyst estimate of $53.61 by $5.50.
For the full fiscal year, AutoZone achieved $18.5 billion in sales, up 5.9% from the previous year, with gross profit margin improving to 53.1%. AutoZone repurchased 244,000 shares during the quarter for $710.6 million, contributing to a total annual repurchase of $3.2 billion. Additionally, AutoZone opened 117 new stores during the quarter, bringing its total store count to 7,353.
Analysts Adjust Price Targets Following Q4 Earnings Miss and Sales Growth
- Citigroup analyst Steven Zaccone maintained a Buy rating but lowered the price target from $3,787 to $3,500.
- Guggenheim analyst Steven Forbes maintained a Buy rating and raised the price target from $3,225 to $3,350.
- Mizuho analyst David Bellinger held an Outperform rating and increased the price target from $3,280 to $3,350.
- UBS analyst Michael Lasser continued with a Buy rating while raising the price target from $3,340 to $3,500.
- Evercore ISI Group analyst Greg Melich retained an Outperform rating, though lowered the price target from $3,350 to $3,300.
- Truist Securities analyst Scot Ciccarelli kept a Buy rating but reduced the price target from $3,394 to $3,341.
- Morgan Stanley analyst Simeon Gutman maintains an Overweight rating and lifts the price target from $3,038 to $3,125.
Which Analyst has the best track record to show on AZO?
Analyst Seth Basham (WEDBUSH) currently has the highest performing score on AZO with 34/37 (91.89%) price target fulfillment ratio. His price targets carry an average of $159.91 (5.26%) potential upside. AutoZone stock price reaches these price targets on average within 157 days.
Duolingo Unveils New AI-Powered Features and Expands Music Education at Duocon 2024
At Duocon 2024, Duolingo announced product innovations aimed at enhancing its learning platform for its 74 million monthly active users. The new AI-powered Video Call feature, available for Duolingo Max subscribers, enables real-time language practice with the character Lily in English, Spanish, and French.
This feature is designed to adapt to users' skill levels, offering a personalized and low-pressure practice environment. In addition, Duolingo introduced the Adventures feature, a game-like experience where learners can apply language skills in realistic scenarios, such as navigating passport control or ordering coffee..
Duolingo also expanded its music education offerings through a partnership with Loog, a musical instrument brand. Together, they will release a three-octave digital piano, priced at $249, to support Duolingo’s growing Music course. Additionally, Duolingo partnered with Sony Music to allow users to practice along with popular songs, broadening the appeal of its music curriculum.
Analyst Ratings and Target Increases Following Product Innovations
- JP Morgan analyst Bryan Smilek maintained an Overweight rating and raised the price target from $255 to $303.
- BofA Securities analyst Nat Schindler kept a Buy rating while increasing the price target from $292 to $298.
- JMP Securities analyst Andrew Boone continued a Market Outperform rating and raised the price target from $260 to $275.
- Needham analyst Ryan MacDonald maintained a Buy rating, but raised the price target from $245 to $310.
Which Analyst has the best track record to show on DUOL?
Analyst Nat Schindler (BAML) currently has the highest performing score on DUOL with 6/6 (100%) price target fulfillment ratio. His price targets carry an average of $71.72 (41.39%) potential upside. Duolingo stock price reaches these price targets on average within 133 days.
Meta Platforms Strengthens Partnership with EssilorLuxottica through Symbolic Investment
Meta Platforms is poised to make an investment in EssilorLuxottica to strengthen their ongoing collaboration in the development of smart eyewear. Meta CEO Mark Zuckerberg highlighted the partnership's long-term significance in a recent interview with The Verge, noting that while the investment won't be substantial, it serves as a gesture of commitment.
This partnership has been in place since 2019, resulting in the successful launch of two generations of Ray-Ban-branded smart glasses. According to reports, there were discussions about Meta acquiring a 5% stake in the French-Italian eyewear giant, which aligns with Zuckerberg's optimistic outlook on EssilorLuxottica's potential to evolve into a leading technology firm.
Zuckerberg stated that anticipated sales were underestimated by a factor of three to five times compared to the first version. The current shortage of Ray-Ban Metas indicates a market demand, prompting Meta to expand its manufacturing capabilities.
Analyst Ratings Reflect Optimism Amid Partnership
- Wedbush analyst Scott Devitt reiterated an Outperform rating and a $600 price target.
- Baird analyst Colin Sebastian maintained an Outperform rating while raising the price target from $530 to $605.
- JMP Securities analyst Andrew Boone kept a Market Outperform rating and increased the price target from $550 to $635.
- Cantor Fitzgerald analyst Deepak Mathivanan reiterated an Overweight rating and a $660 price target.
- Citigroup analyst Ronald Josey retained a Buy rating and raised the price target from $580 to $645.
Which Analyst has the best track record to show on META?
Analyst Thomas Champion (PIPER SANDLER) currently has the highest performing score on META with 19/22 (86.36%) price target fulfillment ratio. His price targets carry an average of $77.26 (15.52%) potential upside. Meta Platforms stock price reaches these price targets on average within 243 days.
Daily stock Analysts Top Price Moves Snapshot

September 27, 2024: Selected stock price target news of the day: September 27th, 2024
By: Matthew Otto
Micron Technology Tops Q4 Earnings and Revenue Estimates, Issues Robust Q1 2025 Forecast
Micron Technology reported Q4 FY2024 earnings per share (EPS) of $1.18, surpassing the analyst estimate of $1.11 by $0.07. Revenue for the quarter reached $7.75 billion, slightly ahead of the consensus estimate of $7.65 billion.
Year-over-year revenue rose by 5.7%, driven by demand in its memory and storage segments, particularly in the data center and automotive sectors. Micron also saw an increase in operating cash flow, generating $3.41 billion, compared to $2.48 billion in the previous quarter and $249 million in the fourth quarter of fiscal 2023.
Looking ahead, Micron provided guidance for Q1 FY2025, forecasting EPS of $1.74, above the consensus estimate of $1.52. Revenue for the upcoming quarter is expected to range between $8.5 billion and $8.9 billion, surpassing the analyst consensus of $8.32 billion.
For the full fiscal year 2024, Micron's revenue totaled $25.11 billion, compared to $15.54 billion in fiscal 2023, reflecting a year-over-year increase of 93%. GAAP net income for the year reached $778 million, or $0.70 per diluted share, while non-GAAP net income was $1.47 billion, or $1.30 per share. Operating cash flow surged to $8.51 billion, a rise from $1.56 billion in the previous fiscal year.
Analysts Adjust Targets Following Q4 Results and Q1 2025 Guidance
- Baird analyst Tristan Gerra maintained an Outperform rating but lowered the price target from $172 to $150.
- While Raymond James analyst Srini Pajjuri kept an Outperform rating and raised the price target from $125 to $140.
- BofA Securities analyst Vivek Arya maintained a Buy rating and increased the price target from $110 to $125.
- TD Cowen analyst Karl Ackerman held onto a Buy rating yet lifted the price target from $115 to $135.
- Meanwhile, Morgan Stanley analyst Joseph Moore kept an Equal-Weight rating but boosted the price target from $100 to $114.
Which Analyst has the best track record to show on MU?
Analyst Brian Chin (STIFEL) currently has the highest performing score on MU with 7/10 (70%) price target fulfillment ratio. His price targets carry an average of $11.55 (7.53%) potential upside. Micron Technology stock price reaches these price targets on average within 30 days.
Cintas Corporation Reports Strong Q1 Fiscal 2025 Results and Raises Annual Guidance
Cintas reported its financial results for the first quarter of fiscal 2025, with a revenue of $2.50 billion, meeting the consensus estimate. This reflects a 6.8% increase from the $2.34 billion reported in the same period last year. Adjusting for one fewer workday compared to the prior year, the same workday revenue growth was 8.4%.
The organic revenue growth rate, which excludes the impact of acquisitions, currency fluctuations, and workday differences, stood at 8.0%. Gross margin for the quarter rose to $1.25 billion, a 9.7% increase compared to $1.14 billion in the first quarter of fiscal 2024, with a gross margin percentage of 50.1%, up from 48.7% last year. Energy expenses, including gasoline and electricity, decreased by 20 basis points year-over-year.
Additionally, Cintas reported an EPS of $1.10, exceeding analyst expectations of $0.95. Operating income for the quarter reached $561.0 million, up 12.1% from $500.6 million in the previous year. Net income grew by 17.4%, amounting to $452.0 million compared to $385.1 million last year.
Cintas also announced guidance for fiscal year 2025, projecting EPS in the range of $4.17 to $4.25, aligning with the consensus of $4.17. Revenue guidance is set between $10.22 billion and $10.32 billion, slightly below the consensus estimate of $10.28 billion. Cash flow from operating activities increased by 38.5% to $466.7 million. Cintas repurchased shares worth $473.6 million and increased its quarterly dividend by 15.6%.
Analysts Mixed Sentiment Following Strong Q1 Fiscal 2025 Results
- Jefferies analyst Stephanie Moore maintained a Hold rating, while adjusting the price target down to $200 from $730.
- Goldman Sachs analyst George Tong kept a Buy rating and raised the price target from $212 to $236.
- Morgan Stanley analyst Toni Kaplan maintained an Equal-Weight rating and increased the price target from $170 to $185.
- Wells Fargo analyst Jason Haas continued with an Underweight rating but raised the price target from $184 to $191.
- UBS analyst Joshua Chan maintained a Buy rating and raised the price target from $219 to $240.
- RBC Capital analyst Ashish Sabadra kept a Sector Perform rating and increased the price target from $181 to $215.
- Baird analyst Andrew Wittmann maintained a Neutral rating while raising the price target from $194 to $209.
Which Analyst has the best track record to show on CTAS?
Analyst Seth Weber (WELLS FARGO) currently has the highest performing score on CTAS with 15/15 (100%) price target fulfillment ratio. His price targets carry an average of $-24.12 (-3.18%) potential downside. Cintas stock price reaches these price targets on average within 98 days.
Accenture Reports Strong Q4 Earnings, Forecasts Continued Growth
Accenture reported financial performance for the fourth quarter and full fiscal year ended August 31, 2024. Accenture achieved new bookings of $20.1 billion for the quarter, contributing to a record total of $81.2 billion for the fiscal year, representing a 13% increase in U.S. dollars and a 14% increase in local currency compared to the prior year.
For the fourth quarter, revenue reached $16.4 billion, reflecting a 3% increase in U.S. dollars and a 5% increase in local currency year-over-year, surpassing consensus estimates of $16.37 billion. Accenture reported a GAAP operating margin of 14.3%, an increase of 230 basis points from the previous year, while adjusted operating margin improved to 15.0%. Adjusted earnings per share (EPS) were $2.79, exceeding analysts' expectations by a penny.
Looking ahead, Accenture forecasts revenue for the first fiscal quarter between $16.85 billion and $17.45 billion, slightly below analyst estimates of $16.92 billion. For the full fiscal year 2025, Accenture anticipates GAAP EPS of $12.55 to $12.91, compared to analysts' expectations of $12.82.
Analysts React to Q4 Performance with Upgraded Ratings and Price Targets
- Susquehanna Analyst James Friedman maintained a Neutral rating and raised the price target from $350 to $360.
- BofA Securities Analyst Jason Kupferberg continued with a Buy rating while increasing the price target from $365 to $388.
- Baird Analyst David Koning kept a Neutral rating but raised the price target from $350 to $370.
- Piper Sandler Analyst Arvind Ramnani upgraded his rating from Neutral to Overweight and the price target from $329 to $395.
Which Analyst has the best track record to show on ACN?
Analyst Arvind Ramnani (PIPER SANDLER) currently has the highest performing score on ACN with 25/29 (86.21%) price target fulfillment ratio. His price targets carry an average of $-7.22 (-2.15%) potential downside. Accenture stock price reaches these price targets on average within 159 days.
Daily stock Analysts Top Price Moves Snapshot
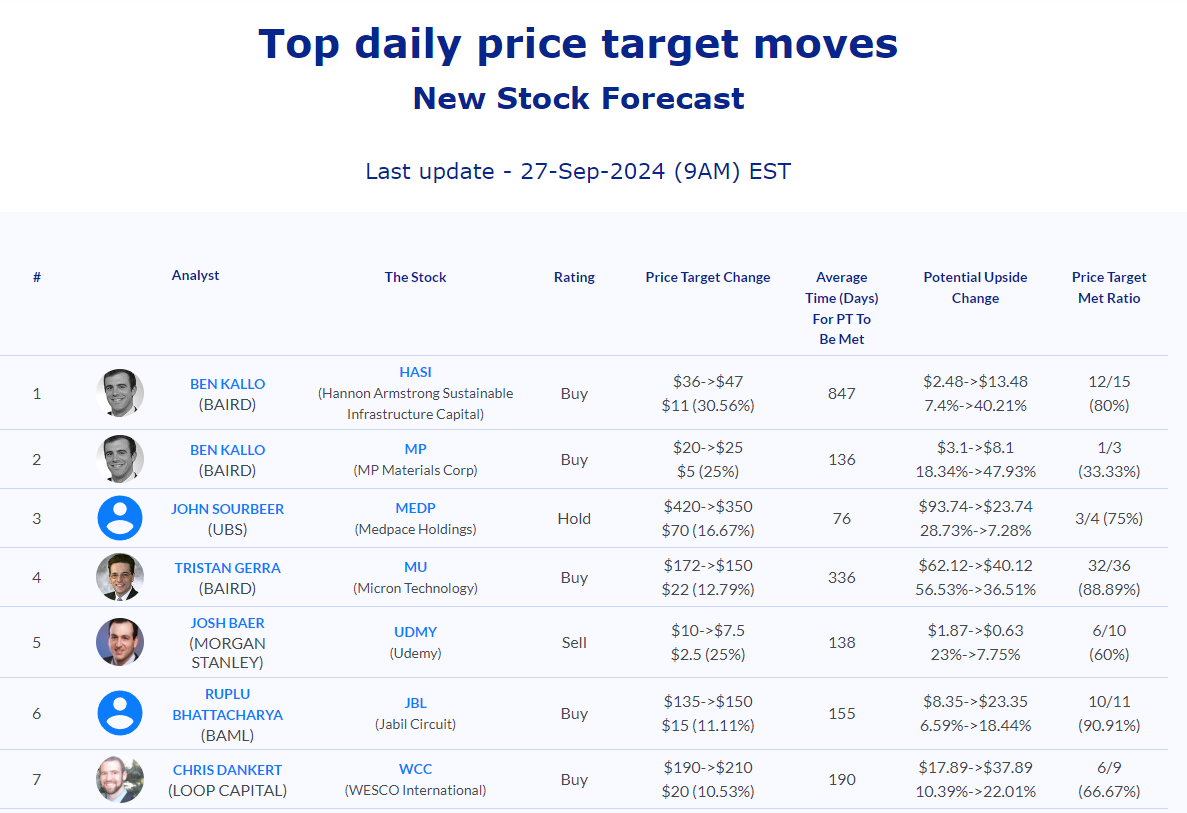
September 30, 2024: Selected stock price target news of the day: September 30th, 2024
By: Matthew Otto
Costco Exceeds Q4 Earnings Expectations Despite Slight Revenue Miss, Highlights Strong Sales Momentum
Costco Wholesale Corporation reported its financial results. For the fourth quarter, net sales reached $78.2 billion, reflecting a 1.0% increase compared to $77.4 billion in the 17-week fourth quarter of the prior year. Fiscal year net sales were $249.6 billion, a 5.0% growth from $237.7 billion in the 53-week fiscal year 2023.
Comparable sales for the quarter increased 5.4% overall, with 5.3% growth in the U.S., 5.5% in Canada, and 5.7% in other international markets. E-commerce sales grew by 18.9%. Costco's net income for the fourth quarter was $2.354 billion, or $5.29 per diluted share, up from $2.160 billion, or $4.86 per diluted share, a year earlier. This exceeded analyst expectations of $5.08 per share. However, revenue for the quarter of $79.7 billion came in slightly below the consensus estimate of $79.93 billion. For the full year, net income was $7.367 billion, up from $6.292 billion in 2023.
Oppenheimer analyst Rupesh Parikh highlighted Costco's success in expanding its nonfood offerings, particularly in apparel, which has helped boost sales despite a mixed discretionary spending environment. However, valuation concerns remain, with Truist analyst, Scot Ciccarelli, noting that Costco's price-to-earnings ratio of 50.7 times next year’s earnings exceeds its five-year average of 37.1. Nevertheless, analysts like Sky Canaves at Emarketer believe Costco remains positioned to capture increased spending from higher-income households as inflation pressures ease.
Analysts Price Target Upgrades Following Q4 Earnings Report
- DA Davidson analyst Michael Baker maintained a Neutral rating, but raised the price target from $780 to $880.
- Roth MKM analyst Bill Kirk kept a Neutral rating, yet increased the price target from $676 to $755.
- Goldman Sachs analyst Kate McShane held a Buy rating and lifted the price target from $876 to $995.
- Wells Fargo analyst George Kelly maintained an Equal-Weight rating, while raising the price target from $800 to $850.
- Telsey Advisory Group analyst Joseph Feldman continued with an Outperform rating and increased the price target from $925 to $1000.
- Barclays analyst Karen Short reiterated an Equal-Weight rating, but boosted the price target from $830 to $850.
- Truist Securities analyst Scot Ciccarelli kept a Hold rating, while raising the price target from $873 to $909.
- BMO Capital analyst Kelly Bania reiterated an Outperform rating and raised the price target from $950 to $980.
Which Analyst has the best track record to show on COST?
Analyst Krisztina Katai (DEUTSCHE BANK) currently has the highest performing score on COST with 17/19 (89.47%) price target fulfillment ratio. His price targets carry an average of $87.57 (10.43%) potential upside. Costco Wholesale Corporation stock price reaches these price targets on average within 147 days.
CarMax Reports Second Quarter 2024 Results: Growth in Unit Sales and Increased Loan Loss Provisions
CarMax reported its financial performance for the second quarter, with key highlights including a 5.1% increase in retail used unit sales and a 2.9% rise in overall unit sales compared to the previous year. Comparable store sales for used units also increased by 4.3%.
CarMax reported earnings per diluted share of $0.85, up 13.3% from $0.75 a year ago, but narrowly missing analysts' forecast of $0.86. Total revenue reached $7.01 billion, slightly lower than the previous year but above analysts’ expectations of $6.79 billion. Despite this, the average retail selling price per vehicle declined by 4.6%, while the wholesale price fell 12.9%. The gross profit per retail unit remained in line with the prior year at $2,269, while the gross profit per wholesale unit was $975.
CarMax's financial services arm, CarMax Auto Finance (CAF), saw income drop by 14.4%, primarily due to a $52.2 million increase in loan loss provisions. The allowance for loan losses now stands at $500.8 million.
Analysts like Sharon Zackfia of William Blair noted that while the loan provisions are a challenge, the uptick in retail unit sales shows promising momentum for future quarters.
Analysts Adjust Ratings and Targets After Strong Q2 Performance
- Needham analyst Chris Pierce maintained a Buy rating and raised the price target from $87 to $90.
- Truist Securities analyst Scot Ciccarelli held a Hold rating while lowering the price target from $75 to $72.
- RBC Capital analyst Steven Shemesh maintained an Outperform rating and increased the price target from $75 to $82.
- Evercore ISI Group analyst Michael Montani kept an In-Line rating and raised the price target from $76 to $79.
Which Analyst has the best track record to show on KMX?
Analyst Scot Ciccarelli (TRUIST) currently has the highest performing score on KMX with 22/26 (84.62%) price target fulfillment ratio. His price targets carry an average of $-5.32 (-6.88%) potential downside. CarMax stock price reaches these price targets on average within 76 days.
Jabil Reports Strong Q4 Performance and Provides Guidance for Fiscal Year 2025
Jabil has released its preliminary, unaudited financial results for the fourth quarter and fiscal year. In the fourth quarter, Jabil reported earnings per share (EPS) of $2.30, exceeding analyst estimates of $2.22 by $0.08. The revenue for the quarter reached $7 billion, surpassing the consensus estimate of $6.59 billion. Additionally, Jabil achieved a U.S. GAAP operating income of $318 million and diluted earnings per share of $1.18. Non-GAAP figures indicated a core operating income of $401 million, while core diluted earnings per share were reported at $2.30.
For the entire fiscal year 2024, Jabil achieved net revenue of $28.9 billion, a U.S. GAAP operating income of $2.0 billion, and diluted earnings per share of $11.17. Core operating income reached $1.6 billion, with core diluted earnings per share at $8.49. Jabil generated over $1 billion in adjusted free cash flow and returned $2.5 billion to shareholders through buybacks.
Looking ahead, Jabil provided an outlook for the first quarter of fiscal year 2025, estimating EPS between $1.65 and $2.05, compared to the consensus of $1.83. Projected revenue for Q1 2025 is anticipated to be between $6.3 billion and $6.9 billion, with a consensus of $6.5 billion. For the full fiscal year 2025, Jabil expects EPS of approximately $8.65, slightly above the consensus estimate of $8.64. Additionally, forecasts revenue of $27 billion for FY2025, slightly below the consensus of $27.2 billion.
Analyst Ratings Strengthen Following Positive Q4 Results
- Barclays analyst George Wang maintained an Overweight rating and raised the price target from $135 to $157.
- Stifel analyst Matthew Sheerin kept a Buy rating, while increasing the price target from $130 to $140.
- BofA Securities analyst Ruplu Bhattacharya reiterated a Buy rating and lifted the price target from $135 to $150.
Which Analyst has the best track record to show on JBL?
Analyst Matthew Sheerin (STIFEL) currently has the highest performing score on JBL with 13/15 (86.67%) price target fulfillment ratio. His price targets carry an average of $17.66 (14.44%) potential upside. Jabil Circuit stock price reaches these price targets on average within 123 days.
Daily stock Analysts Top Price Moves Snapshot
