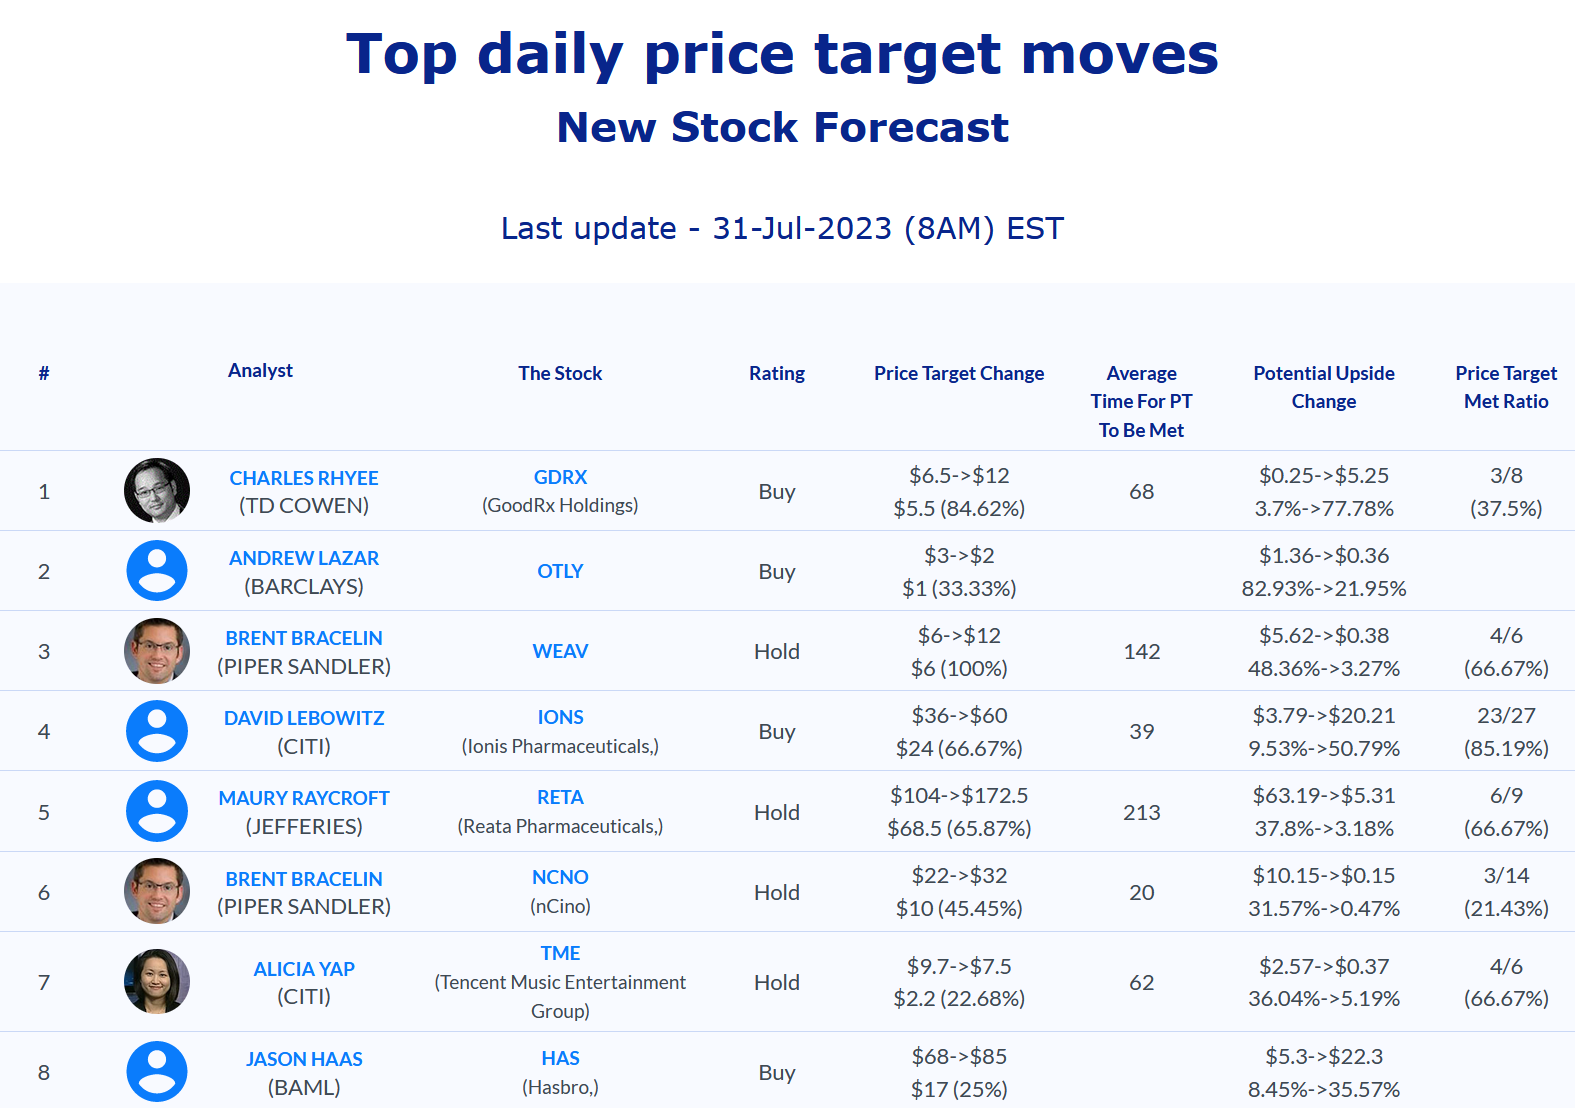
The analyst price target moves we wrote up each trading day in July 2023, 20 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
July 3, 2023: Selected stock price target news of the day: July 03, 2023
By Matthew Otto
Eli Lilly to Acquire Sigilon Therapeutics
pharmaceutical giant Eli Lilly revealed last week its plans to acquire Sigilon Therapeutics. , a company specializing in cell therapies, particularly for diabetes patients. The acquisition aims to provide Lilly with access to innovative experimental treatments that offer longer-term solutions for individuals living with diabetes.
Lilly, renowned for its extensive portfolio of diabetes drugs and insulin. Already held an 8.44% stake in Sigilon as of March 27. However, the company now intends to purchase all remaining shares. The deal involves an upfront cash payment of $14.92 per share, totaling $34.6 million, for the remaining shares of Sigilon.
Sigilon shareholders will also have the opportunity to earn an additional $111.64 per share if specific developmental and regulatory milestones are achieved. As stated by Lilly.
The transaction is expected to be completed during the third quarter of 2023, granting Lilly access to Sigilon's proprietary cell therapy candidate developed specifically for the treatment of type 1 diabetes.
This collaboration between Eli Lilly and Sigilon is not new, as the two companies have been partners since 2018. Back then, Lilly entered into a licensing agreement with Sigilon, investing $63 million to develop cell therapies targeting type 1 diabetes. However, the exact details of Lilly's undisclosed equity investment were not disclosed.
It is worth noting that Lilly's diabetes product portfolio significantly contributed to over 50% of its total revenue in 2022.
Morgan Stanley adjust Price Target on Sigilon
- Morgan Stanley analyst Matthew Harrison maintains an Equal-Weight however he raises the price target from $7 to $21.
Harrison is also currently the analyst with the highest performing score on SGTX with 3/5 (60%) price target fulfillment ratio. His price targets carry on an average of $-0.04 (11.82%) potential downside and typically reach target within an average of 429 days.
Agenus Reports Promising Phase 1b Trial Data for Treating Metastatic Colorectal Cancer
Agenus revealed data from its Phase 1b trial concerning the combination of botensilimab and balstilimab at the 2023 ESMO World Congress on Gastrointestinal Cancer. This data demonstrates survival benefits and sustained responses for patients with non-MSI-H (microsatellite stable or non-microsatellite instability-high) metastatic colorectal cancer, a condition historically resistant to chemotherapy and immunotherapy.
According to the Chief Medical Officer at Agenus, Dr. Steven O'Day, these results not only indicate the potential of the botensilimab/balstilimab combination for colorectal cancer treatment but also show promise for multiple challenging cancer types. Supporting this assertion, Dr. Andrea Bullock, a study investigator, highlighted the significant survival benefit observed in the trial, with 69% of objective responses ongoing at the data cutoff.
Analysts Maintain Positive Outlook on Agenus
- Colleen Kusy from Baird initiates coverage on Agenus with an Outperform rating and a price target of $8.
- Tony Butler from EF Hutton reiterates a Buy rating and a price target of $8.3.
- Emily Bodnar from HC Wainwright reiterates a Buy rating and a maintained price target of $8.
Analyst Michael King (BENCHMARK) has currently the highest performing score on AGEN with his price targets carrying on an average of $7.74 (289.82%) potential upside.
Tesla Surpasses Expectations with Record-Breaking Deliveries and Production in Q2 2023
Tesla's Q2 2023 report shows a growth in vehicle production and deliveries, surpassing analysts' expectations. The EV giant delivered a total of 466,140 vehicles while producing 479,700 units. The significant growth, representing an 83% year-over-year increase. Can be attributed to expanded manufacturing capacity and boosted production at Tesla's Austin plant. 96% of Tesla's deliveries consisted of its Model 3 and Model Y vehicles.
Tesla currently operates several assembly plants worldwide, with plans to construct a new factory in Monterrey, Mexico. CEO Elon Musk revealed plans to deliver the Cybertruck in 2023 and a revamped version of the Model 3 in North America.
Analysts Provide Mixed Ratings and Price Targets for Tesla
- Citigroup Analyst Itay Michaeli reiterates a Neutral rating and a price target of $215.
- Wedbush Analyst Daniel Ives maintains an Outperform rating and a price target of $300.
- Truist Securities Analyst William Stein raises the price target to $240 from $154 while maintaining a Hold rating.
- Deutsche Bank Analyst Emmanuel Rosner increases the price target to $270.
Analyst George Galliers (GOLDMAN) has currently the highest performing score on TSLA with 6/7 (85.71%) price target fulfillment ratio. His price targets carry on an average of $-4.19 (-4.36%) potential downside and typically reach target within an average of 94 days.
Daily stock Analysts Top Price Moves Snapshot

July 5, 2023: Selected stock price target news of the day: July 05, 2023
By Matthew Otto
Protagonist Therapeutics' Shows Trial Results for Oral Psoriasis Treatment JNJ-2113
Protagonist Therapeutics announced results from the Phase 2b FRONTIER 1 clinical trial of JNJ-2113, an oral interleukin-23 receptor (IL-23R) antagonist, in treating moderate-to-severe plaque psoriasis. The trial achieved all primary and secondary efficacy endpoints, and a larger proportion of patients who received JNJ-2113 experienced significant improvements in skin lesions, as measured by the Psoriasis Area and Severity Index (PASI), compared to those who received a placebo.
Patients treated with JNJ-2113 demonstrated achievement of PASI 75, PASI 90, and PASI 100 (75%, 90%, and 100% improvement in skin lesions respectively) at week 16. These trial results support the advancement of JNJ-2113 into phase 3 clinical development for the treatment of moderate-to-severe plaque psoriasis in adult patients.
Plaque psoriasis is the most prevalent form of psoriasis in the United States, impacting approximately 6.7 million adults. It is characterized by the formation of raised, red, and scaly patches on the skin. This condition can cause significant discomfort and distress for those affected.
Analysts Differing Price Targets for Protagonist Therapeutics, Bullish Outlook Prevails
- Piper Sandler analyst Yasmeen Rahimi reiterates an Overweight rating and a price target of $35.
- BTIG analyst Julian Harrison maintains a Buy rating and a price target of $41.
- Jefferies analyst Roger Song raises the price target from $40 to $49 while maintaining a Buy rating.
Analyst Jonathan Wolleben (JMP) has currently the highest performing score on PTGX with 3/6 (50%) price target fulfillment ratio. His price targets carry on average an $16.25 (62.94%) potential upside and typically reach target within an average of 110 days.
Rivian Automotive's Q2 2023 Deliveries
Rivian Automotive showed growth in the second quarter, manufacturing 13,992 electric vehicles and selling 12,640 units. This positive news pleased investors, reflected in an 8% increase in Rivian's stock price, reaching around $18 per share. In comparison, the S&P 500 was slightly down, while the Nasdaq Composite saw a small increase. Over the past month, Rivian shares have risen approximately 25%.
The remarkable growth is the driving force behind this positive performance. Production soared over 200% compared to the previous year, rising from 9,395 vehicles in the first quarter. Sales also saw an increase of about 180% year over year, surpassing the 7,946 units sold in the first quarter.
Exceeding expectations is another factor contributing to the investor satisfaction. Wall Street predicted around 11,000 units to be delivered, but Rivian surpassed that figure. Higher deliveries translate to increased sales and potentially a smaller-than-anticipated loss for the second quarter.
Rivian has already produced around 23,000 units in 2023, well on track to meet its full-year target of approximately 50,000 units.
Analysts Offer Mixed Perspectives on Rivian
- DA Davidson analyst Michael Shlisky has upgraded from Underperform to Neutral and the price target from $11 to $18.
- Needham analyst Chris Pierce maintains a Buy rating and raises the price target from $26 to $28.
- Piper Sandler analyst Alexander Potter has downgraded from Overweight to Neutral and his price target from $63 to $15.
Analyst Mark Delaney (GOLDMAN) has currently the highest performing score on RIVN with 5/5 (100%) price target fulfillment ratio. His price targets carry on an average of $-6.8 (4.77%) potential downside and typically reach target within an average of 29 days.
Foxconn's Revenue Raises Concerns for Apple as Smartphone Sales Weaken
A key supplier of Apple, Foxconn Technology. Has announced a decrease in revenue in the previous month, largely due to a drop in smartphone sales.
The slump in Foxconn's performance also reflected in the company's quarterly figures, with total revenue for the three months up to the end of June at NT$ 1,302.7 billion. This marks a 10.9% decrease quarter over quarter and a 13.8% drop from a year earlier. Foxconn's computing products segment showed double-digit growth, while components remained stagnant, and other segments, including cloud and networking products, and smart consumer electronics like iPhones, declined.
Given Apple's dependence on iPhone sales for its quarterly profits, Foxconn's current financial scenario could potentially forecast upcoming market trends for Apple's flagship product.
Analyst Views on Apple Stock Differ
- UBS analyst David Vogt reiterated a Neutral rating and a price target of $190.
- DA Davidson downgraded to Neutral and the price target to $185.
- Jefferies analyst Kyle McNealy raised the price target to $135 while maintaining a Buy rating.
Analyst David Vogt (UBS) has currently the highest performing score on AAPL with 23/23 (100%) price target fulfillment ratio. His price targets carry on an average of $26.94 (19.05%) potential upside and typically reach target within an average of 149 days.
Daily stock Analysts Top Price Moves Snapshot

July 6, 2023: Selected stock price target news of the day: July 06, 2023
By: Matthew Otto
Apple Hospitality Acquires Courtyard in Cleveland
Apple Hospitality REIT announced its acquisition of the newly renovated Courtyard by Marriott Cleveland University Circle for $31 million. The 154-room hotel is located at 2021 Cornell Road in Cleveland's University Circle district and has recently undergone a complete renovation, enhancing its guest rooms, public spaces, meeting facilities, fitness center, and adding one more guest room.
The hotel is located near major league sports stadiums and corporations across multiple industries, which drive additional demand to the area. It is also surrounded by various demand generators, including business, leisure, academic, health care, and medical research sectors.
Following the acquisition, Apple Hospitality's portfolio now consists of 221 hotels with 29,138 guest rooms spread across 37 states.
Analysts Provide Mixed Reviews on Apple Hospitality REIT's Performance
- Oppenheimer Analyst Tyler Batory maintains an Outperform rating and lowers the price target from $21 to $19.
- Barclays Analyst Anthony Powell remains in an Overweight rating and raises the price target from $19 to $20.
- Compass Point Analyst Floris van Dijkum downgrades from Buy to Neutral with a price target of $17.
Analyst Anthony Powell (BARCLAYS) has currently the highest performing score on APLE with 4/10 (40%) price target fulfillment ratio. His price targets carry on an average of $3.78 (30.33%) potential upside and typically reach target within an average of 198 days.
Meta Platforms' Messaging App Threads Gains Early Traction
Meta Platforms launched its messaging app Threads. According to analysts Threads has the advantage of easy access to billions of Instagram users, a similar interface to Twitter, and the advertising power of Meta, the parent company of Instagram. The app gained traction, with 10 million sign-ups within the first seven hours, including participation from celebrities like Kim Kardashian and Gordon Ramsay.
Threads is built upon the Instagram platform, allowing users to log in with their Instagram credentials. With Instagram's user base of over 2 billion monthly active users, Threads has a head start compared to Twitter, which had 229 million monthly active users in May 2022. Mastodon, another Twitter-like app, has 1.7 million monthly active users.
Analysts Upgrades Price Targets for Meta Platforms
- Keybanc analyst Justin Patterson maintains an Overweight and raises the price target from $280 to $335.
- Citigroup analyst Ronald Josey reiterates a Buy rating and raises the price target from $315 to $360.
Analyst Daniel Salmon (BMO) has currently the highest performing score on META with 21/23 (91.3%) price target fulfillment ratio. His price targets carry on an average of $18.89 (8.54%) potential upside and typically reach target within an average of 81 days.
JetBlue Ends Alliance with American Airlines to Focus on a New Merger
JetBlue Airways announced that it would not appeal a U.S. court's order to end its alliance with American Airlines Group. The airline is instead initiating the process to wind down the three-year alliance. The termination of this partnership follows a ruling by U.S. District Judge Leo Sorokin in May that the so-called "Northeast Alliance" was diminishing competition, an assertion that American Airlines described as "erroneous" and plans to appeal.
Meanwhile, JetBlue is shifting its focus to a proposed $3.8 billion merger with Spirit Airlines. The potential alliance would be the largest merger in the U.S. airline industry since the tie-up between American and US Airways in 2013. The New York-based airline believes that by ending the partnership with American, the objections from the U.S. Department of Justice (DOJ) to the Spirit merger become moot. The DOJ had previously attempted to block the merger, citing concerns about potential higher fares and fewer seats for consumers. However, the DOJ has declined to comment on JetBlue's recent statement.
Analysts Ratings and Price Targets Upgraded for JetBlue Airways
- JP Morgan Analyst Jamie Baker upgraded from Underweight to Overweight and the price target from $15 to $25.
- Bank of America Analyst Andrew Didora maintained a Neutral rating and raised the price target from $9 to $10.
- Cowen Analyst Helane Becker increased the rating from Market Perform to Outperform and set a price target of $24.
Analyst Andrew Didora (BAML) has currently the highest performing score on JBLU with 9/13 (69.23%) price target fulfillment ratio. His price targets carry on an average of $1.46 (13.73%) potential upside and typically reach target within an average of 86 days.
Daily stock Analysts Top Price Moves Snapshot

July 7, 2023: Selected stock price target news of the day: July 07, 2023
By: Matthew Otto
FIS Achieves Certification for FedNow Service, Paving the Way for Instant Payments
Fidelity National Information Services completed testing and certification for the FedNow Service, the Federal Reserve's new instant payment offering. The certification obtained by FIS is specifically for "Credit Transfer – Receive Only" payments. That lets FIS receive payments from any financial institution utilizing the FedNow network, send payment returns, and provide acknowledgements, requests, and responses.
By achieving this certification, FIS is fully prepared to assist its client financial institutions in leveraging the FedNow Service. This will enable these institutions to offer their customers 24/7 instant payments, enhance their competitiveness, and develop new products.
FIS recognizes the growth of digital payments and views the FedNow Service as a crucial solution for the industry. As a result, FIS has done early adoption and will contribute to the modernization of the U.S. payments system. The company continues enhancing its capabilities and features so its bank clients can use the FedNow Service to serve their customers.
Analyst Shows Mixed Ratings and Revised Price Targets
- Raymond James analyst John Davis Maintains Strong Buy rating and lowers price target from $83 to $79.
- Wolfe Research analyst Darrin Peller Reiterates Peer Perform rating.
- Stephens analyst Charles Nabhan Lowers price target to $69.
Analyst Jeff Cantwell (WELLS FARGO) has currently the highest performing score on FIS with a 7/9 (77.78%) price target fulfillment ratio. His price targets carry on an average of $12.82 (12.41%) potential upside and typically reach target within an average of 92 days.
Microsoft Could Become the Next $3 Trillion Mega-Cap Tech Stock, Morgan Stanley says
Morgan Stanley has identified Microsoft as the next mega-cap tech stock likely to achieve a $3 trillion valuation, following Apple's recent milestone. The analyst considers Microsoft a "Top Pick". He cites its strong position in the generative AI race and its ability to monetize this growing trend. The bank has increased Microsoft's price target by 24% to $415 from $335.
According to Morgan Stanley's Keith Weiss, Microsoft's investment in OpenAI could be worth a $90 billion incremental opportunity in 2025. Weiss highlights Microsoft's integration of AI capabilities into its software offerings, such as Office 365, Azure, and GitHub. He expects that to add to its pricing power.
Weiss also emphasizes that Microsoft's financials will benefit from AI sooner rather than later. Bigger datasets should drive higher revenues for the company's Azure cloud service. Despite Microsoft's stock already experiencing a significant year-to-date increase, Weiss concludes that the valuation remains reasonable compared to historical averages. The bank says Microsoft's position in generative AI and its valuation support its potential for further growth in the AI market.
Analysts Express Positive Outlook on Microsoft with Raised Price Targets and Buy Ratings.
- Morgan Stanley analyst Keith Weiss maintains an Overweight rating and raises the price target from $335 to $415.
- Wedbush analyst Daniel Ives reiterates an Outperform rating and a $375 price target.
- D.A. Davidson analyst Gil Luria sets a Buy rating and a $270 price target.
Analyst Gil Luria (D.A. DAVIDSON) has currently the highest performing score on MSFT with
2/2 (100%) price target fulfillment ratio. His price targets carry on average an $53.6 (21.96%) potential upside and typically reach target within an average of 73 days.
Levi Strauss Cuts Annual Profit Forecast as Costs Rise and Sales Decline
Levi Strauss has cut its annual profit forecast due to higher costs and declining sales at its wholesale channels in North America. Levi's net revenues for the second quarter declined by 9%, marking the steepest quarterly drop since Q1 2021. To stimulate sales among price-sensitive shoppers, Levi Strauss reduces prices on select products sold through wholesale channels.
The company revised the profit forecast for 2023 to $1.10 to $1.20 per share. The previous range was $1.30 to $1.40. Adjusted gross margin is also expected to contract, and the forecasted annual net revenue growth has been narrowed down.
Levi Strauss faced supply chain challenges in its US distribution centers due to inventory backlog. While revenue in the direct-to-consumer channel increased by 13% during the second quarter. Wholesale fell 22% as wholesalers tightened their inventories in North America and Europe. The company's net income for the second quarter was $1.6 million, lower compared to $49.7 million in the same period the previous year.
Analysts Maintain Ratings for Levi Strauss, Lower Price Targets
- Citigroup analyst Paul Lejuez maintains a Neutral rating and lowers the price target from $15 to $14.
- Stifel analyst Drew Crum reiterates a Buy rating and lowers the price target from $19 to $17.
- Wells Fargo analyst Ike Boruchow remains an Overweight rating and lowers the price target from $18 to $15.
- Telsey Advisory Group analyst Dana Telsey maintains an Outperform rating and lowers the price target from $24 to $18.
Analyst Dana Telsey (TELSEY ADVISORY) has currently the highest performing score on LEVI with 4/11 (36.36%) price target fulfillment ratio. Her price targets carry on average an
$7.2 (44.86%) potential upside and typically reach target within an average of 113 days.
Daily stock Analysts Top Price Moves Snapshot
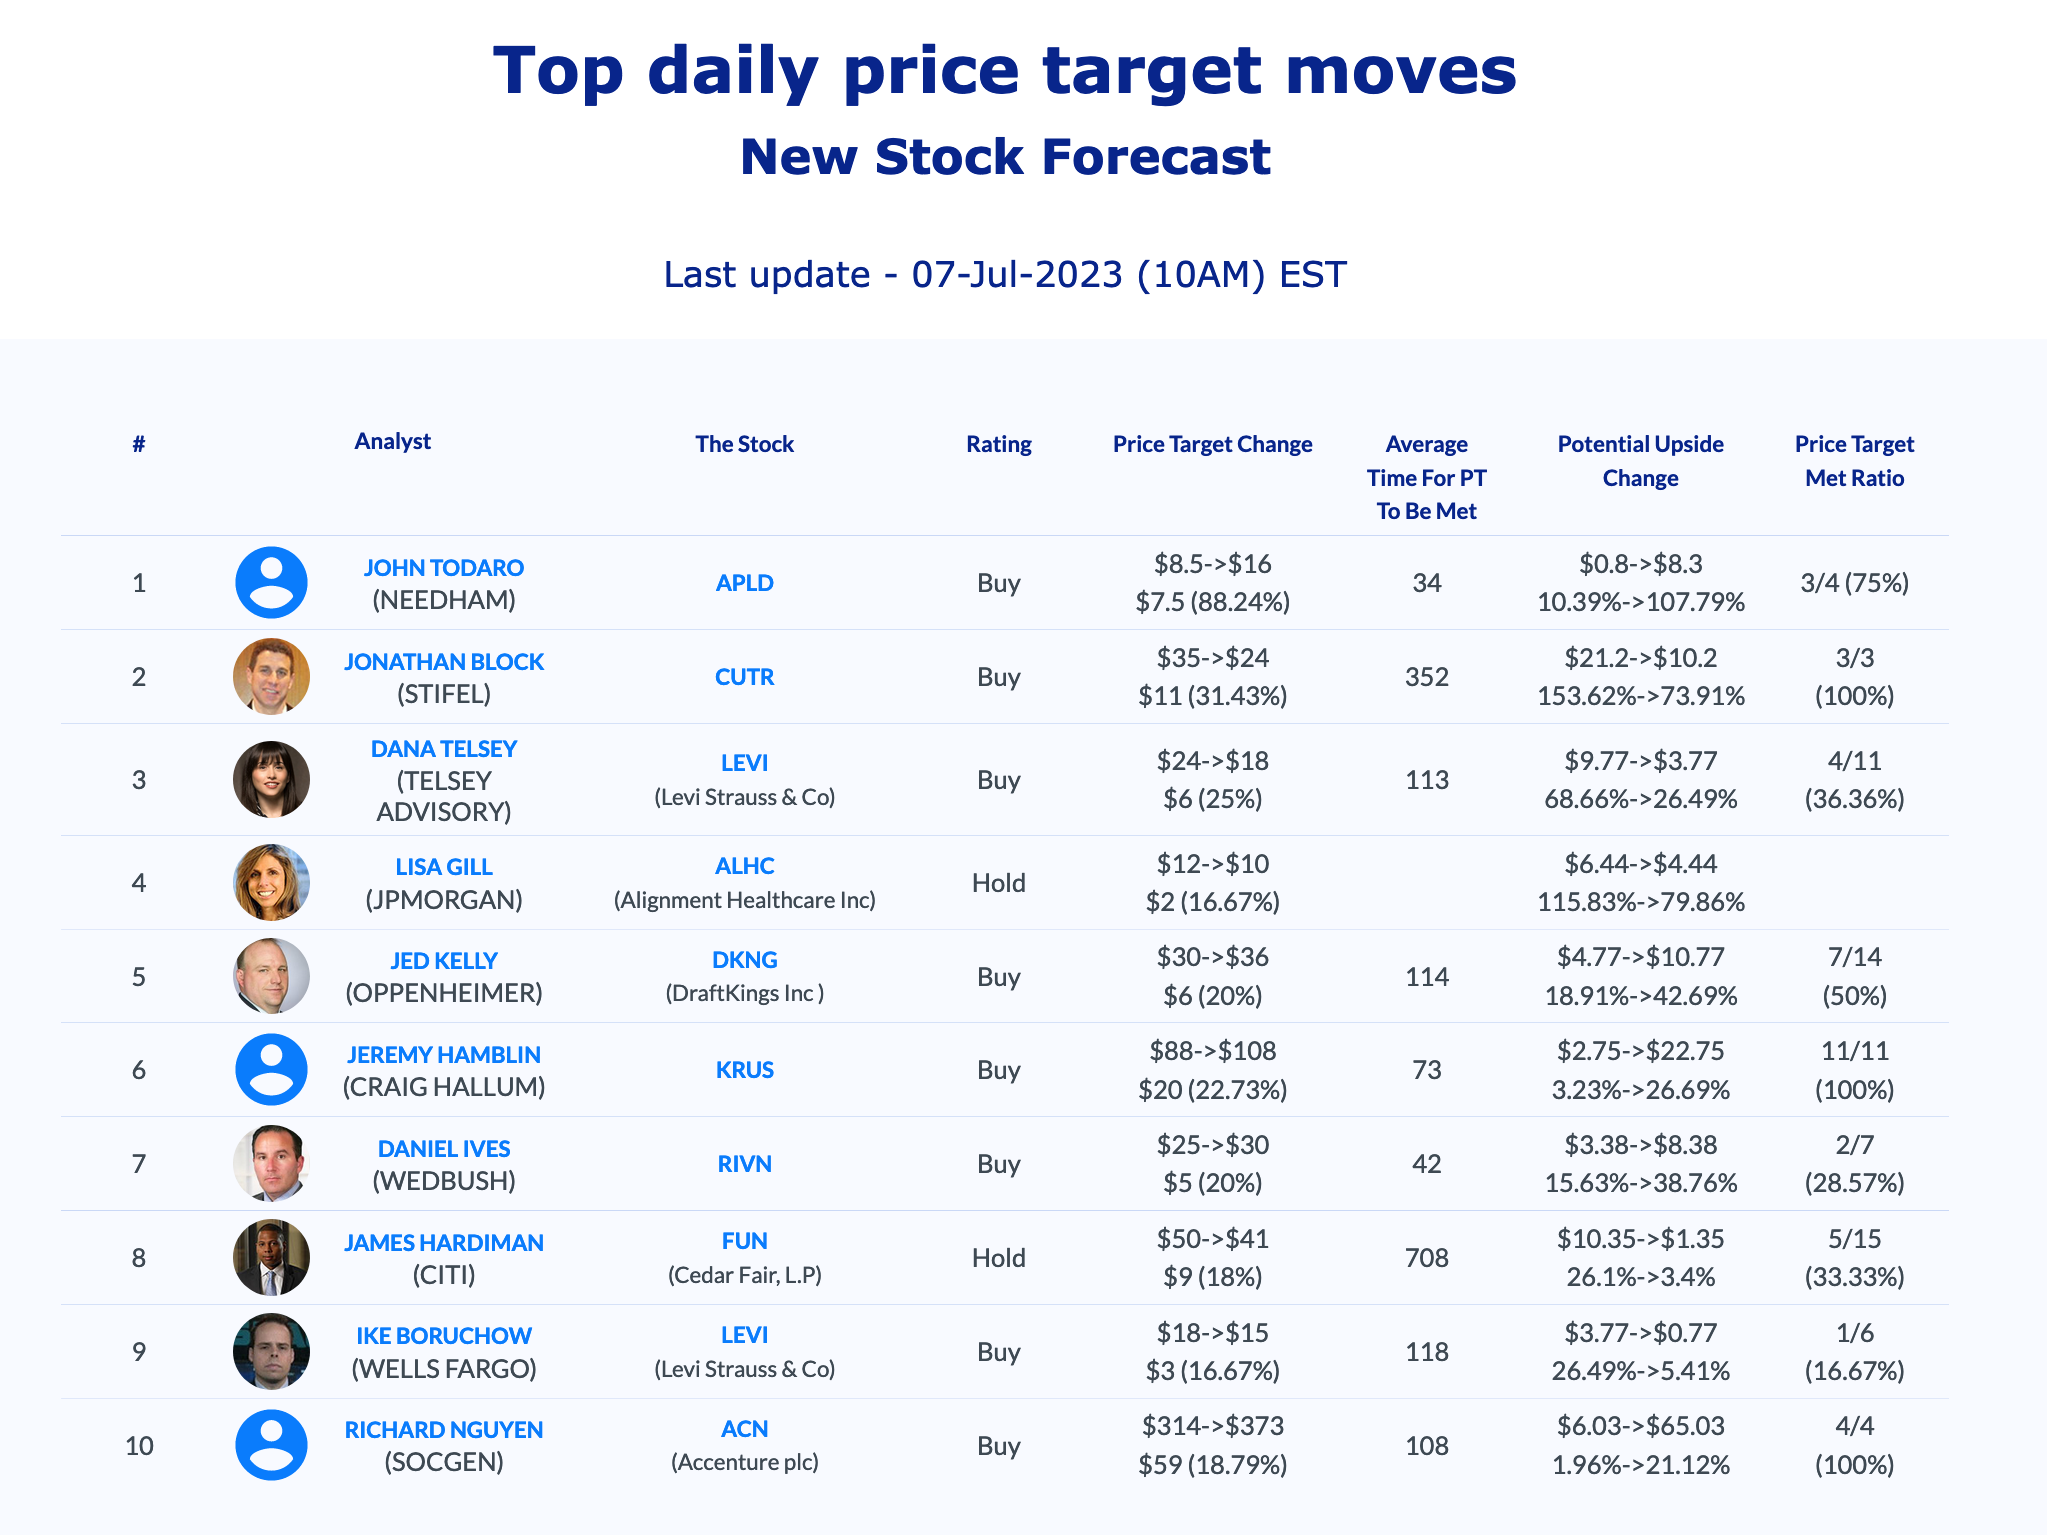
July 10, 2023: Selected stock price target news of the day: July 10, 2023
By Matthew Otto
Analyst is Optimistic on AI Growth Opportunities of Nvidia
Tigress Financial Partners is optimistic about Nvidia's potential in the artificial intelligence (AI) sector. Analyst Ivan Feinseth believes that Nvidia's innovative abilities and industry-leading position will allow it to benefit from the accelerating adoption of AI in various technologies and applications, including autonomous vehicles. Healthcare, and other emerging opportunities.
Nvidia's products have an exposure to generative AI, which has gained popularity this year. This technology involves using brute-force methods to create content by ingesting text, images, and videos. The interest in generative AI was sparked by OpenAI's release of ChatGPT, a language model that utilizes similar techniques.
Ivan Feinseth also notes that Nvidia stands to benefit from a shift in technology infrastructure spending away from traditional server processors towards Nvidia's chips. These semiconductors are better suited to handle the computations required for advanced AI products.
Analysts Remain Bullish on NVIDIA, Raise Price Targets
- Tigress Financial analyst Ivan Feinseth maintains a Buy rating and raises the price target from $320 to $560.
- Daiwa Capital analyst Louis Miscioscia upgrades from Neutral to Outperform and the price target from $408 to $475.
- Goldman Sachs analyst Toshiya Hari raises the price target to $495 from $440 while maintaining a Buy rating.
Analyst Richard Shannon (CRAIG HALLUM) has currently the highest performing score on NVDA with 17/20 (85%) price target fulfillment ratio. His price targets carry on average an $7.42 (4.55%) potential upside and typically reach target within an average of 59 days.
Fisker Stock Rises as Company Announces $300 Million Fundraising Plan
Fisker announced plans to raise $300 million in convertible notes. The convertible notes can potentially lead to the issuance of around 100 million additional Fisker shares, diluting the existing shares. However, investors do not need to make interest payments on the notes. Fisker's ability to access capital is seen as a positive factor. Especially considering the challenges faced by other electric vehicle start-ups like Lordstown Motors.
Unlike owning a manufacturing plant. Fisker has opted for a more capital-efficient approach by partnering with Magna International for the production of its first vehicle, the Ocean SUV. Although Fisker had approximately $650 million in cash at the end of the first quarter, it is expected to spend an additional $300 million in the remaining three quarters of 2023. Raising funds preemptively is considered a prudent move by Fisker to ensure it has adequate resources before the need becomes critical.
Analysts Hold Different Views on Fisker's Performance
- Wolfe Research analyst Rod Lache downgrades from Peer Perform to Underperform and sets a $6 price target.
- RF Lafferty analyst Jamie Perez maintains a Buy rating but lowers the price target from $15 to $12.
Analyst Jaime Perez (LAFFERTY) has currently the highest performing score on FSR with 3/6 (50%) price target fulfillment ratio. His price targets carry on average an $5.71 (59.14%) potential upside and typically reach target within an average of 18 days.
FMC Faces Unprecedented Inventory Reductions, Affects Revenue Outlook for Q2 and Full Year
FMC experienced unexpected and significant reductions in channel inventory by customers in North America. Latin America, and EMEA (Europe, the Middle East, and Africa) at the end of May. This led to a sharp decline in volume in three out of four operating regions. FMC's CEO, Mark Douglas, stated that channel partners rapidly reduced inventory levels, resulting in unforeseen volume declines.
As a result, FMC has adjusted its financial outlook. Second-quarter revenue is now expected to be between $1 billion and $1.03 billion. Down from the previous estimate of $1.42 billion to $1.48 billion. The full-year revenue forecast has also been revised downwards to between $5.2 billion and $5.4 billion. Compared to the earlier projection of $6.08 billion to $6.22 billion.
FMC's stock has fallen by 16% in 2023 so far. To address the impact of these challenges. FMC has implemented cost mitigation measures, resulting in a reduction of operating expense estimates by $60 million to $70 million in the second half of the year.
Analyst Maintain Buy Ratings for FMC
- Morgan Stanley analyst Vincent Andrews reiterates Overweight rating and a price target of $145.
- Chris Parkinson from Mizuho Securities maintains a Buy rating and sets a price target of $150.
Analyst Vincent Andrews (MORGAN STANLEY) has currently the highest performing score on FMC with 8/10 (80%) price target fulfillment ratio. His price targets carry on average an $15.27 (15.41%) potential upside and typically reach target within an average of 144 days.
Daily stock Analysts Top Price Moves Snapshot

July 11, 2023: Selected stock price target news of the day: July 11, 2023
By Matthew Otto
Amazon's Stock May Benefit from Prime Day Sales Boost
Amazon's Prime Day is scheduled for July 11-12 this year. It is an exclusive sales event for Amazon Prime members. The event offers discounts on various products, such as smart security cameras, beauty products, clothing, and personal electronics.
Prime Day is a significant contributor to Amazon's business success, with record-breaking sales reported in previous years. In 2022, Prime members purchased over 300 million items during the event, setting a new company record. Analysts anticipate even better results this year.
BofA Securities analyst Justin Post expects a strong Prime Day, potentially surpassing the 12% growth estimate compared to Prime Day last July. This could potentially lead to increased gross merchandise value for Amazon in the third quarter.
Consumers' cost-consciousness has been heightened due to factors like high inflation and rising interest rates. Although the consumer confidence index increased in June, reaching its highest level since January 2022, the expectations index, which reflects consumers' short-term outlook for income, remains low, indicating concerns about a future recession. Given these circumstances, analysts believe the timing is favorable for Prime Day 2023, as consumers continue to seek deals and cost-conscious options. Retailers, including Amazon, have acknowledged consumers' increased focus on affordability this year.
Analysts Offer Positive Ratings and Price Targets for Amazon.com
- JMP Securities analyst Nicholas Jones reiterates with a Market Outperform rating and a $140 price target.
- DBS Bank analyst Sachin Mittal initiates coverage with a Buy rating and a $150 price target.
- BofA analyst Justin Post maintains Buy rating and increases the price target from $139 to $154.
Analyst Laura Martin (NEEDHAM) has currently the highest performing score on AMZN with 16/19 (84.21%) price target fulfillment ratio. Her price targets carry on average an $22.55 (20.08%) potential upside and are fulfilled within an average of 136 days.
PVH Announces Further Job Cuts, Aiming to Boost Annual Savings
PVH has announced additional layoffs, expanding on a reduction strategy disclosed last year. In August 2022, PVH had announced plans to decrease personnel costs by roughly 10% across its global offices by the end of 2023. This move resulted in a pretax cost of $20 million due to severance payments in 2022. However, the company anticipates it will lead to annual savings exceeding $100 million.
While the number of new job cuts remains unspecified, PVH expects the latest round of severances to cost about $50 million.
Analysts Adjust PVH Price Targets Following Layoff Announcement
- TD Cowen's analyst John Kernan maintains a Market Perform rating and has reduced the price target from $95 to $92.
- BMO Capital's Simeon Siegel gives a Market Perform rating and increases the price target from $81 to $90.
- Dana Telsey from the Telsey Advisory Group reiterates an Outperform rating and a price target of $102.
Analyst Matthew Boss (JPMORGAN) has currently the highest performing score on PVH with 16/19 (84.21%) price target fulfillment ratio. His price targets carry on average an $7.21 (8.44%) potential upside and are fulfilled within an average of 175 days.
Apple's Eyes $3 Trillion Market Cap Despite Spending Dip
Apple, despite briefly achieving a $3 trillion market capitalization in June, saw its market cap slide back down. KeyBanc Capital Markets analysts have set a new price target of $200 per share, indicating potential for Apple to regain its peak valuation. This optimistic outlook persists despite predictions of an upcoming spending slowdown on Apple products.
Brandon Nispel examined data from 1.8 million unique credit and debit card customers, revealing a 23% month-over-month rise in Apple transactions of $400 or more in June. However, the same data also showed a 15% quarter-over-quarter drop, which Nispel said could lead to below-average growth in the third quarter of 2023. The decline is worse than the three-year historical average of 9% for the June-ending quarter.
Regardless of these potential headwinds, the KeyBanc analysts maintain their positive stance on Apple's stock. Factors contributing to this outlook include new product releases and the company's reputation as a stable investment in a volatile market. Despite softer direct channel sales and pressure on domestic iPhone sales from slowing U.S. carrier activity and lower upgrade rates, the analysts assert that Apple's status and investor sentiment will sustain its elevated stock price.
Differing Analyst Perspectives on Apple's Stock Outlook
- KeyBanc analyst Brandon Nispel maintains an Overweight rating and raises the price target from $180 to $200.
- UBS analyst David Vogt reiterates a Neutral rating and a price target of $190.
- Citigroup analyst Jim Suva initiates coverage with a Buy rating and a price target of $240.
Analyst David Vogt (UBS) has currently the highest performing score on AAPL with 24/24 (100%) price target fulfillment ratio. His price targets carry on average an $25.77 (18.23%) potential upside and are fulfilled within an average of 143 days.
Daily stock Analysts Top Price Moves Snapshot

July 12, 2023: Selected stock price target news of the day: July 12, 2023
By Matthew Otto
Salesforce to Raise Prices
Salesforce has announced that it will raise prices for some of its cloud and marketing tools by an average of 9% starting in August. This marks the company's first price increase in seven years.
The decision to raise prices comes as Salesforce and other technology companies are investing in generative artificial intelligence (AI) to enhance their products and services. Over the past seven years, Salesforce has invested over $20 billion in research and development to add new features, including generative AI tools, to its software.
At the same time, revenues from cloud services, which experienced growth during the pandemic lockdown, have started to slow down. Major cloud players like Microsoft. Amazon and Alphabet have faced pressure as enterprise clients aim to optimize their cloud spending amidst rising borrowing costs.
Analysts Maintain Positive Outlook on Salesforce
- BofA Securities analyst Brad Sills reiterates a Buy rating and a $250 price target.
- Needham maintains a Buy rating and raises their price target to $250.
- Evercore ISI Group reiterates an Outperform rating and a $240 price target.
- Piper Sandler remains on Overweight rating and a $248 price target.
Analyst Gil Luria (D.A. DAVIDSON) has currently the highest performing score on CRM with 2/2 (100%) price target fulfillment ratio. His price targets carry on average an $-1.02 (-0.20%) potential downside and typically reach target within an average of 5 days.
European Regulators Approve Broadcom's Takeover of VMware
Broadcom's $80 billion takeover of VMware has received clearance from European regulators, signaling a positive outlook for the technology sector and a potential resurgence in dealmaking. The European Commission approved the acquisition with certain conditions imposed on Broadcom. This approval suggests that tech mergers and acquisitions might face less resistance from regulators, particularly in Europe where competition watchdogs have historically been strict.
The technology industry has experienced a slowdown in dealmaking. Partly due to concerns over regulatory scrutiny and the perception that regulators are reluctant to approve tech mega-mergers. Last year, Nvidia's bid to acquire chip designer Arm was thwarted by regulators. However, with Broadcom's acquisition receiving the green light in Europe. Attention now turns to the United States, where the Federal Trade Commission is also scrutinizing the deal.
The approval of Broadcom's acquisition by European regulators and the market response indicate a shift in the landscape of tech deal activity. These developments may suggest that the technology sector may experience an increase in mergers and acquisitions, as companies waiting on the sidelines may be encouraged to pursue deal opportunities.
Analysts Maintain Positive Stance on Broadcom
- Deutsche Bank analyst Ross Seymore Maintains with a Buy rating and raises the price target from $870 to $905.
- Mizuho analyst Vijay Rakesh Reiterates Buy rating and a price target of $840.
- Wells Fargo analyst Aaron Rakers Ramins in Equal-Weight rating and raises the price target from $600 to $800.
Analyst Christopher Rolland (SUSQUEHANNA) has currently the highest performing score on AVGO with 19/20 (95%) price target fulfillment ratio. His price targets carry on average an $88.76 (24.45%) potential upside and typically reach target within an average of 213 days.
EU Fines Illumina €432 Million for Unapproved Acquisition
European Union regulators have fined Illumina a record 432 million euros ($476 million) for completing its acquisition of Grail without obtaining regulatory approval. The fine represents 10% of Illumina's turnover, the maximum allowed under EU merger rules. Illumina plans to appeal the decision and has already set aside $453 million to cover a potential maximum fine.
The European Commission accused Illumina of intentionally proceeding with the merger before obtaining regulatory clearance, known as gun-jumping. Grail was also fined a symbolic amount by the European Commission. This marks the first time the commission has imposed a fine on the target of an acquisition. Illumina believes that the acquisition will benefit its shareholders and save lives. The European Commission blocked the deal over concerns about innovation and consumer choice in the cancer detection test market.
Illumina has appealed the European Commission's decision, arguing that the agency lacks jurisdiction to block the merger. A final decision on the appeal is expected in late 2023 or early 2024. If Illumina loses the appeal, the company has stated that it will divest Grail.
Analysts Reiterate confidence in Illumina
- Canaccord Genuity analyst Kyle Mikson reiterates Buy rating and a price target of $300.
- Piper Sandler analyst David Westenberg maintains Buy rating and sets a price target of $290.
Analyst Tycho Peterson (JPMORGAN) has currently the highest performing score on ILMN with 5/6 (83.33%) price target fulfillment ratio. His price targets carry on an average of $33.76 (14.13%) potential upside and typically reach target within an average of 113 days.
Daily stock Analysts Top Price Moves Snapshot
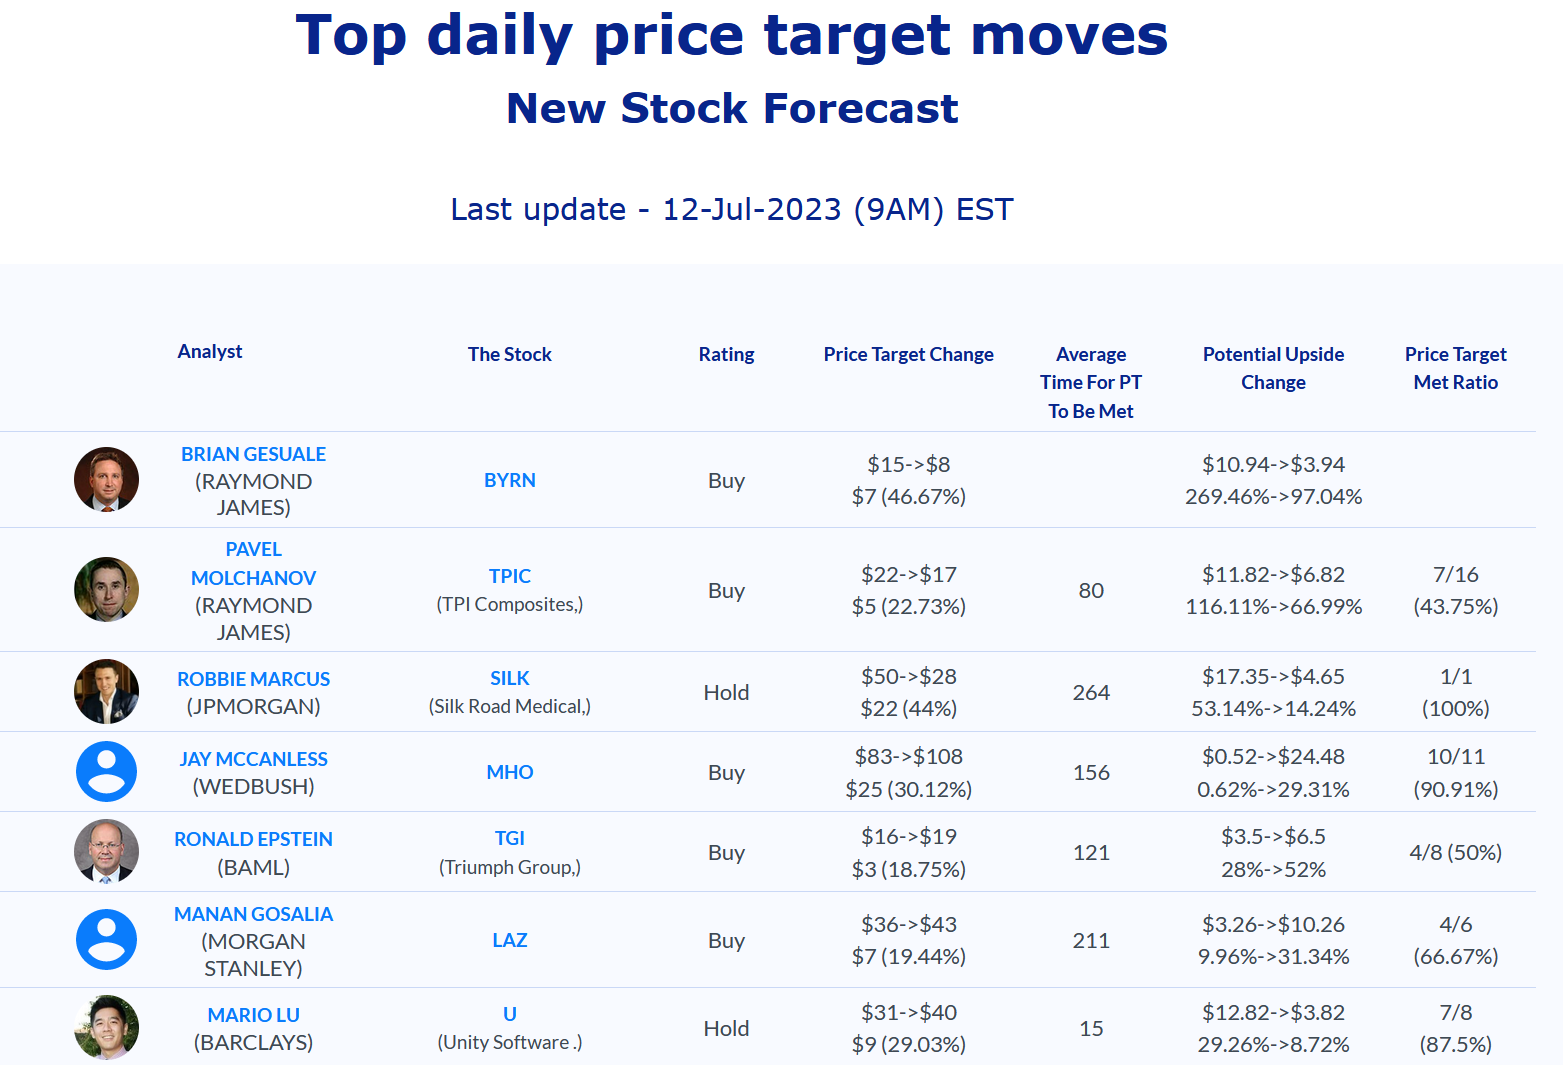
July 13, 2023: Selected stock price target news of the day: July 13, 2023
By Matthew Otto
Domino's Pizza Partners with Uber to Expand Delivery Services
Domino's Pizza announced a partnership with Uber's Uber Eats and Postmates apps. The agreement makes Uber Eats the exclusive third-party platform for Domino's in the United States until at least 2024. Domino's will retain control over its brand and food quality by using its own drivers for deliveries, while also benefiting from the expanded reach offered by Uber's platforms.
By joining Uber Eats and Postmates, Domino's aims to reach new customers accustomed to ordering through these popular delivery apps. This move represents a shift for Domino's, which previously relied on its own app, website, and drivers for deliveries.
The agreement also includes plans for Domino's to transition to Uber Eats for deliveries in 27 international markets, including the United Kingdom, Canada, and Australia. This expansion into international markets aligns with the existing presence and operations of both Domino's and Uber in these countries.
Analysts Offer Mixed Ratings and Adjust Price Targets for Domino's Pizza
- Wells Fargo analyst Zachary Fadem maintained an Equal-Weight rating and price target raised from $310 to $375.
- Baird analyst David Tarantino reiterated a Neutral rating and price target raised from $320 to $360.
- Northcoast Research analyst Jim Sanderson Upgrades from Neutral to Buy and announces a $430 price target.
- Citigroup analyst Jon Tower remained a Neutral rating while price target raised from $349 to $405.
- TD Cowen analyst Andrew Charles reiterated a Market Perform rating and a $330 price target.
- Stephens & Co. analyst Joshua Long maintained an Equal-Weight rating and a $300 price target.
- Loop Capital analyst Alton Stump remained a Hold rating while price target raised from $320 to $343.
Analyst Chris O'cull (STIFEL) currently has the highest performing score on DPZ with 16/16 (100%) price target fulfillment ratio. His price targets carry on an average of $25.62 (10.55%) potential upside and are fulfilled within an average of 97 days.
Delta Air Lines Achieves Record-Breaking Quarterly Revenue
Delta Air Lines posted its highest-ever quarterly revenue and earnings in the second quarter, driven by strong travel demand and lower fuel costs. International travel and premium seat bookings, such as first class, performed exceptionally well during this period. The company raised its 2023 earnings forecast, reflecting its confidence in sustained travel growth. Delta's CEO, Ed Bastian, expects consumer travel enthusiasm to continue driving bookings for years to come, referring to the current period as the "mid-innings" of travel growth.
Delta anticipates a slow but steady increase in corporate travel bookings and robust international demand in the coming months. The company reported a 22% decrease in fuel costs, which significantly contributed to its strong financial results. Delta's net income for the quarter reached $1.83 billion, the highest since 2013. Adjusted revenue for the three-month period ending June 30 was $14.61 billion, representing a 19% increase from the previous year. These figures surpassed analysts' expectations and highlighted the airline's resilience amidst the recovering travel industry.
Delta Air Lines Upgraded by Analysts with Higher Price Targets
- Barclays analyst Brandon Oglenski maintains an Overweight rating and raises the price target from $55 to $58.
- Susquehanna analyst Christopher Stathoulopoulos reiterates a Positive rating and raises the price target from $54 to $60.
- Jefferies analyst Sheila Kahyaoglu remains on Buy rating and raises the price target from $50 to $60.
Analyst Andrew Didora (BAML) has currently the highest performing score on DAL with 12/13 (92.31%) price target fulfillment ratio. His price targets carry on an average of $6.29 (15.05%) potential upside and are fulfilled within an average of 297 days.
ExxonMobil to Acquire Denbury in $4.9 Billion Deal
Exxon Mobil has announced its acquisition of carbon capture developer Denbury in a deal valued at $4.9 billion. The acquisition will give Exxon ownership of the largest carbon dioxide pipeline network in the United States. The move is part of Exxon's strategy to expand its Low Carbon Solutions business and offer comprehensive carbon capture and sequestration solutions to industries that are difficult to decarbonize. The acquisition has been approved by the boards of directors of both companies and is expected to close in the fourth quarter of the year, pending regulatory approval.
Denbury investors will receive 0.84 shares of Exxon Mobil for each share of Denbury they own. Denbury's CEO, Chris Kendall, believes that ExxonMobil is the ideal partner due to its extensive resources and capabilities required for the development of the carbon capture business.
Analysts Adjust Price Targets for Exxon Mobil
- Wolfe Research analyst Sam Margolin downgraded from Outperform to Peer Perform.
- UBS analyst Josh Silverstein maintains a Buy rating and lowered the price target to $137 from $139.
- Citigroup analyst Alastair Syme reiterates with a Neutral rating and a $110 price target.
Analyst Jon Rigby (UBS) has currently the highest performing score on XOM with
3/4 (75%) price target fulfillment ratio. His price targets carry on average an$13.1 (16.10%) potential upside and are fulfilled within an average of 571 days.
Daily stock Analysts Top Price Moves Snapshot

July 14, 2023: Selected stock price target news of the day: July 14, 2023
By Matthew Otto
Alcoa Faces Downgrades Amid Concerns Over Falling Commodity Prices
J.P. However, morgan analyst Bill Peterson downgraded Alcoa from Buy to Hold. A lowered price target of $36 per share compared to the previous target of $54. About 47% of analysts still rating the stock as Buy, but the average analyst price target has dropped.
Peterson expressed caution about the near-term outlook for aluminum base metal due to planned restarts in China and a seasonal demand lull. So, as China accounts for nearly 60% of global aluminum production, any changes in output have an impact on aluminum prices worldwide. About 47% of analysts still rating the stock as Buy, but the average analyst price target has dropped.
Falling commodity prices have been a concern for the company. Benchmark aluminum prices declining approximately 10% over the past year and about 20% from January highs.
Analysts Issue Mixed Ratings for Alcoa Stock
- JP Morgan analyst Bill Peterson downgrades from Overweight to Neutral and the price target from $54 to $36.
- Morgan Stanley analyst Carlos De Alba maintains an Underweight rating and the price target at $33.
- Wolfe Research analyst Timna Tanners downgrades from Peer Perform to Underperform and sets a price target of $25.
- Goldman Sachs analyst Emily Chieng keeps a Buy rating on Alcoa but lowers the price target from $54 to $46.
Analyst Alexander Hacking (CITI) currently has the highest performing score on AA with 18/20 (90%) price target fulfillment ratio. His price targets carry an average $9.29 (22.44%) potential upside and typically reach target within an average of 256 days.
Leslie's Reports Preliminary Q3 2023 Results and Revises Fiscal Year Outlook
Leslie's announced preliminary financial results for the third quarter of Fiscal 2023. Sales for the quarter are expected to be $611 million, with a comparable sales decline of 12%. Gross profit is projected to be $249 to $251 million, and gross margin is expected to be around 41%. Net income is estimated to be $70 to $73 million. Adjusted EBITDA is anticipated to be $124 to $128 million. The company's CEO, Mike Egeck. Acknowledged that the third-quarter results were below expectations due to traffic declines and increased consumer price sensitivity.
The company's fiscal third-quarter earnings were $0.68 per share, missing the analyst estimate of $0.74. Revenue for the quarter came in at $673.6 million, below the consensus estimate of $696.45 million.
The company is revising its Fiscal 2023 outlook based on the third-quarter results. Net sales for the fiscal year are now expected to be $1,430 to $1. 450 million or $0.90 and $0.96 per share, lower than the consensus of $1.06. Down from the previous guidance of $1.02 to $1.10 per share. Gross profit projected to be $549 to $559 million.
Net income is expected to range from $33 to $40 million. Adjusted EBITDA is projected to be $170 to $180 million. The adjusted net income is anticipated to be $52 to $59 million. Adjusted diluted earnings per share are expected to be $0.28 to $0.32.
Higher product costs, increased distribution-related expenses, and fixed-cost deleverage affected the company's gross margins.
Analysts Downgrade Leslie's and Lower Price Targets
- The William Blair analyst Ryan Merkel has downgraded from Outperform to Market Perform.
- Meanwhile, Guggenheim Steven Forbes has lowered the rating from Buy to Neutral.
- Telsey Advisory Dana Telsey maintains a Market Perform rating but has lowered the price target from $11 to $8.5.
- Piper Sandler Peter Keith has downgraded from Overweight to Neutral and has lowered the price target from $16 to $7.
Analyst Garik Shmois (LOOP CAPITAL) currently has the highest performing score on LESL with 6/9 (66.67%) price target fulfillment ratio. His price targets carry an average $3.51 (18.22%) potential upside and the stock reaches them within an average of 14 days.
Acadia Expands Licensing Agreement with Neuren for Trofinetide and NNZ-2591
Acadia Pharmaceuticals has expanded its licensing agreement with Neuren Pharmaceuticals, granting Acadia ex-North American rights to trofinetide and global rights to Neuren's developmental candidate NNZ-2591 for Rett syndrome and Fragile X syndrome for an upfront payment of $100 million. This move strengthens Acadia's position by addressing the unmet needs of individuals with Rett syndrome.
Trofinetide, launched by Acadia as DAYBUE. Is the first FDA-approved treatment for Rett syndrome.Fragile X syndrome (FXS) affects both males and females. An estimated prevalence of approximately 1 in 7,000 males and 1 in 11,000 females diagnosed with FXS. Intelligence quotient (IQ) scores decline with age, with adolescents and adults consistently scoring lower on IQ tests than young children. Boys with FXS have an average IQ score under 55. Significantly lower than the general population's average IQ score of 100. The average age of FXS diagnosis is around 35 to 37 months for boys and 42 months for girls.
Analysts Maintain ACADIA Ratings and Raise Price Targets
- JMP Securities analyst Jason Butler maintains a Market Outperform rating and raises the price target from $31 to $39.
- Oppenheimer analyst Jay Olson remains in a Perform rating and raises the price target from $20 to $23.
- HC Wainwright analyst Andrew Fein reiterates a Buy rating and raises the price target from $28 to $33.
- Morgan Stanley analyst Jeffrey Hung maintains an Equal-Weight rating and raises the price target from $20 to $21.
Analyst Jay Olson (OPPENHEIMER) currently has the highest performing score on ACAD with 8/9 (88.89%) price target fulfillment ratio. His price targets carry an average $1.09 (6.20%) potential upside and are the stock reaches them within an average of 39 days.
Daily stock Analysts Top Price Moves Snapshot
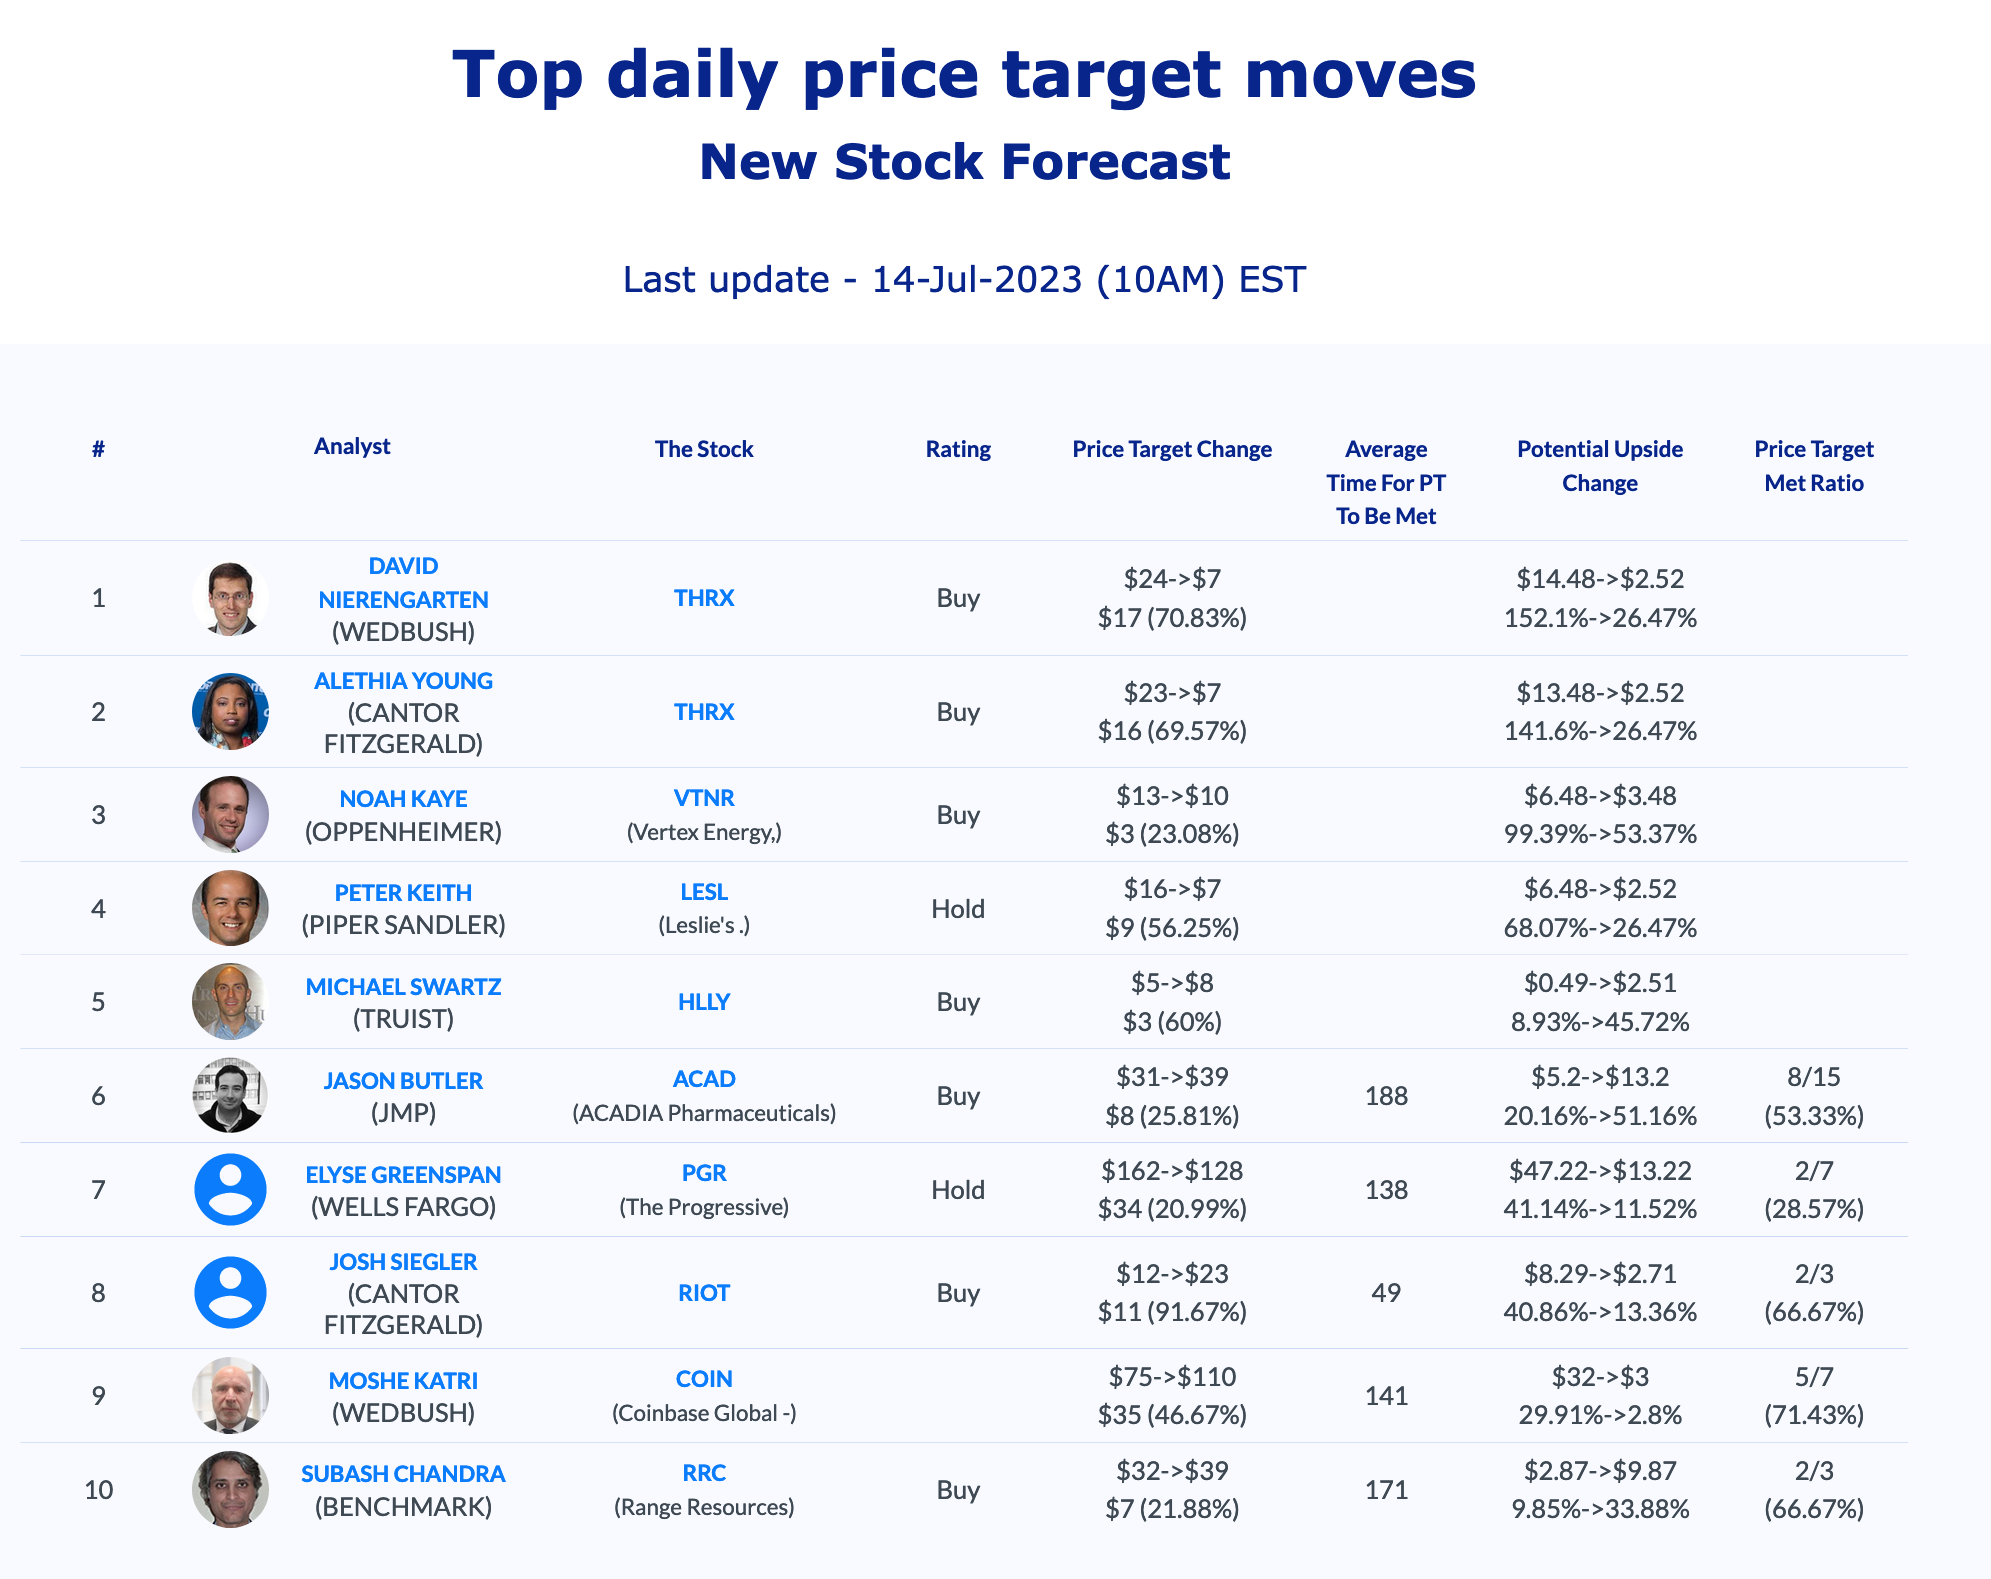
July 17, 2023: Selected stock price target news of the day: July 17, 2023
By Matthew Otto
Progressive Faces Challenges as Expenses Rise and Growth Slows
Progressive is facing challenges that have impacted its performance. Higher expenses and slowing growth have led to a downgrade by Wells Fargo analyst Elyse Greenspan. The total number of automotive policies in force at the end of June showed a slight decline compared to May, and the company's underwriting profits have been shrinking. The combined ratio, which measures underwriting and corporate expenses against revenue, was unfavorable in June at 104.9%, indicating that insurance underwriting was losing money. These disappointing results and the anticipated normalization of insurance expenses have led to a hold rating on the stock.
The increasing costs of paying auto claims have also contributed to Progressive's challenges. The rising value of new and used cars in recent years has resulted in higher repair costs and more expensive auto insurance claims. Although the Manheim Used Vehicle Value Index showed a slight year-over-year decline in June, prices are still higher than pre-pandemic levels.
Progressive Receives Mixed Analyst Ratings and Lowered Price Targets
- Wells Fargo analyst Elyse Greenspan downgrades to Equal-Weight and her price target from $162 to $128.
- Raymond James analyst C. Gregory Peters maintains an Outperform rating but lowers his price target from $145 to $140.
- Citigroup analyst Michael Ward reiterates a Sell rating and lowers the price target from $123 to $106.
- Barclays analyst Tracy Benguigui remains with an Underweight rating and drops his price target from $120 to $103.
Analyst Meyer Shields (STIFEL) currently has the highest performing score on PGR with 14/16 (87.5%) price target fulfillment ratio. His price targets carry an average of $1.82 (10.10%) potential upside. Progressive stock price reaches these price targets on average within 160 days.
Chipotle Tests Robot to Revolutionize Food Preparation
Chipotle Mexican Grill is testing a new collaborative robot prototype called Autocado, designed to cut, core, and peel avocados for guacamole preparation. The robot, developed by Vebu, aims to significantly reduce the time it takes to make a batch of guacamole. Currently, it takes approximately 50 minutes, but Autocado has the potential to cut that time in half. Chipotle is also exploring the development of a robotic tortilla-chip maker named Chippy, which fries and seasons chips. The company has a history of embracing fast-food technology, including launching an order-ahead app.
Chipotle is not alone in experimenting with robotics in the fast-food industry. White Castle has been testing a robot that operates a frying station, McDonald's has unveiled an automated test restaurant with robots serving customers at the drive-through, and Starbucks introduced the Siren System to reduce drink-making time.
However, developing and implementing these robotic technologies is a complex process. While Chippy has been integrated into one store for testing, Chipotle's robotic initiatives are still underway.
Analysts Bullish on Chipotle Mexican Grill, Raise Price Targets
- Oppenheimer analyst Brian Bittner maintains an Outperform rating and increase the price target from $2050 to $2350.
- Stephens & Co. analyst Joshua Long reiterates an Overweight rating and raises the price target from $2280 to $2400.
- Morgan Stanley analyst Brian Harbour raises the price target to $2025.
- Guggenheim analyst Gregory Francfort increases the price target from $1550 to $1950.
- Citi analyst Gregory Badishkanian raises the price target to $2454.
Analyst Nick Setyan (WEDBUSH) currently has the highest performing score on CMG with 41/45 (91.11%) price target fulfillment ratio. His price targets carry an average of $67.1 (4.98%) potential upside. Chipotle Mexican Grill stock price reaches these price targets on average within 122 days
Ford Cuts Prices for Electric F-150 Lightning Pickup Amid Increased Production
Ford Motor has announced price cuts for its electric F-150 Lightning pickup truck. The company has reduced prices for some of the lower-priced versions of the Lightning by nearly $10,000, while prices for all versions, including the top-line Platinum trim, will decrease by at least $6,000 compared to the levels set in March. Ford had previously raised prices for the Lightning due to supply constraints and higher prices for battery minerals. The production upgrades at the Dearborn factory, where the Lightning is manufactured, will result in a temporary closure of the facility for several weeks.
Ford's CEO, Jim Farley, has made the production of Lightning and other electric vehicles a priority. However, the company faced challenges in this endeavor, including a production shutdown of five weeks following a fire incident in a completed truck in February. The initial lowest price for the Lightning was around $40,000, but it had been raised multiple times, reaching about $60,000 in March. With the latest price cuts, the entry-level truck's sticker price will be around $50,000, while the extended-range Platinum trim will start at approximately $92,000, down from over $98,000.
Analysts Maintain and Adjust Price Targets for Ford Motor Stock
- Wells Fargo analyst Colin Langan maintains with an Underweight rating and raised the price target from $10 to $11.
- Barclays analyst Dan Levy reiterates an Equal-Weight rating and increased the price target from $13 to $14.
- Citigroup analyst Itay Michaeli remains with a Buy rating while increasing the price target from $16 to $17.
Analyst Jairam Nathan (DAIWA) currently has the highest performing score on F with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $1.48 (15.20%) potential upside. Ford Motor stock price reaches these price targets on average within 538 days
Daily stock Analysts Top Price Moves Snapshot
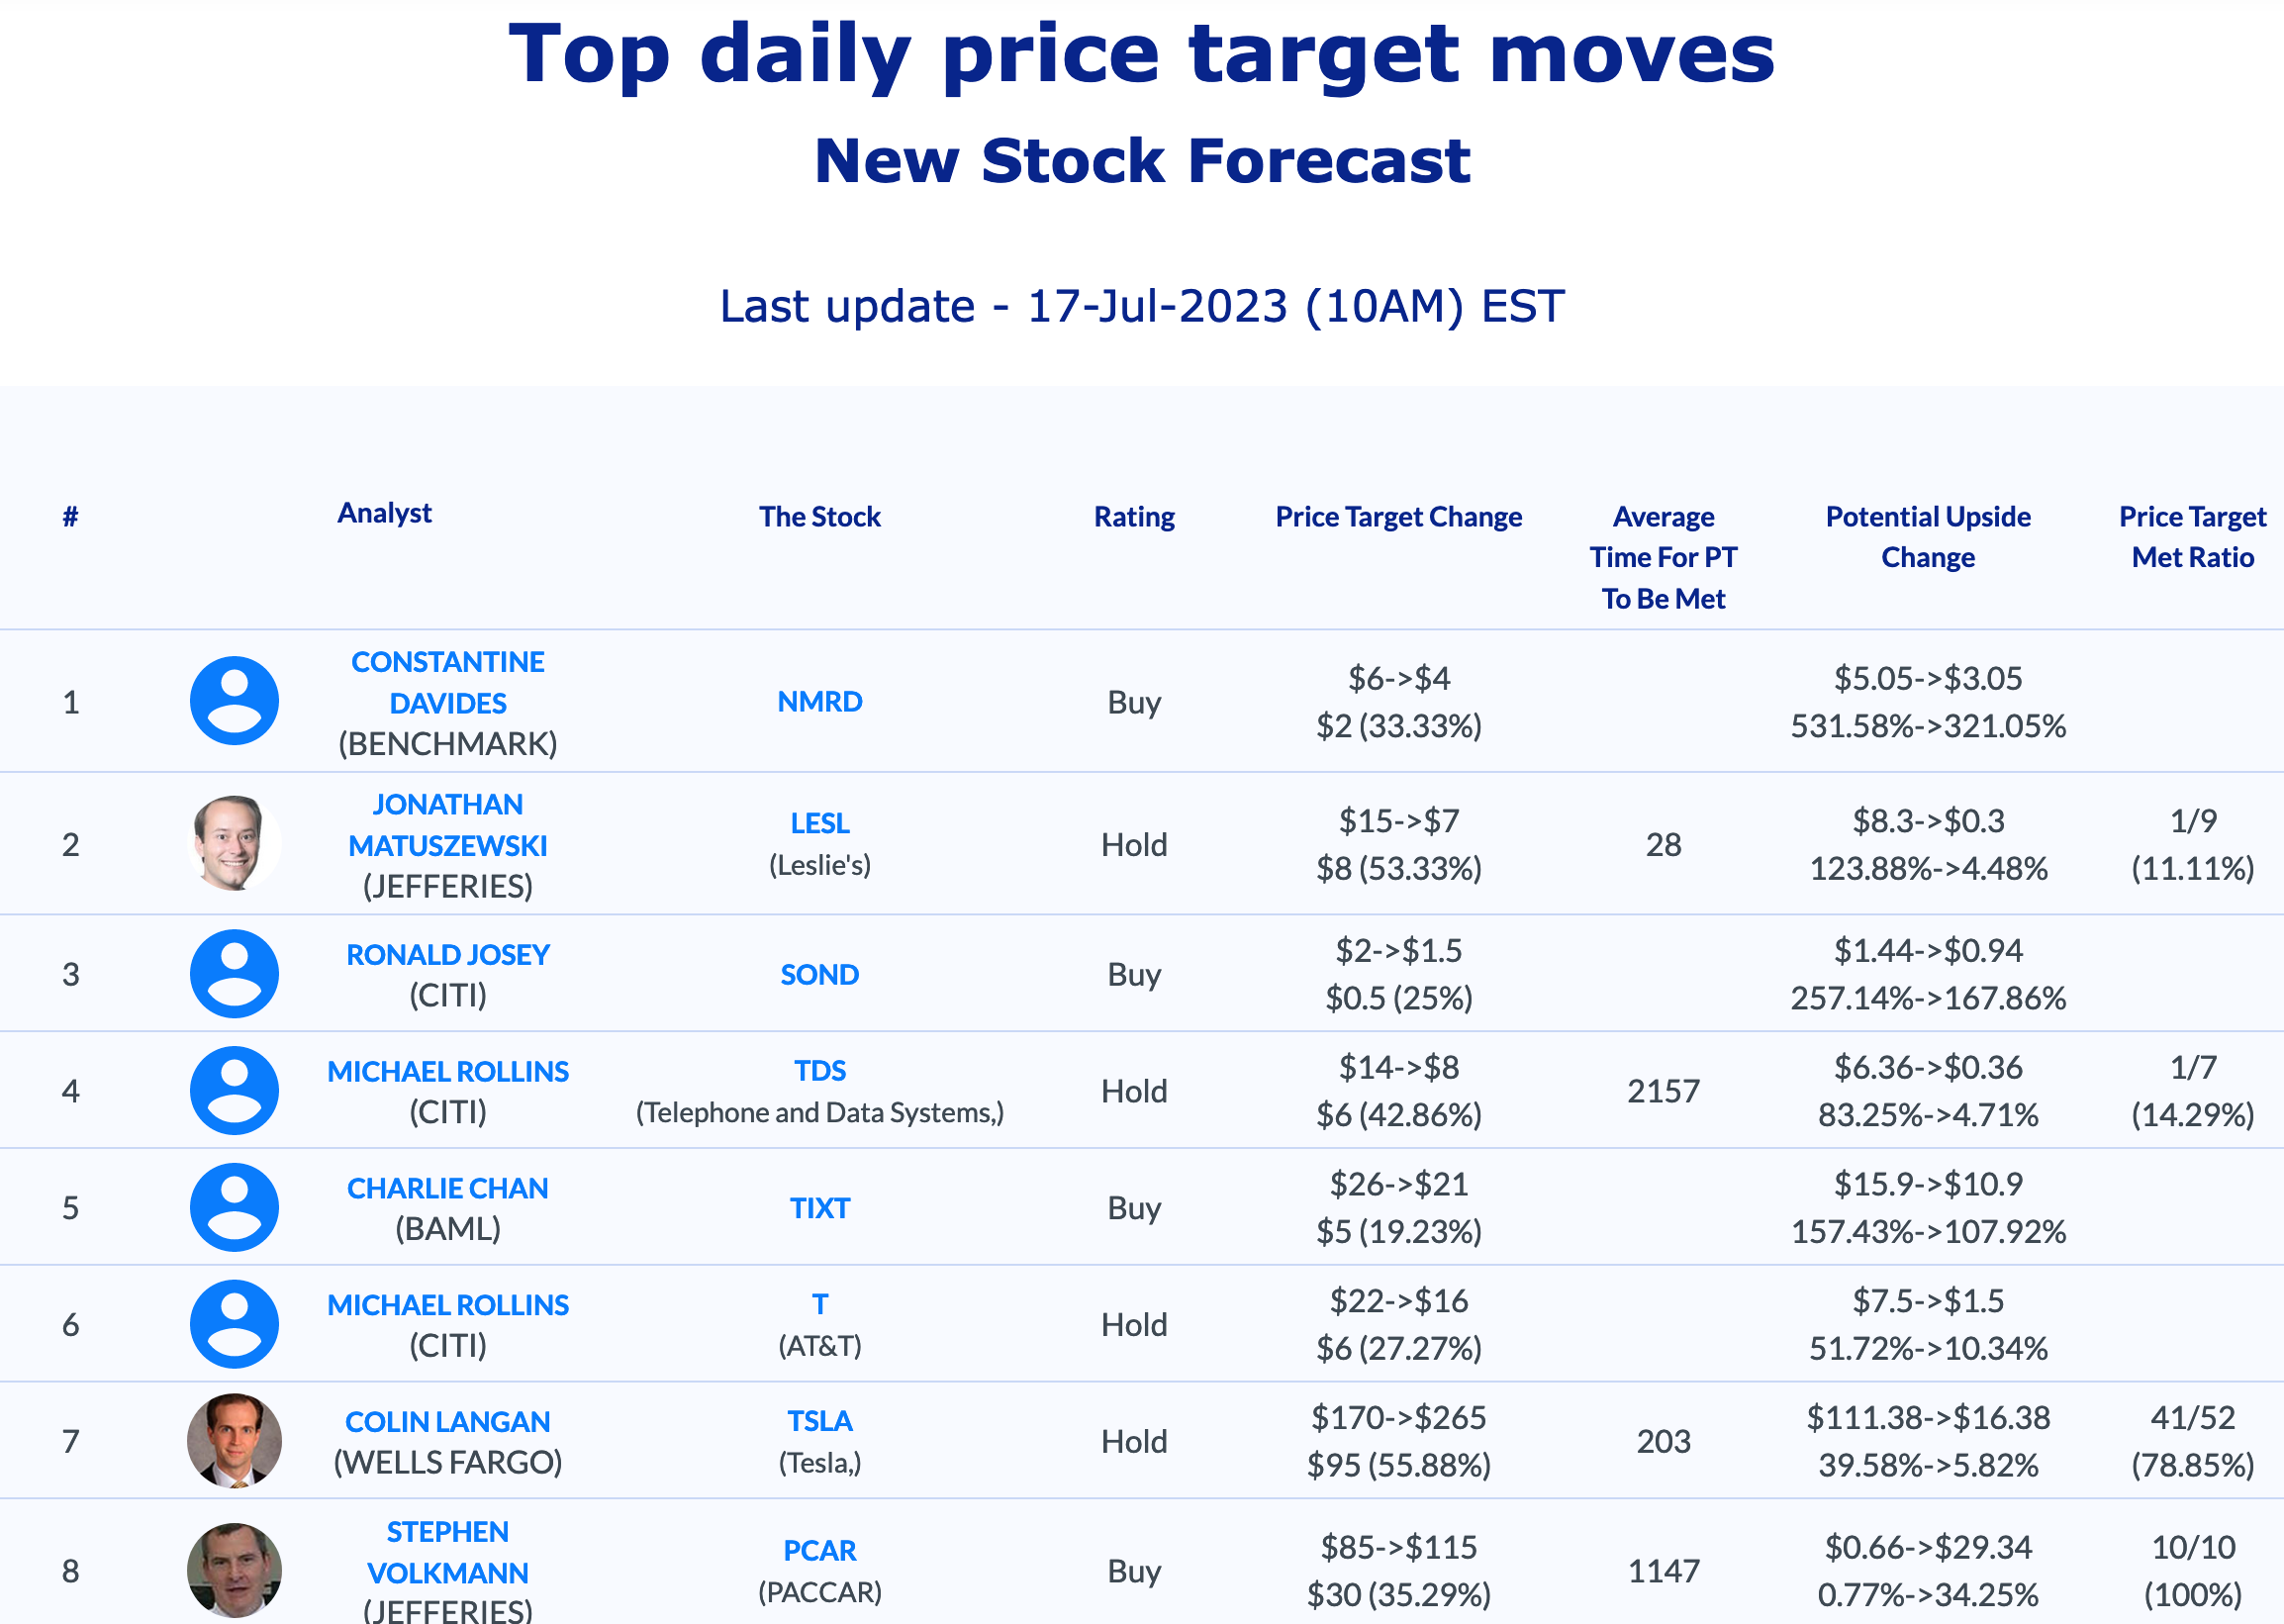
July 18, 2023: Selected stock price target news of the day: July 18, 2023
By Matthew Otto
Bank of America's Bond Portfolio Losses Highlighted Ahead of Q2 Earnings
Bank of America is expected to release its second-quarter earnings report. One key figure likely hidden in the financial supplement: the size of the loss on its significant bond portfolio. The held-to-maturity securities, consisting mainly of mortgage securities. Suffered a $99 billion loss on a $625 billion Bond portfolio as a result of the drop in the bond market since their purchase at historically low interest rates in 2020 and 2021. This loss is higher than those experienced by Bank of America's peers, such as JPMorgan Chase and Wells Fargo.
Although banks are not required to reflect losses on held-to-maturity securities in their capital positions. The economic losses incurred by Bank of America are significant and represent a portion of its tangible equity. While the bank believes that the held-to-maturity portfolio will eventually recover as the securities mature. The average yield of the portfolio is currently 2.6%, half the current market rate. This could potentially impact the bank's net interest margins as deposit costs rise.
Analyst Mixed Ratings and Revised Price Targets for Bank of America
- Morgan Stanley analyst Betsy Graseck maintains an Equal-Weight rating and raises her price target from $32 to $33.
- RBC Capital analyst Gerard Cassidy reiterates an Outperform rating and a $35 price target.
Analyst Gerard Cassidy (RBC) currently has the highest performing score on BAC with 14/20 (70%) price target fulfillment ratio. His price targets carry an average of $5.12 (31.67%) potential upside. Bank of America stock price reaches these price targets on average within 888 days.
Morgan Stanley's Strong Q2 Earnings Fueled by Record Wealth Management Results
Morgan Stanley reported second-quarter earnings and revenue that exceeded analysts' expectations. Earnings per share were $1.24, higher than the estimated $1.15 per share. The company's revenue reached $13.46 billion, surpassing the expected $13.08 billion. Despite a 13% decline in profit compared to the previous year. The bank's steady focus on wealth management has helped maintain its earnings and boosted its valuation relative to peers.
Morgan Stanley's wealth management division performed well in the second quarter, with revenue rising by 16% to $6.66 billion. This growth was primarily driven by higher interest income and the division attracted $90 billion in net new client assets, exceeding estimates. However, the bank's Wall Street division, specifically the institutional securities business, experienced an 8% decline in revenue to $5.65 billion due to decreases in trading activity. Equities trading generated $2.55 billion in revenue, surpassing estimates, while fixed income revenue amounted to $1.72 billion, falling short of expectations.
Mixed Analyst Recommendations for Morgan Stanley as Price Targets are Adjusted
- Odeon Capital analyst Dick Bove upgrades from Hold to Buy and sets a $94 price target.
- JP Morgan analyst Kian Abouhossein maintains an Overweight rating but lowers the price target from $97 to $91.
- Citigroup analyst Keith Horowitz reiterates with a Neutral rating and reduces the price target from $95 to $90.
Analyst Whit Mayo (LEERINK) currently has the highest performing score on MS with 2/2 (100%) price target fulfillment ratio. His price targets carry an average of $4.55 (5.47%) potential upside. Morgan Stanley stock price reaches these price targets on average within 145 days
Goldman Sachs Revises Down Odds of U.S. Recession, Cites Positive Economic Activity
Goldman Sachs has revised the probability of a U.S. recession in the next 12 months to 20% from 25% due to positive economic activity and better-than-expected economic data. The chief economist, Jan Hatzius. Mentioned that recent data have reinforced their confidence that a recession is not necessary to bring down inflation to an acceptable level. Factors such as resilient U.S. economic activity, a rebound in consumer sentiment, and a decrease in unemployment levels contribute to Goldman Sachs' optimism.
The U.S. economy expanded at a rate of 2.3% in the second quarter. Initial jobless claims fell to 239,000 for the week ending June 24, surpassing estimates. June's core inflation, excluding food and energy. Rose at the slowest pace since February 2021, indicating a potential easing of consumer price rises. While there may be some deceleration in subsequent quarters due to slower real disposable personal income growth. Goldman Sachs believes that the U.S. economy will continue to grow, albeit at a below-trend pace. Supported by factors such as favorable financial conditions, a rebounding housing market, and ongoing growth in factory building.
Despite expecting a 25 basis point hike from the Federal Reserve's upcoming meeting. Goldman Sachs' chief economist suggests it could mark the end of the current cycle of interest rate increases.
Analysts Provide Mixed Recommendations for Goldman Sachs Group
- Odeon Capital analyst Dick Bove upgrades from Hold to Buy with a $355.75 price target.
- Societe Generale analyst Andrew Lim downgrades from Buy to Hold.
- JMP Securities analyst Devin Ryan maintains a Market Outperform rating and lowers the price target from $470 to $450.
- JP Morgan analyst Kian Abouhossein reiterates an Overweight rating and lowers the price target from $415 to $398.
Analyst Betsy Graseck (MORGAN STANLEY) currently has the highest performing score on GS with 6/11 (54.55%) price target fulfillment ratio. Her price targets carry an average of $39.19 (11.81%) potential upside. Goldman Sachs stock price reaches these price targets on average within 35 days
Daily stock Analysts Top Price Moves Snapshot
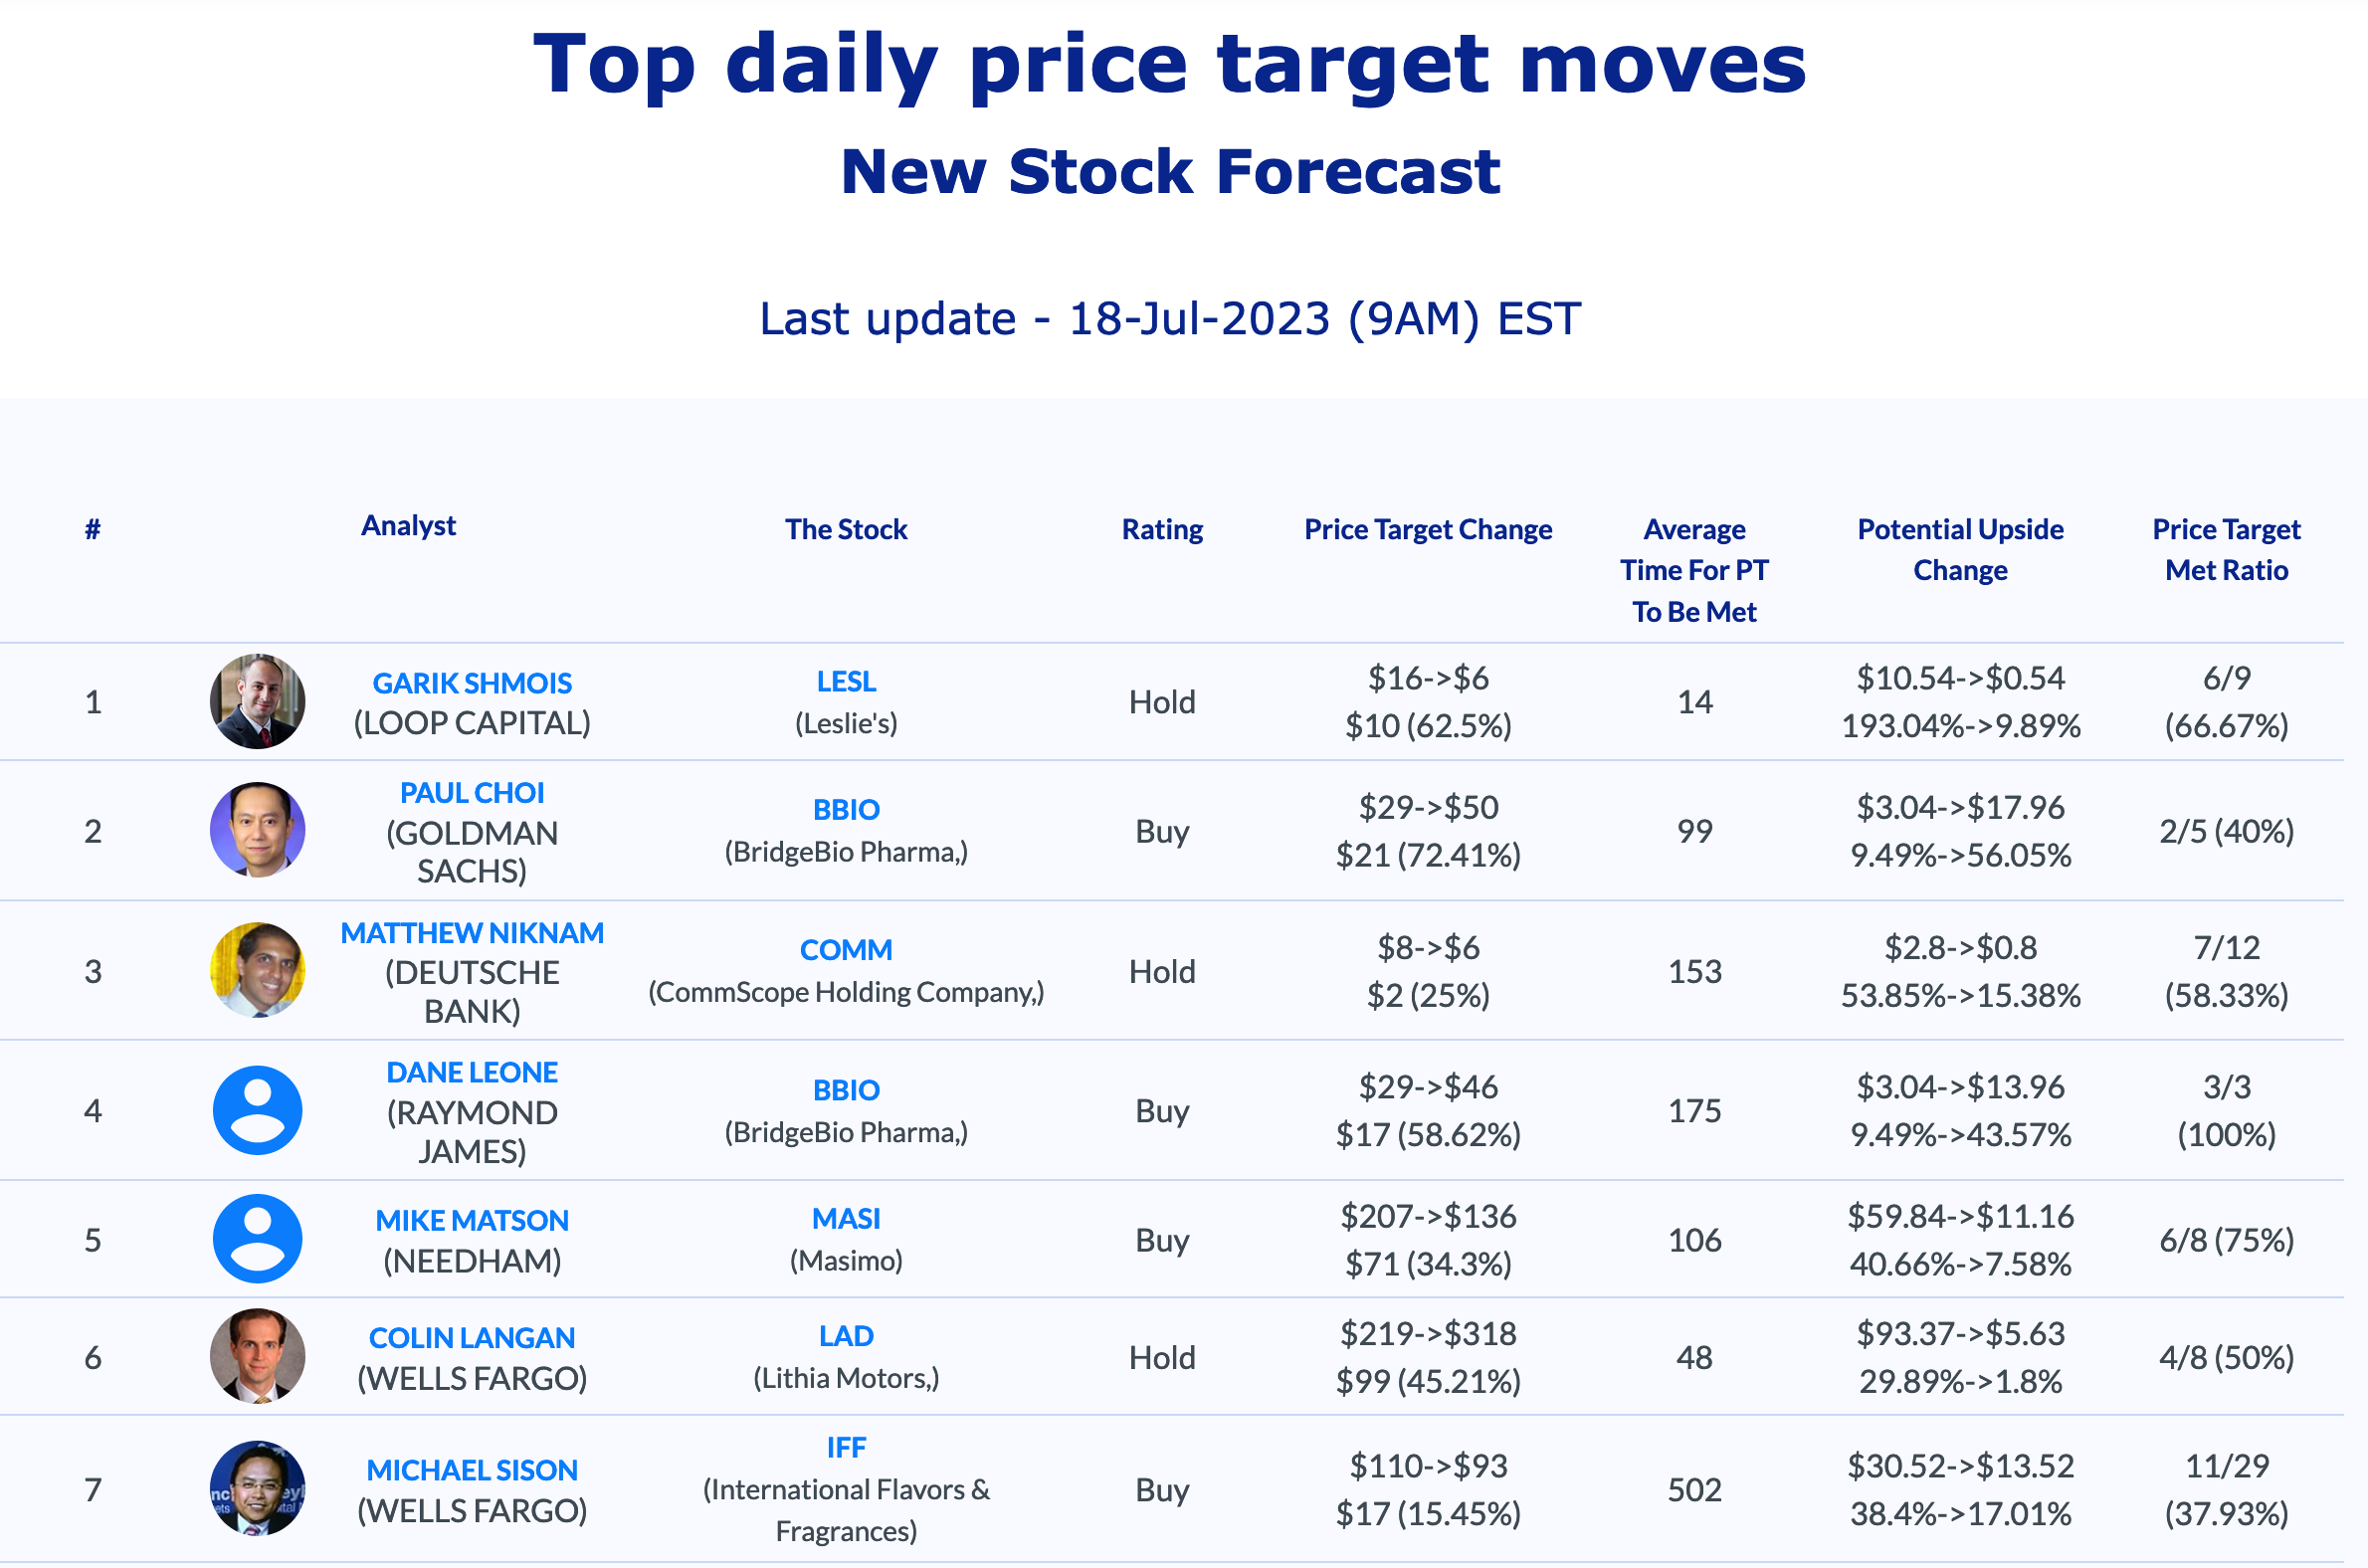
July 19, 2023: Selected stock price target news of the day: July 19, 2023
By Matthew Otto
Carvana Reports an Improvement in Quarterly Profit and Debt Restructuring
The second quarter proved to be a milestone for Carvana, with adjusted EBITDA reaching $155 million and profit per unit at $6,520. The company reported revenue of $2.97 billion for the quarter, surpassing expectations of $2.6 billion. Carvana also disclosed an agreement with bondholders to reduce its outstanding debt by over $1.2 billion, which led to a change in its earnings date.
The debt restructuring deal is expected to eliminate a portion of Carvana's unsecured note maturities and reduce its required cash interest expense by $430 million annually for the next two years.
Mixed Analyst Recommendations for Carvana
- JP Morgan analyst Rajat Gupta downgrades from Neutral to Underweight and set a price target of $10. The analyst expressed a view that Carvana's valuation has exceeded what can be justified by recent improvements in the company's business.
- JMP Securities analyst Nicholas Jones maintains an Outperform rating and raises the price target from $25 to $50.
- Piper Sandler analyst Alexander Potter reiterates an Overweight rating and raises the price target from $21 to $29.
Analyst Michael Baker (D.A. DAVIDSON) currently has the highest performing score on CVNA with 6/7 (85.71%) price target fulfillment ratio. His price targets carry an average of
$8.96 (1.14%) potential upside. Carvana stock price reaches these price targets on average within 20 days.
Charles Schwab Reports Better-Than-Expected Q2 Profit
Charles Schwab reported second-quarter profit that was lower than expected but still better than anticipated. Despite a decline in interest revenue, Schwab saw a boost in asset management fees, which helped offset the impact. Schwab relies on clients' uninvested cash for its interest-earning businesses, but some clients have been moving their cash to alternatives that offer better returns in the current high-interest rate environment.
To counter the outflows of cash, Schwab has turned to supplementary funding sources, including borrowing from the Federal Home Loan Bank, which has resulted in more expensive funding. As a result, net interest revenue for the company declined by 10% to $2.29 billion in the second quarter. The company expects the realignment activity to improve before the end of 2023. Schwab saw a 12% increase in asset management and administration fees, reaching $1.17 billion, driven by inflows into the company's funds.
Charles Schwab's second-quarter profit, excluding one-time costs, fell by 25% to $1.49 billion, or 75 cents per share. However, this surpassed analysts' expectations of 71 cents per share. The earnings report comes during a week when investors are closely monitoring the results of banks and financial institutions, looking for any lingering effects from the banking crisis earlier this year.
Analysts Raise Price Targets for Charles Schwab Amid Positive Outlook
- Citigroup analyst Christopher Allen maintains a Buy rating and raises the price target from $65 to $75.
- JMP Securities analyst Devin Ryan reiterates Outperform rating and raises the price target from $73 to $77.
- Barclays analyst Benjamin Budish stands on an Equal-Weight rating and raises the price target from $62 to $70.
- Raymond James analyst Patrick O'Shaughnessy remains on Outperform rating and raises the price target from $64 to $77.
Analyst Steven Chubak (WOLFE) currently has the highest performing score on SCHW with 10/11 (90.91%) price target fulfillment ratio. His price targets carry an average of $3.64 (8.65%) potential upside. Charles Schwab stock price reaches these price targets on average within 160 days
Microsoft Stock Reaches All-Time High as Pricing Strategy for AI Software Is Announced
Microsoft announced the pricing strategy for its Microsoft 365 Copilot software, which adds generative artificial intelligence capabilities to its flagship software suite. The software will be offered to business customers at a rate of $30 per user per month.
Bernstein analyst Mark Moerdler noted that the pricing for 365 Copilot exceeded his expectations and represented a price increase ranging from 53% to 240%, depending on the version of Microsoft 365 being used. The focus on Microsoft 365 instead of Office 365 suggests a strategic move to drive new subscriptions and shift users to the higher-priced Microsoft 365.
Microsoft also unveiled Bing Chat Enterprise, a standalone chatbot app for business customers priced at $5 per user per month. Analysts, such as Wedbush's Dan Ives and Citi's Tyler Radke, viewed the pricing announcement positively, with Ives believing it could boost Microsoft's annual cloud revenue by 20% by 2025. Radke, although the general availability is expected to be months away, considered the news to be incrementally positive.
Analysts Raise Price Targets and Maintain Positive Ratings for Microsoft
- Wells Fargo analyst Michael Turrin maintains an Overweight rating and raises his price target from $380 to $400.
- Barclays analyst Raimo Lenschow remains an Overweight rating and raises his price target from $336 to $425.
- Piper Sandler analyst Brent Bracelin reiterates an Overweight rating and a $400 price target.
- Wedbush analyst Daniel Ives maintains an Outperform rating and a $375 price target.
- Keybanc analyst Michael Turits reiterates an Overweight rating and raises his price target from $340 to $400.
.
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on MSFT with 25/25 (100%) price target fulfillment ratio. His price targets carry an average of $18.45 (12.49%) potential upside. Microsoft stock price reaches these price targets on average within 119 days
Daily stock Analysts Top Price Moves Snapshot

July 20, 2023: Selected stock price target news of the day: July 20, 2023
By Matthew Otto
Netflix Misses on Q2 Revenue
Netflix disappointed Wall Street in the second quarter as its revenue fell short of analyst estimates. Despite exceeding earnings predictions and adding 5.9 million new streaming customers which surpassed Wall Street's prediction of 1.9 million. (By the end of June, the global subscriber count for Netflix stood at 238.4 million).
Revenue for the quarter witnessed a 2.7% rise from the same period last year, reaching $8.2 billion. Although it fell slightly short of the predicted $8.3 billion by analysts. The company forecasts that the revenue for the upcoming third quarter will reach $8.5 billion. Wall Street's estimate was slightly higher at $8.7 billion.
The firm announced earnings-per-share of $3.29, diluted for Q2, exceeding the anticipated $2.86 as predicted by analysts polled by Refinitiv.
Netflix's efforts to find new revenue streams and combat streaming competition through the introduction of an ad-supported tier and a crackdown on password sharing have been ongoing. However, as Netflix approaches market saturation in the United States, it faces challenges in maintaining its growth trajectory.
While the addition of nearly 6 million subscribers outpaced expectations. Average revenue per member declined by 3% due to the influx of sign-ups from countries with lower subscription prices. Netflix's revenue growth projections for the third quarter also fell below Wall Street's estimates. The ongoing strike by Hollywood actors and writers, which has disrupted film and television productions industry-wide, has affected Netflix as well. However, the company is still raising its 2023 free cash flow estimate to $5 billion and expressing hope for a resolution to the labor tensions.
Mixed Analyst Views on Netflix as Price Targets and Ratings Differ
- Credit Suisse analyst Douglas Mitchelson reiterates a Neutral rating and a $370 price target.
- BofA Securities analyst Jessica Ehrlich maintains a Buy rating and raises her price target from $490 to $525.
- Pivotal Research analyst Jeffrey Wlodarczak remains with a Buy rating and upgrades his price target from $535 to $600.
- Wolfe Research analyst Peter Supino maintains an Outperform rating and raises his price target from $485 to $500.
- Piper Sandler analyst Thomas Champion remains with a Neutral rating and increases his price target from $350 to $440.
- Deutsche Bank analyst Bryan Kraft reiterates a Buy rating and upgrades his price target from $475 to $485.
Analyst Lee Horowitz (DEUTSCHE BANK) currently has the highest performing score on NFLX with a 7/7 (100%) price target fulfillment ratio. His price targets carry an average of $22.89 (6.17%) potential upside. Netflix stock price reaches these price targets on average within 134 days.
Elon Musk Outlines Ambitious AI Goals: Self-Driving and Robots in Factories
Tesla CEO Elon Musk has set new targets for artificial intelligence (AI) products, including self-driving software and the use of humanoid robots in factories. Musk stated that Tesla is in talks with a major automaker to license its full self-driving technology. He believes that the approval of self-driving capabilities by regulators would result in an increase in the value of Tesla vehicles, which he described as potentially "the single biggest step change in history."
Musk also mentioned the potential deployment of Tesla robots on factory floors as early as next year. Although only a small number of robots have been built so far. The move to license Tesla's technology comes after several failed attempts by others in the industry to develop reliable self-driving software. Musk admitted that he has been overly optimistic in the past about achieving full self-driving, but he believes that Tesla will surpass human driving capabilities by the end of this year.
Analysts Provide Varied Recommendations and Price Targets for Tesla
- Wedbush analyst Daniel Ives reiterates an Outperform rating and a $300 price target.
- Wells Fargo analyst Colin Langan maintains an Equal-Weight rating and a $265 price target.
- Bernstein analyst Toni Sacconaghi reiterates an Underperform rating and a $150 price target.
- Barclays analyst Dan Levy remains with an Equal-Weight rating and a $260 price target.
- Needham analyst Chris Pierce stays with a Hold rating.
Analyst George Galliers (GOLDMAN) currently has the highest performing score on TSLA with 7/8 (87.5%) price target fulfillment ratio. His price targets carry an average of $-4.27 (-4.03%) potential downside. Tesla stock price reaches these price targets on average within 81 days
Philip Morris Reports Strong Q2 2023 Results and Raises Full-Year Forecast
Philip Morris has released its second-quarter and first-half results for 2023. The company reported second-quarter diluted EPS of $1.01 and adjusted diluted EPS of $1.60, showing a currency-neutral growth of 16.9%. For the full year 2023, Philip Morris is aiming for a reported diluted EPS of between $5.36 and $5.45, and an adjusted diluted EPS of $6.13 to $6.22, which would represent a currency-neutral growth of 8.0% to 9.5%.
The report showed that Philip Morris's second-quarter total cigarette and Heat-Not-Burn (HTU) shipment volume increased by 3.3%. The shipment volume of HTUs grew by 26.6%. Notably, the smoke-free product net revenues rose by 34.1%. The net revenues reached $9.0 billion, marking a 14.5% increase, and smoke-free product net revenues accounted for 35.4% of total net revenues.
HTU shipment volume growth was fueled by both distributor and wholesaler inventory movements, and IQOS continued to gain momentum. Swedish Match, now a part of Philip Morris International, performed well, particularly in the US market with ZYN nicotine pouch shipment volumes.
Philip Morris has raised its full-year 2023 forecast for organic net revenue growth to a range of 7.5% to 8.5%, and currency-neutral adjusted diluted EPS growth to a range of 8.0% to 9.5%.
Philip Morris Receives Positive Analyst Reviews With Raised Price Targets
- Morgan Stanley analyst Pamela Kaufman reiterates an Overweight rating and a $118 price target.
- Citigroup analyst Simon Hales upgrades from Neutral to Buy and the price target from $109 to $117.
Analyst Pamela Kaufman (MORGAN STANLEY) currently has the highest performing score on PM with 9/20 (45%) price target fulfillment ratio. Her price targets carry an average of $24.08 (32.46%) potential upside. Philip Morris stock price reaches these price targets on average within 684 days
Daily stock Analysts Top Price Moves Snapshot
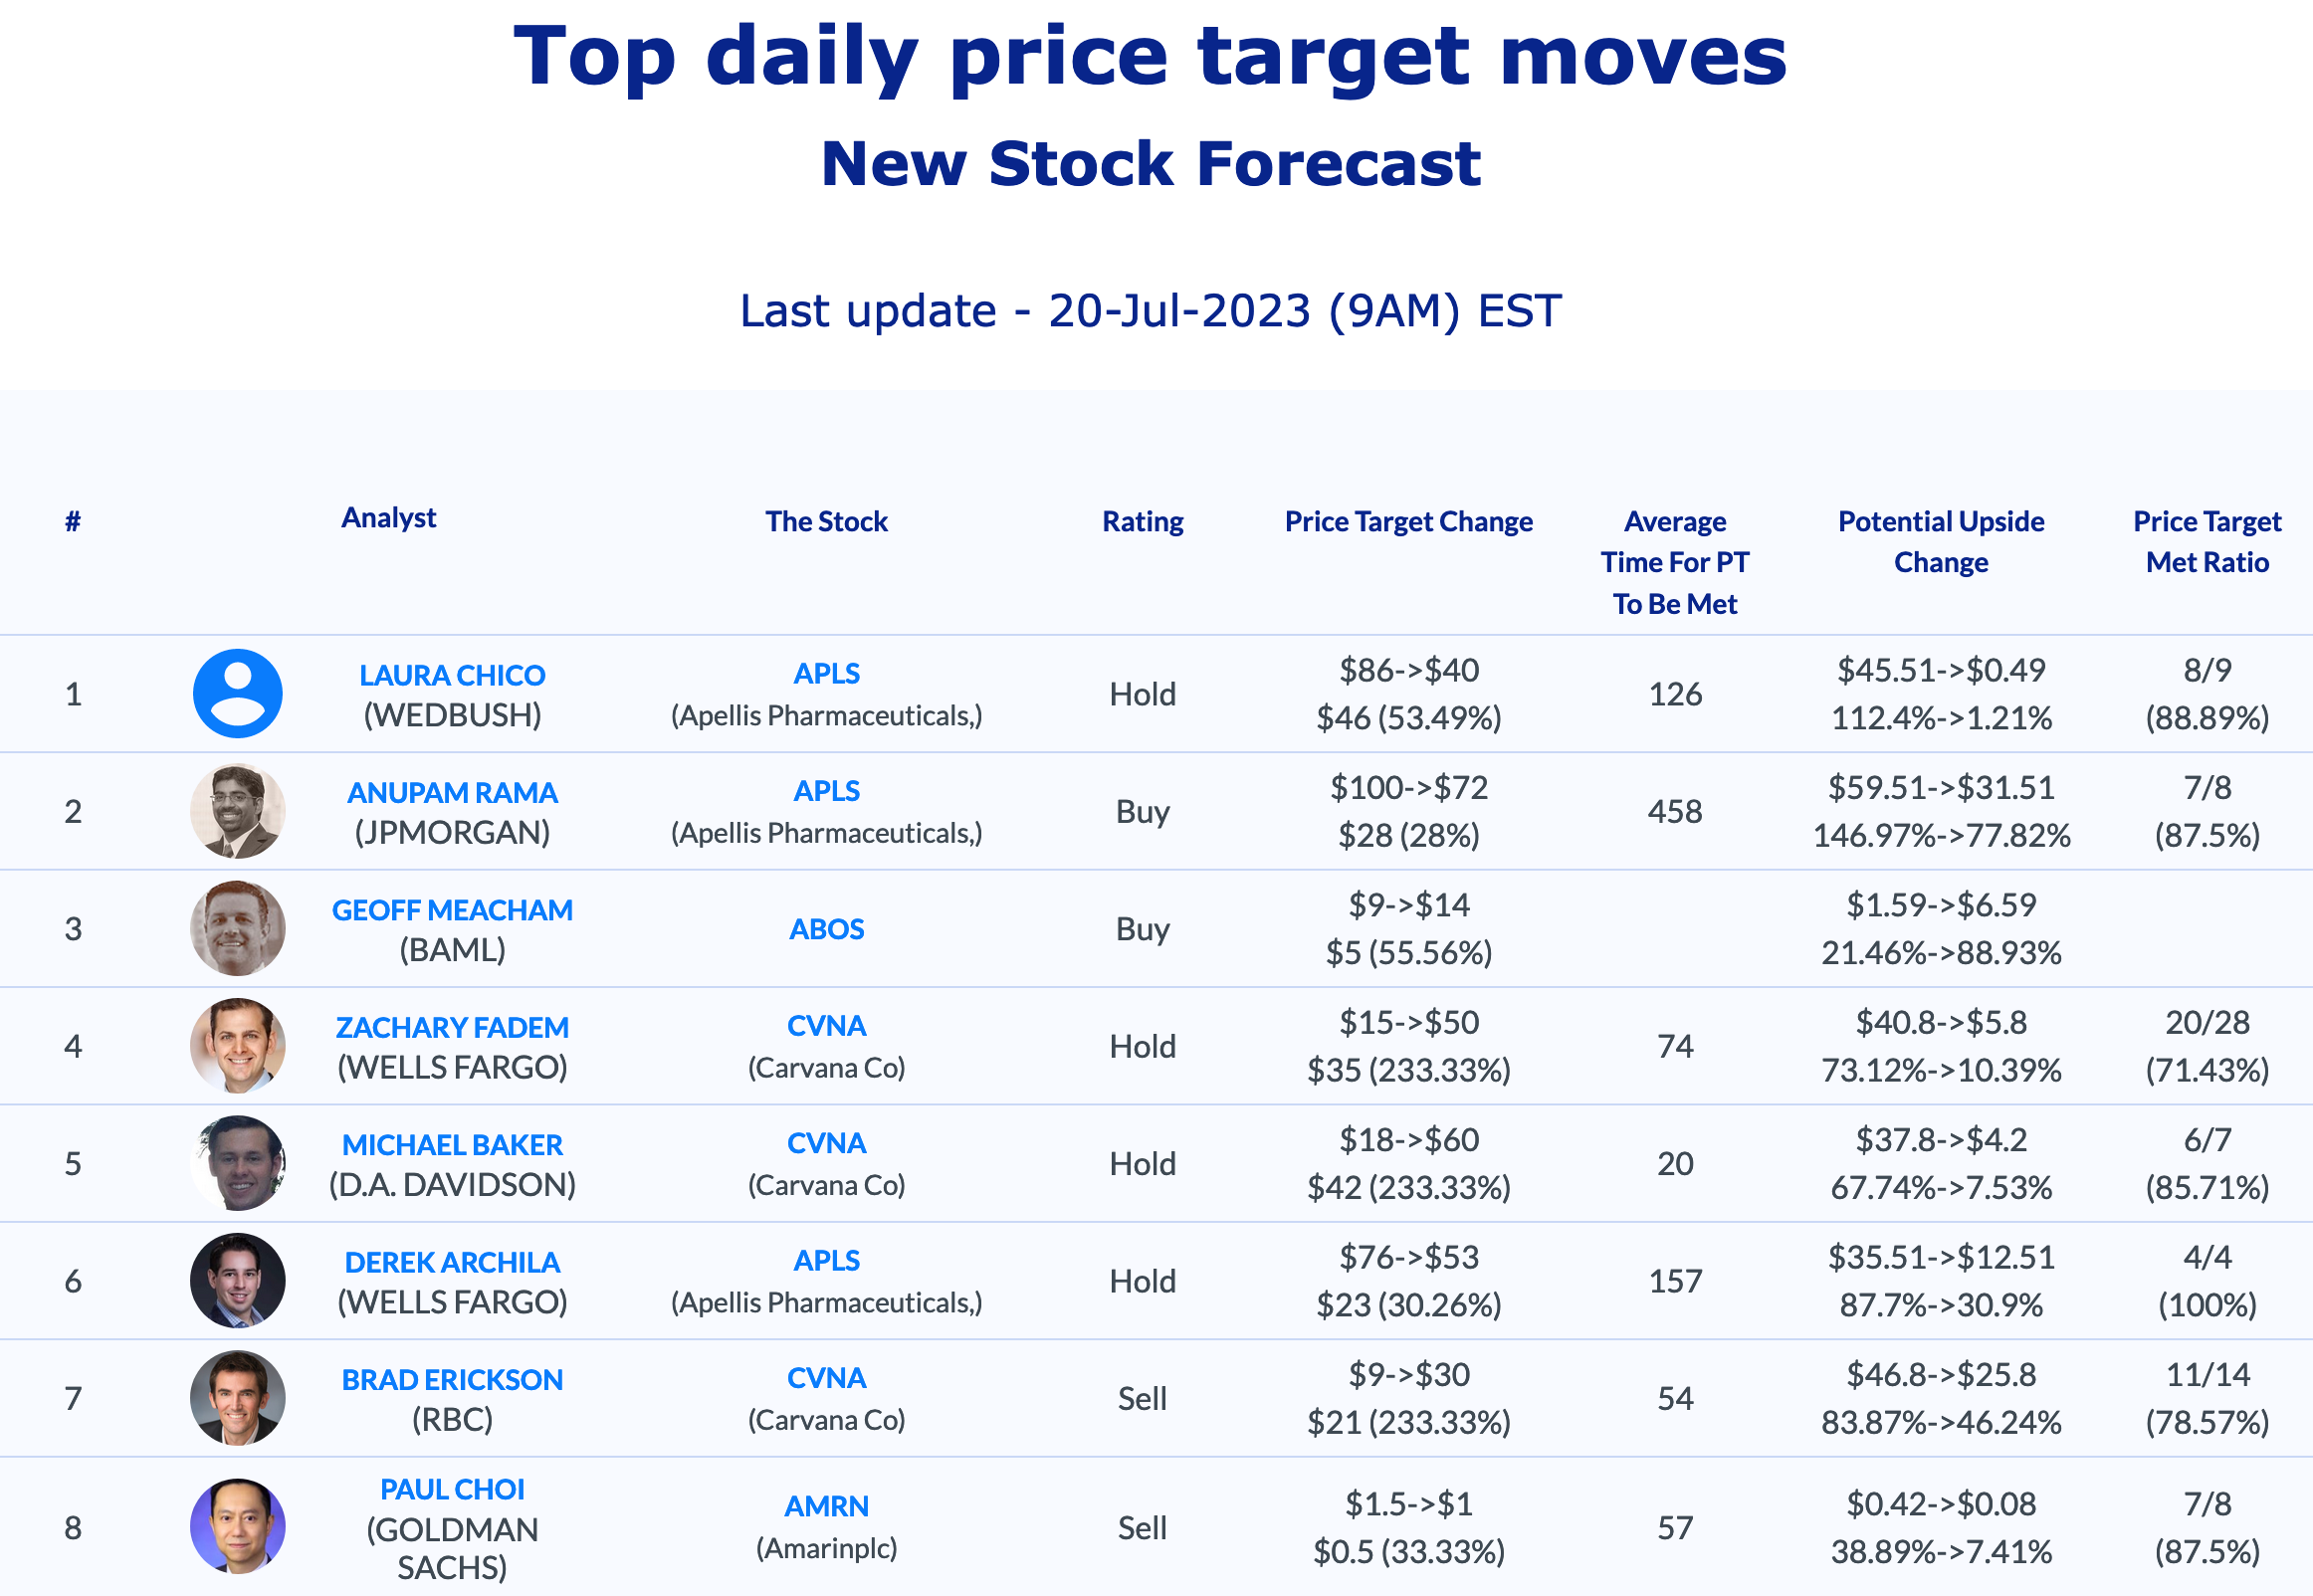
July 21, 2023: Selected stock price target news of the day: July 21, 2023
By Matthew Otto
Blackstone's Comes Close to Wall Street Expectations
Blackstone held its second quarter conference call, reporting GAAP net income of $1.2 billion and distributable earnings of $1.2 billion or $0.93 per share on $2.35 billion in revenue vs the Refinitiv expected earnings per share of 92 cents and $2.43 billion in revenue. They also declared a dividend of $0.79 per share. The company reached a milestone by surpassing $1 trillion of assets under management, making it the first alternative manager to do so. They highlighted their focus on long-term committed capital, which allows them to weather market volatility and avoid forced selling during unfavorable periods. Blackstone also emphasized their strong investment performance across various sectors and the growth potential in areas like private credit, insurance, infrastructure, energy transition, life sciences, and Asian markets.
Blackstone Receives Mixed Analyst Ratings with Higher Price Targets
- BMO Capital analyst Rufus Hone maintains a Market Perform rating and raises the price target from $93 to $97.
- Wells Fargo analyst Timothy O'Shea reiterates an Overweight rating and upgrades the price target from $104 to $118.
- JP Morgan analyst Kenneth Worthington downgrades from Overweight to Neutral rating but increases price target from $102 to $111.
- BofA Securities analyst Craig Siegenthaler remains with a Buy rating and raises the price target from $105 to $117.
- Evercore ISI Group analyst Glenn Schorr maintains Outperform rating while increasing the price target from $110 to $118.
- Piper Sandler analyst Sumeet Mody stays at an Overweight rating while upgrading the price target from $107 to $115.
- Barclays analyst Benjamin Budish reiterates an Equal-Weight rating and raises the price target from $101 to $110.
- UBS analyst Adam Beatty maintains a Buy rating and increases the price target from $102 to $120.
- Citigroup analyst Chris Allen maintains a Buy rating and raises the price target from $98 to $116.
- Morgan Stanley analyst Michael Cyprys reiterates an Overweight rating while raising the price target from $115 to $116.
Analyst Finian O'shea (WELLS FARGO) currently has the highest performing score on BX with 12/15 (80%) price target fulfillment ratio. His price targets carry an average of $12.86 (20.46%) potential upside. Blackstone stock price reaches these price targets on average within 160 days.
Discover Reports Q2 Earnings Despite Regulatory Challenges
Discover Financial Services reported its second-quarter earnings, revealing a net income of $901 million or $3.54 per share, analysts expected earnings of $3.67 per share on revenue of $3.89 billion.. The quarter showcased asset and deposit growth, with credit performance aligning with expectations. Notably, the company relaunched its cash back debit product, attracting over 30,000 new accounts and planning a national marketing campaign in the future. Additionally, Discover expanded its Discover Global Network through strategic partnerships in the Asia Pacific region and the UK, aiming to enhance international acceptance.
However, the company faced regulatory challenges concerning the misclassification of certain card accounts. Discover established a $365 million liability to compensate affected merchants and acquirers and acknowledged deficiencies in corporate governance and risk management.
Financially, Discover reported robust results, with net interest income up $567 million or 22% year-over-year and non-interest income increased $98 million or 16%. The company experienced loan growth and deposit growth, aiming to increase funding from deposits to over 70%. Operating expenses increased due to investments in compliance management systems, but Discover maintains disciplined cost management with an efficiency ratio target in the high 30s.
Analysts Adjust Price Targets for Discover Amid Market Performance Concerns
- BMO Capital analyst James Fotheringham maintains a Market Perform and lowers the price target from $103 to $99.
- Citigroup analyst Arren Cyganovich maintains a Neutral and lowers the price target from $119 to $108.
- Piper Sandler analyst Kevin Barker downgrades from Overweight to Neutral and the price target from $130 to $112.
- Stephens & Co. analyst Vincent Caintic reiterates with an Equal-Weight and a $124 price target.
Analyst Mihir Bhatia (BAML) currently has the highest performing score on DFS with 8/8 (100%) price target fulfillment ratio. His price targets carry an average of $11.65 (14.64%) potential upside. Discover Financial Services stock price reaches these price targets on average within 183 days
CSX Reports Solid Q2 Performance Despite Challenges, Focused on Long-Term Growth and Sustainability Efforts
CSX reports in the second quarter of 2023.the company's key financial highlights for the second quarter include moving over 1.5 million carloads, a 3% growth in merchandise volume and 4% growth in coal volume, generating $3.7 billion in revenue (3% lower than the previous year) which is lower than the $3.74 billion consensus estimate from Refinitiv.
Operating income decreased 13% year-over-year to $1.5 billion, resulting in an EPS decrease of 9% to $0.49 which came in line with consensus. They also discussed their safety efforts and focus on improving service to customers in various markets like automotive, minerals, metals, and coal.
Analysts Provide Mixed Recommendations for Goldman Sachs Group
- Benchmark analyst Nathan Martin reiterates a Buy rating and $37 price target.
- Susquehanna analyst Bascome Majors maintains a Neutral rating and lowers the price target from $38 to $36.
- BMO Capital analyst Fadi Chamoun reiterates an Outperform rating and $37 price target.
- Citigroup analyst Christian Wetherbee remains on a Buy rating while lowering the price target from $39 to $38.
Analyst Walter Spracklin (RBC) currently has the highest performing score on CSX with 21/22 (95.45%) price target fulfillment ratio. His price targets carry an average of $2.57 (19.31%) potential upside. CSX stock price reaches these price targets on average within 411 days
Daily stock Analysts Top Price Moves Snapshot

July 24, 2023: Selected stock price target news of the day: July 24, 2023
By Matthew Otto
Johnson & Johnson Advancing Spin-Off Strategy. Starting With Kenvue
Last week Johnson & Johnson outperformed Wall Street expectations, with growth in its medical technology business contributing significantly. The adjusted earnings per share were $2.80, exceeding the expected $2.62. The total revenue for the second quarter reached $25.53 billion, surpassing the anticipated $24.63 billion. The company's sales during this quarter saw a 6.3% growth from the same period last year.
The pharmaceutical firm registered a net income of $5.14 billion or $1.96 per share, an increase from the $4.8 billion or $1.80 per share from the same period a year ago. Following the strong performance, Johnson & Johnson has revised its full-year sales forecast upwards to between $98.80 billion and $99.80 billion, approximately $1 billion higher than the guidance provided in April. In addition, the company has also elevated its adjusted earnings outlook for 2023 to $10.70 to $10.80 per share from the previous estimate of $10.60 to $10.70 per share.
The medical devices business of Johnson & Johnson experienced robust growth, with sales rising 12.9% from the second quarter of 2022 to $7.79 billion. The company's pharmaceutical division also saw positive trends, recording $13.73 billion in sales, a more than 3% year-over-year growth.
The consumer health segment of Johnson & Johnson generated $4.01 billion in sales for the quarter, marking a 5.4% increase from the same period a year ago. Despite these favorable financial outcomes, Johnson & Johnson continues to grapple with legal issues surrounding its talc-based products. In April, the company proposed to pay close to $9 billion to settle over 38,000 lawsuits. Moreover, a recent ruling required Johnson & Johnson to pay $18.8 million to a man who claimed that exposure to its baby powder caused him to develop cancer.
New Spin Off Strategy Declared
Today, Johnson & Johnson announced an exchange offer allowing its shareholders to opt for shares in Kenvue, its newly listed consumer health unit. Johnson & Johnson, holding an 89.6% stake in Kenvue, aims to divest at least 80.1% of the shares in this unit via the offering. This move is part of Johnson & Johnson's strategy to spin off the consumer health division and focus more on its medical devices and pharmaceuticals businesses.
Johnson & Johnson disclosed that Goldman Sachs and J.P. Morgan Securities are serving as dealer managers for the offering.
Wall Street Adjust Price Targets Higher
Today, Raymond James analyst Jayson Bedford kept an Outperform and lifted his price target from $181 to $184.
Last week,
- Credit Suisse analyst Trung Huynh has revised upward the price to $175 from $170.
- JP Morgan analyst Michael Weinstein maintained a Neutral position yet raised the price target to $180 from $175.
- Morgan Stanley analyst Terence Flynn reiterated an Equal-Weight and a $187 price target.
Analyst Steve Chesney (ATLANTIC EQUITIES) has currently the highest performing score on JNJ with 7/7 (100%) price target fulfillment ratio. His price targets carry on average an $1.83 (2.07%) potential upside. Johnson & Johnson stock price reaches these price targets on average within 63 days.
Schlumberger's International Growth Outpaces North America
Schlumberger posted their Q2 2023 financial results, reporting earnings per share (EPS) of $0.72. This surpassed analyst expectations by $0.01, as the estimate was $0.71. Nevertheless, the oil-field services company's revenue for the quarter, which came in at $8.1 billion. Was slightly below the consensus estimate of $8.2 billion.
The reported Q2 EPS showed an increase of 44% compared to the same period a year earlier. Similarly, the company's revenue rose 20% from the previous year. In a statement, CEO Olivier Le Peuch expressed optimism about the company's international and offshore market growth, despite the more subdued outlook for North American drilling.
A closer look at SLB's revenues shows that international markets are starting to outpace North American markets. According to Peter McNally, an analyst at Third Bridge, international revenues now account for nearly 80% of SLB's total revenue. This represents a 21% growth in Q2 compared to the previous year, showing a widening gap with Halliburton, SLB's main competitor.
For the quarter, Schlumberger reported a cash flow of $1.61 billion. The company predicts a stronger free cash flow for the second half of 2023 compared to the first half, setting the stage for a more robust annual free cash flow than the previous year.
Wall Street Analysts Adjust a Bit Higher
- Susquehanna analyst Charles Minervino maintains a Positive outlook, increasing the price target from $65 to $68.
- Raymond James analyst James Rollyson maintains an Outperform rating, raising the price target from $65 to $67.
Analyst Ian Macpherson (PIPER SANDLER) has currently the highest performing score on SLB with 3/4 (75%) price target fulfillment ratio. His price targets carry on average an $7.33 (24.23%)potential upside. Schlumberger's stock price reaches these price targets on average within 105 days.
Autoliv Reports Larger-Than-Expected Q2 Profit Boost
Sweden's Autoliv, the world's largest airbag and seatbelt maker. Reported a larger-than-expected increase in second-quarter adjusted profit as sales surged due to product launches and higher prices. Despite improvements, Autoliv's CEO Mikael Bratt noted that the company is still experiencing higher call-off volatility than pre-pandemic levels.
Autoliv has faced abnormally high cost inflation in recent years, pressuring the company and other automotive industry suppliers to negotiate hard for price increases. CEO Bratt said that while he is pleased with the results and sees momentum building, demand has not yet met the company's expectations.
In May, Autoliv revealed a cost-saving initiative to counteract high costs, including the elimination of 8,000 jobs and the closure of several sites in Europe. This step is expected to decrease costs by about $25 million in 2024, increase to around $55 million in 2025, and reach about $75 million upon full completion, according to the company's statement.
Adjusted operating profit rose over 70% to $212 million in the quarter ending June 30, up from $124 million in the same period a year ago. This performance outperformed average Refinitiv analysts' predictions of a $197 million profit. Brokerage Jefferies acknowledged Autoliv's strong second quarter, which surpassed consensus estimates.
Autoliv reiterated its full-year outlook but anticipated that its adjusted operating margin would be back-end loaded for the second half of the year due to normal seasonality between the third and fourth quarters.
Analysts Update Price Targets Amid Continued Market Recovery
- Baird analyst Luke Junk maintains a Neutral rating and raises his price target from $102 to $106.
- Mizuho analyst Vijay Rakesh keeps a Buy rating and lifts his price target from $96 to $106.
Analyst Ryan Brinkman (JPMORGAN) has currently the highest performing score on ALV with 11/11 (100%) price target fulfillment ratio. His price targets carry on average an $12.6 (24.23%) potential upside. Autoliv stock price reaches these price targets on average within 494 days
Daily stock Analysts Top Price Moves Snapshot
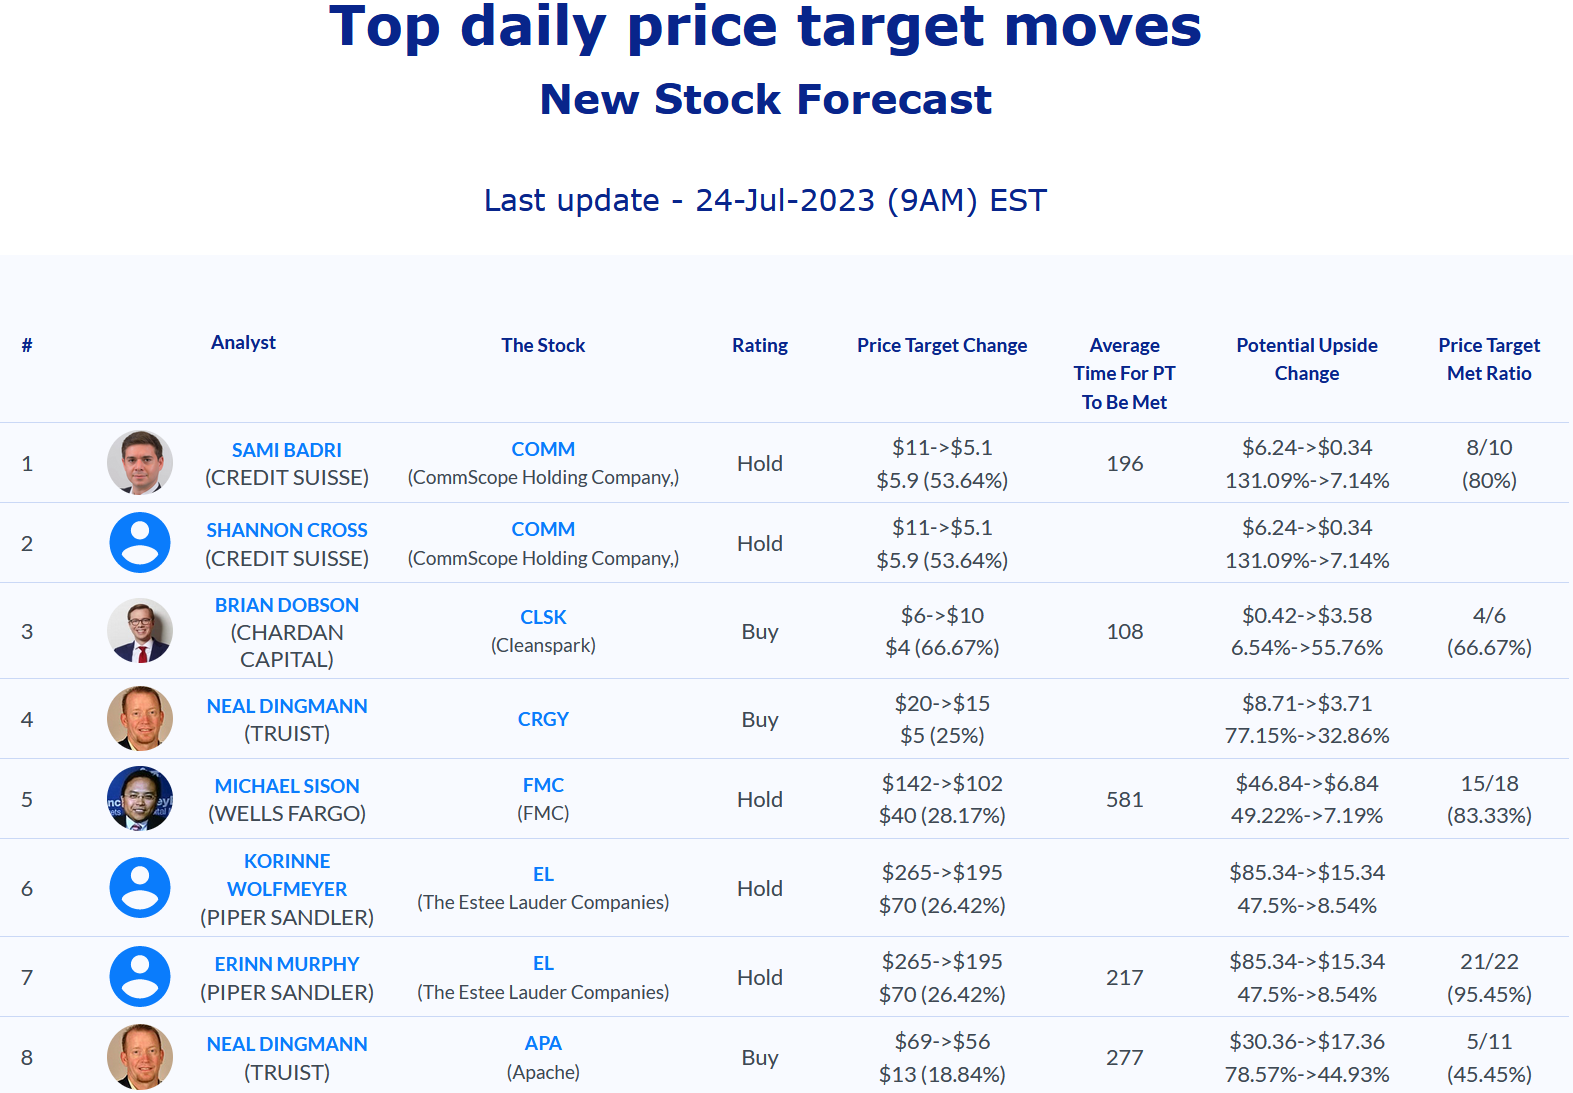
July 25, 2023: Selected stock price target news of the day: July 25, 2023
By Matthew Otto
Dominos Delivers on Q2 Results
Ann Arbor, Michigan-based Domino's Pizza released its Q2 2023 financial results, showing a strong performance despite some challenges. The company beat Wall Street estimates for quarterly profit, thanks to easing supply chain pressures and lower food costs, including cheese and the recently announced UberEats partnership.
The pizza chain's supply chain costs fell about 6% to $548.6 million in the three months ending June 18, lifting gross margins to 39.5% compared with 36.3% in the same period the previous year.
Domino's recently partnered with Uber to enhance their delivery business by allowing customers to place orders on Uber's food delivery app. This strategic partnership is expected to boost their delivery services and attract new customers. The service is set to be piloted in four U.S. markets in the fall.
The revenue for the quarter stood at $1.02 billion, slightly lower than analysts' average estimate of $1.07 billion. However, profit per share of $3.08 exceeded the expected $3.05. U.S. same-store sales rose 0.1%, missing estimates of about 0.2% increase.
Domino's highlighted several key financial indicators for Q2 2023, including global retail sales growth of 5.8% (excluding foreign currency impact), international same-store sales growth of 3.6%, and a net store growth of 197. The diluted EPS increased by 9.2% to $3.08.
In addition, Domino's declared a $1.21 per share quarterly dividend for shareholders of record as of September 15, 2023, to be paid on September 29, 2023. The company will host its Investor Day on December 7, 2023, at its headquarters in Ann Arbor, Michigan.
Despite revenues decreasing by 3.8% in Q2 2023 as compared to Q2 2022, income from Operations increased by 9.7% primarily due to higher global franchise revenues resulting from retail sales growth. Net Income also increased by 6.7% due to higher income from operations and a decrease in the provision for income taxes.
Wall Street Analysts Agree on the Potential Future Margins
- Oppenheimer analyst Brian Bittner maintained an Outperform rating and raised the price target from $400 to $427.
- Morgan Stanley analyst Brian Harbour also kept an Overweight rating while increasing the price target from $425 to $440.
- Christopher Carril from RBC Capital retained an Outperform rating and raised the price target from $430 to $440.
- BMO Capital's Andrew Strelzik kept an Outperform rating and lifted the price target from $450 to $455.
- Stephens & Co. analyst Joshua Long reiterated an Equal-Weight rating and maintained a $365 price target.
- Citigroup analyst Jon Tower maintained a Neutral rating and boosted the price target from $405 to $431.
- Barclays analyst Jeffrey Bernstein retained an Underweight rating and increased the price target from $270 to $320.
- TD Cowen analyst Andrew Charles kept a Market Perform rating and raised the price target from $330 to $420.
- Finally, Wedbush's Nick Setyan maintained an Outperform rating and lifted the price target from $430 to $445.
Analyst Jeff Farmer (GORDON HASKETT) has currently the highest performing score on DMZ with 4/4 (100%) price target fulfillment ratio. His price targets carry on average an $-70.9 (-18.37%) potential downside. Domino's stock price reaches these price targets on average within 117 days.
F5 Surprises on Earnings, Sees Continued growth
F5 announced its financial results for Q3 of the fiscal year 2023. Despite challenges presented by macroeconomic uncertainty, the company reported a 4% growth in revenue from the same period in 2022, from $674 million to $703 million. This growth is attributed to an 8% increase in global services revenue and a 1% increase in product revenue, with a 5% growth in systems revenue, although software revenue saw a 3% drop.
The company's GAAP (Generally Accepted Accounting Principles) gross profit was $561 million, a gross margin of 79.8%. This is a slight decrease in gross margin compared to Q3 of 2022, which stood at 80.6%. However, the non-GAAP gross profit was $579 million, representing a non-GAAP gross margin of 82.5%.
Operating profit was $104 million, a GAAP operating margin of 14.7%. This is also a slight decrease from 2022's Q3 GAAP operating margin of 15.9%. However, the non-GAAP operating profit increased to $233 million from $194 million the previous year, raising the non-GAAP operating margin to 33.2% from 28.8%.
Net income for Q3 2023 was $89 million, or $1.48 per diluted share, a rise from 2022's Q3 figure of $83 million, or $1.37 per diluted share. Non-GAAP net income for Q3 2023 was $194 million, or $3.21 per diluted share, up from $155 million, or $2.57 per diluted share, in the same period the previous year.
The company's outlook for Q4 2023 anticipates a revenue in the range of $690 million to $710 million, with non-GAAP earnings in the range of $3.15 to $3.27 per diluted share.
The report exceeded top and bottom-line expectations for the fiscal third quarter, posting adjusted earnings of $3.21 per share on revenue of $703 million, compared to analysts' expectations of $2.86 in earnings per share and revenue of $699 million.
Wall Street Action
- Morgan Stanley analyst Meta Marshall reiterates an Equal-Weight rating and maintains a $165 price target.
- RBC Capital analyst Matthew Hedberg maintains a Sector Perform rating and raises the price target from $146 to $173.
- Barclays analyst Tim Long maintains an Equal-Weight rating and raises the price target from $140 to $162.
- Needham analyst Alex Henderson maintains a Buy rating and raises the price target from $175 to $180.
- Keybanc analyst Thomas Blakey maintains an Overweight rating and raises the price target from $179 to $193.
- Jefferies analyst George Notter raises F5's price target to $150.
Analyst Samik Chatterjee (JPMORGAN) has currently the highest performing score on FFIV with 11/14 (78.57%) price target fulfillment ratio. His price targets carry on average an $20.31 (12.50%) potential upside. F5 stock price reaches these price targets on average within 296 days.
Kodiak Discontinues Development of Tarcocimab Tedromer Following Phase 3 Trials' Results
Kodiak Sciences has announced the topline results from its Phase 3 clinical trials of tarcocimab tedromer, an innovative antibody biopolymer conjugate that was being studied for its potential in treating neovascular age-related macular degeneration (AMD) and diabetic macular edema (DME), two leading causes of blindness in older adults.
The company conducted three Phase 3 trials,which involved 557 treatment-naïve subjects with wet AMD. The trial successfully met its primary endpoint demonstrating non-inferior visual acuity gains for tarcocimab dosed monthly compared to aflibercept dosed every 8 weeks following 3 monthly loading doses. Aflibercept is a current standard treatment for AMD. Additionally, tarcocimab was found to be safe and well tolerated with a low rate of intraocular inflammation.
However, the GLEAM and GLIMMER trials, which involved 917 treatment-naïve subjects with DME, did not meet their primary efficacy endpoints. These identically designed studies were aimed at evaluating the efficacy, durability, and safety of tarcocimab tedromer. Although a significant proportion of patients demonstrated extended treatment intervals with tarcocimab, the studies failed to show non-inferior visual acuity gains for tarcocimab compared to aflibercept. Aflibercept is also a common treatment for DME.
Furthermore, an unexpected increase in the incidence of cataracts, a common eye condition that clouds the lens leading to decreased vision, was observed in the tarcocimab groups of the GLEAM and GLIMMER studies. This unexpected finding was a significant factor contributing to the failure of both studies. In contrast, no such imbalance in cataracts was observed in the DAYLIGHT study.
Following the disappointing results from the GLEAM and GLIMMER trials and the overall evaluation of the drug's effectiveness, Kodiak has made the decision to discontinue further development of tarcocimab. The decision comes despite the potential tarcocimab had shown in the treatment of AMD and DME.
Major Analyst Firms Downgrade Following Phase 3 Clinical Trials Results
- Chardan Capital's Daniil Gataulin has downgraded Kodiak Sciences from Buy to Neutral.
- Barclays analyst Gena Wang maintains an Underweight rating and lowers the price target from $5 to $2.
- JP Morgan analyst Anupam Rama downgrades from Neutral to Underweight.
- Jefferies analyst Michael Yee downgrades from Buy to Hold, setting a $3 price target.
Analyst Anupam Rama (JPMORGAN) has currently the highest performing score on KOD with 2/4 (50%) price target fulfillment ratio. His price targets carry on average an $7.14 (37.32%) potential upside. Kodiak Sciences stock price reaches these price targets on average within 154 days
Daily stock Analysts Top Price Moves Snapshot
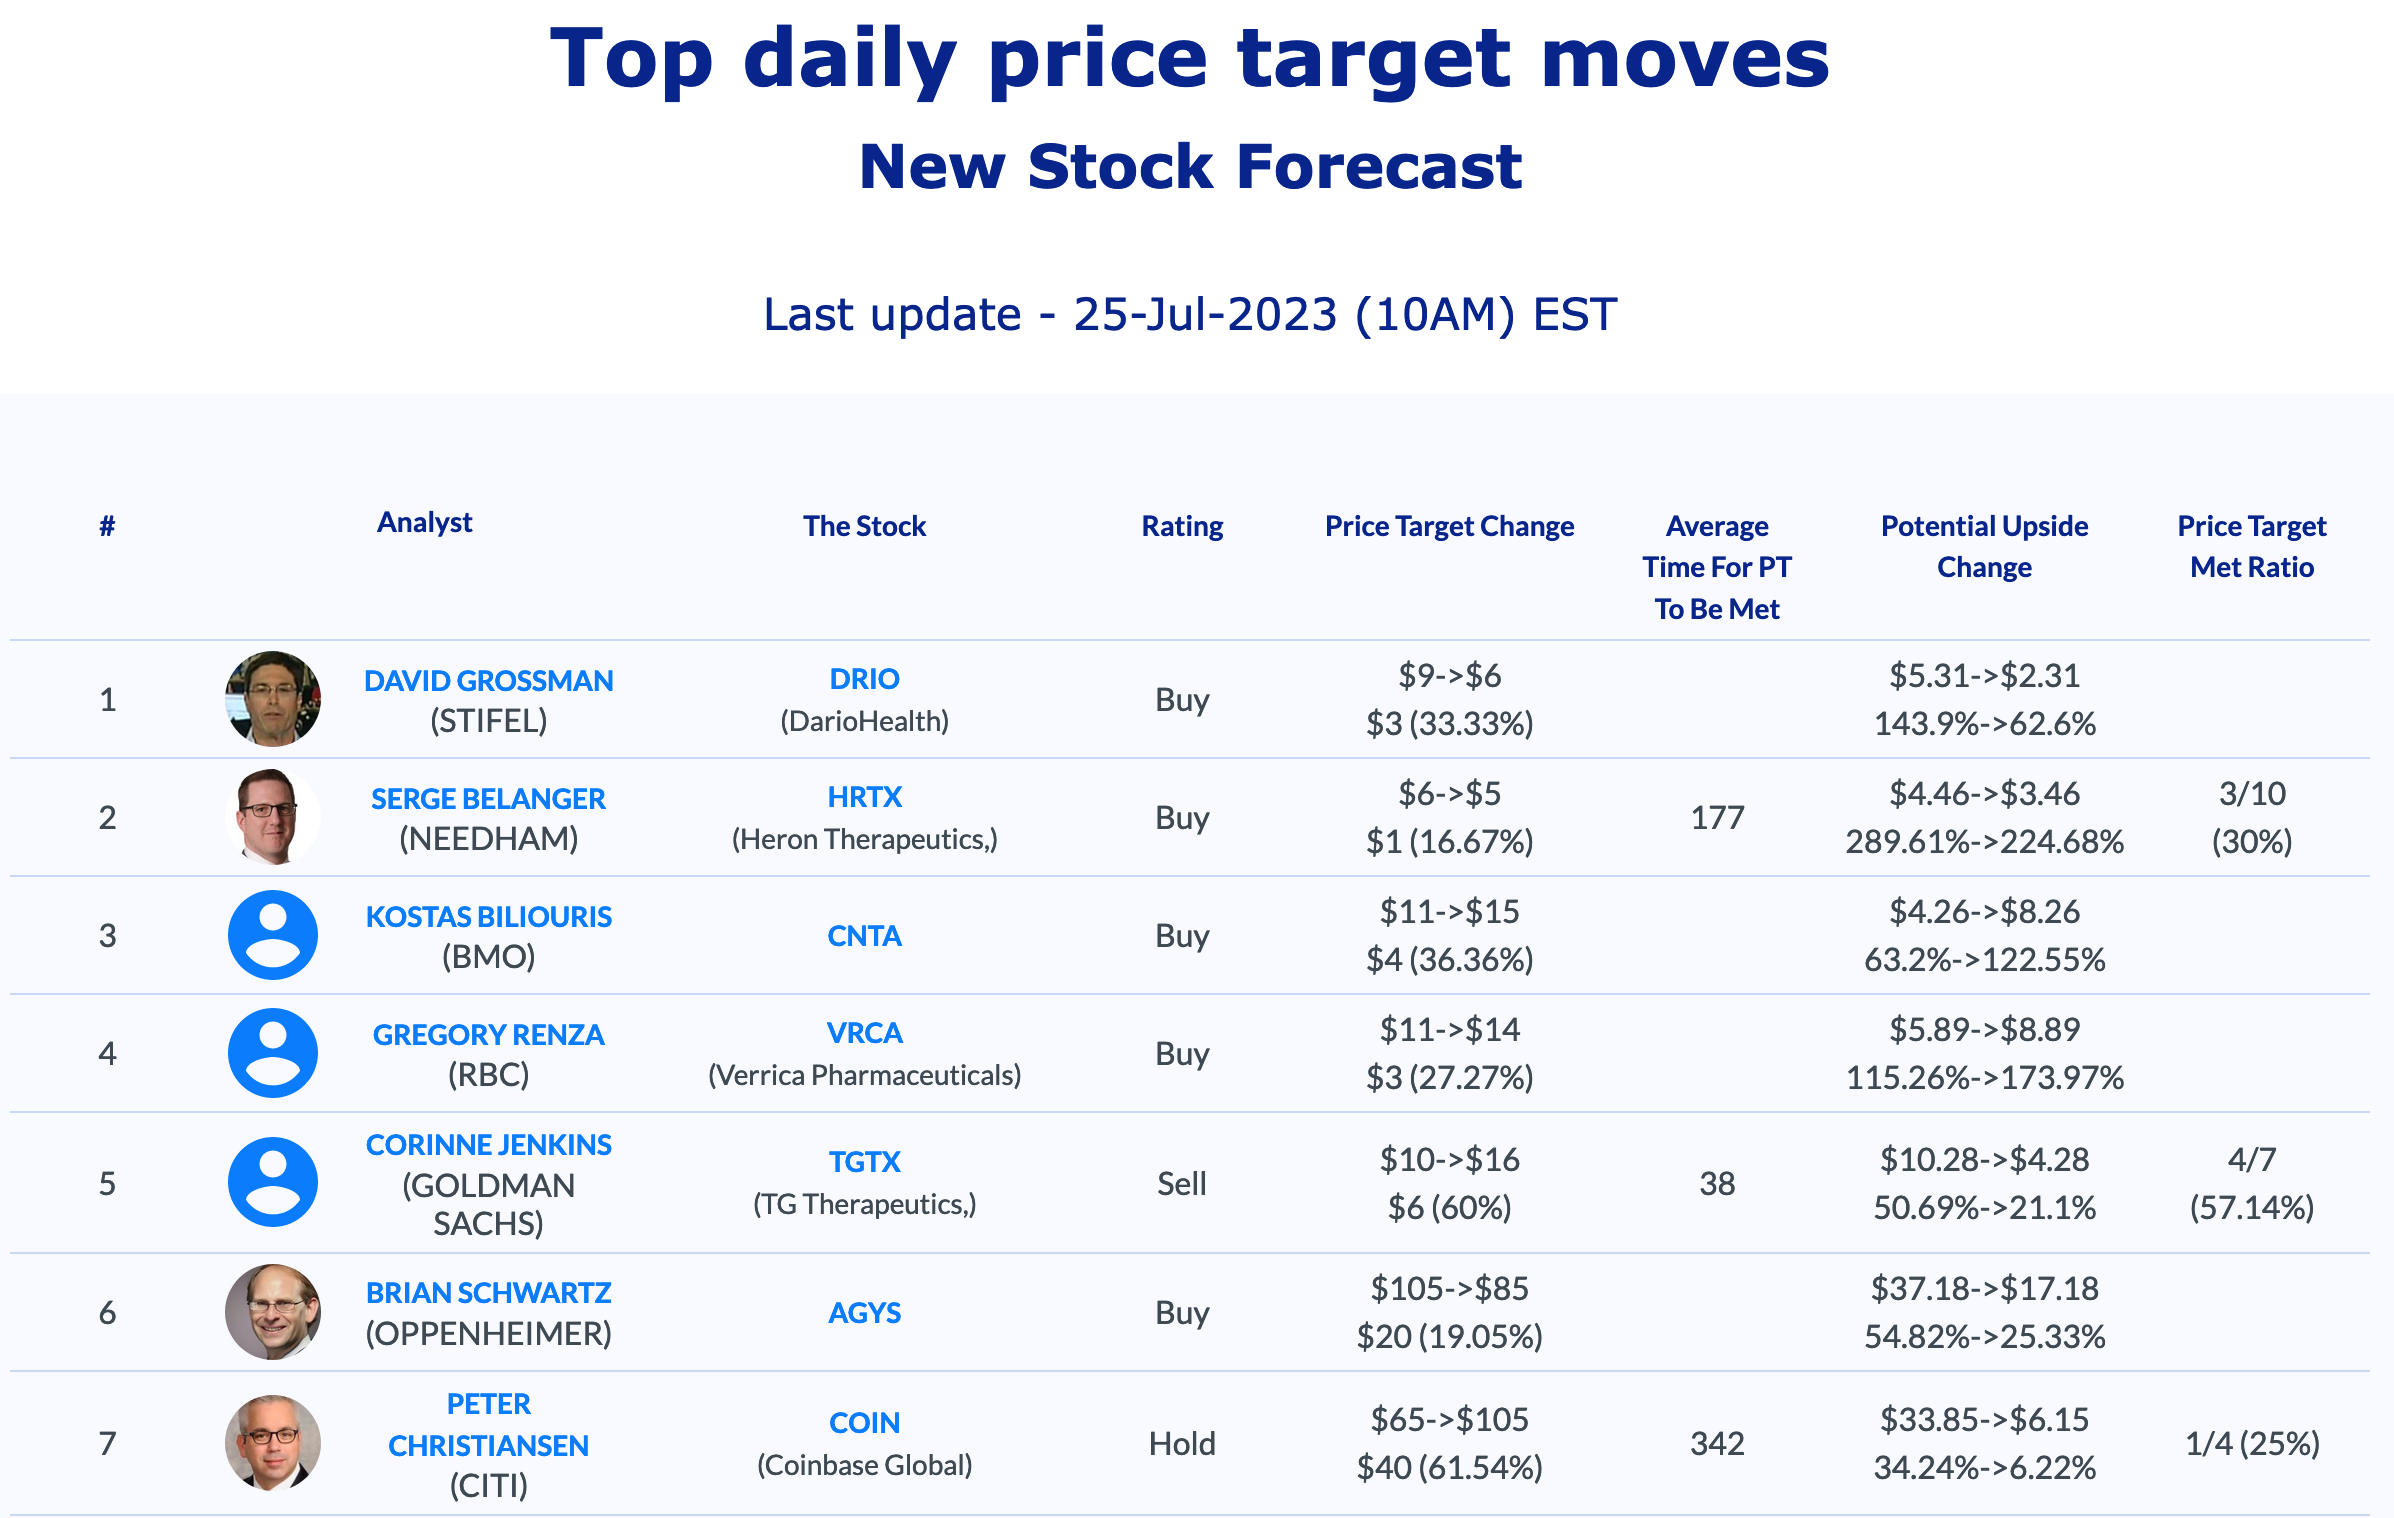
July 26, 2023: Selected stock price target news of the day: July 26, 2023
By: Matthew Otto
Alphabet Posts Strong Q2 Results
Alphabet, Google's parent company, has posted strong results for Q2 2023, reporting earnings per share of $1.44, significantly outperforming analyst expectations of $1.34. The company reported total revenues of $74.6 billion, exceeding the expected $72.85 billion. Specific sectors such as Google Search and YouTube showed a substantial uptick, with revenues of $42.63 billion (a 4.8% increase) and $7.67 billion (a 4.4% increase), respectively. However, the Google Network sector reported a revenue drop of 5% to $7.85 billion.
Google Cloud stood out as a high performer this quarter, with a 28% rise in revenues to $8.03 billion. It also recorded a record operating income of $395 million, showing resilience by bouncing back from an operating loss of $590 million in the same quarter the previous year.
During the earnings call, Pichai emphasized Alphabet's investments in artificial intelligence (AI). The company is expecting AI to drive growth in search advertising revenue and expand the potential of its cloud business
Ruth Porat's Role Transition
Alphabet also announced that Ruth Porat, currently Chief Financial Officer, would be stepping into a new role as Chief Investment Officer of Alphabet and Google in September. Porat will oversee Alphabet's Other Bets portfolio and continue her role as CFO until a suitable replacement is found.
Analysts Approve Google Going into AI
- JMP Securities analyst Andrew Boone holds steady with a Market Outperform rating and adjusts the price target upward from $132 to $138.
- Needham analyst Laura Martin sustains a Buy rating, increasing her price target from $115 to $140.
- Keybanc analyst Justin Patterson continues to support Alphabet with an Overweight rating, lifting the price target from $140 to $145.
- Wolfe Research analyst Deepak Mathivanan keeps an Outperform rating, pushing his price target up from $140 to $150.
- Truist Securities analyst Youssef Squali escalates his price target to $160.
- Canaccord Genuity analyst Maria Ripps bumps his price target up to $155.
- Jefferies analyst Brent Thill hikes Alphabet's price target to $165.
- RBC Capital analyst Brad Erickson enhances his price target to $155.
Analyst Alan Gould (LOOP CAPITAL) has currently the highest performing score on GOOGL with 16/6 (100%) price target fulfillment ratio. His price targets carry on average an $9.33 (11.44%) potential upside. Alphabet stock price reaches these price targets on average within 72 days.
Biogen Reaffirms Full Year Guidance, Reduces of 1,000 Jobs
Biogen announced its Q2 2023 financial results, reporting revenue of $2,456 million versus the consensus estimate of $2,370 million and GAAP and Non-GAAP diluted EPS of $4.07 and $4.02 respectively, $0.24 better than the analyst estimate. The company's newly launched Alzheimer's drug, LEQEMBI, a monoclonal antibody medication used for the treatment of Alzheimer's disease, which is expected to contribute significantly to its growth, following its launch in the U.S.
Key developments include the commencement of the "Fit for Growth" program, aimed at achieving approximately $1 billion in gross operating expense savings by 2025, a net reduction of 1,000 headcount, representing 11% of its workforce, and the extension of TECFIDERA regulatory market protection in the E.U. until February 2025. In addition, new data underline the potential benefits of SPINRAZA for the treatment of spinal muscular atrophy in infants and toddlers, One in every 6,000 babies is born with SMA. The firm also reports a nearly complete R&D pipeline prioritization, allowing for greater focus on high-value opportunities.
Despite a 5% decline in second-quarter revenue compared to the same period last year, the company reaffirmed its full-year guidance for 2023.
Wall Street Reaction Is Mixed
- Wedbush analyst Laura Chico maintains a Neutral position with a lowered price target from $269 to $268.
- BMO Capital analyst Evan Seigerman holds an Outperform rating, albeit with a lowered price target from $357 to $347.
- HC Wainwright analyst Andrew Fein reiterates a Buy and a price target of $325.
- Needham analyst Ami Fadia also maintains a Buy, raising the price target from $320 to $323.
- Morgan Stanley analyst Matthew Harrison has raised the price target to $363.
- RBC Capital analyst Brian Abrahams has raised the price target to $379.
Analyst Brian Skorney (BAIRD) has currently the highest performing score on BIIB with 13/17 (76.47%) price target fulfillment ratio. His price targets carry on average an $25.22 (9.40%) potential upside. Biogen stock price reaches these price targets on average within 201 days
Spotify's Q2 User Growth Exceeds Estimates but Revenue Falls Short
Music streaming giant Spotify has surpassed estimates in Q2 for both its monthly active users and premium subscribers, despite missing the mark on revenue projections. Here are some key takeaways from their Q2 report:
- User Growth: Spotify's monthly active users rose to 551 million, surpassing the company's own guidance and analysts' forecast of 526.8 million. This marks the sixth consecutive quarter of robust user growth for the company. Furthermore, the premium subscribers, a critical component of Spotify's revenue, increased by 17% to 220 million, beating estimates of 216.6 million.
- Revenue: Despite the impressive user growth, Spotify reported quarterly revenue of 3.18 billion euros ($3.51 billion), falling slightly short of analysts' estimates of 3.21 billion euros. CEO Daniel Ek believes revenue growth will follow user growth, a pattern they've seen repeatedly at Spotify.
- Price Increases: Spotify recently raised prices for its premium plans in several countries, a change that is expected to minimally impact revenue this quarter but will start to take effect from September. CFO Paul Vogel anticipates the full effect of the price increase to be felt in Q4.
- Future Expectations: Looking ahead, Spotify projects that premium subscribers will reach 224 million this quarter, with revenue estimated at 3.3 billion euros. These expectations are slightly above analysts' predictions of 222.4 million subscribers but slightly below the forecasted revenue of 3.40 billion euros.
Analysts Reaction is Mostly Positive
- Credit Suisse analyst Douglas Mitchelson reiterates a Neutral rating and a $120 price target.
- Deutsche Bank analyst Benjamin Black upgraded from Hold to Buy, setting a new price target at $180.
- Barclays analyst Mario Lu maintains an Overweight rating and raises the price target from $180 to $182.
- Goldman Sachs analyst Eric Sheridan continues to hold a Neutral rating, raising the price target from $156 to $163.
- Macquarie analyst Tim Nollen lowered Spotify's price target to $185.
- Rosenblatt analyst Barton Crockett raised Spotify's price target to $150.
Analyst Andrew Marok (RAYMOND JAMES) has currently the highest performing score on SPOT with 4/4 (100%) price target fulfillment ratio. His price targets carry on average an $20.15 (19.49%) potential upside. Spotify stock price reaches these price targets on average within 124 days.
Daily stock Analysts Top Price Moves Snapshot
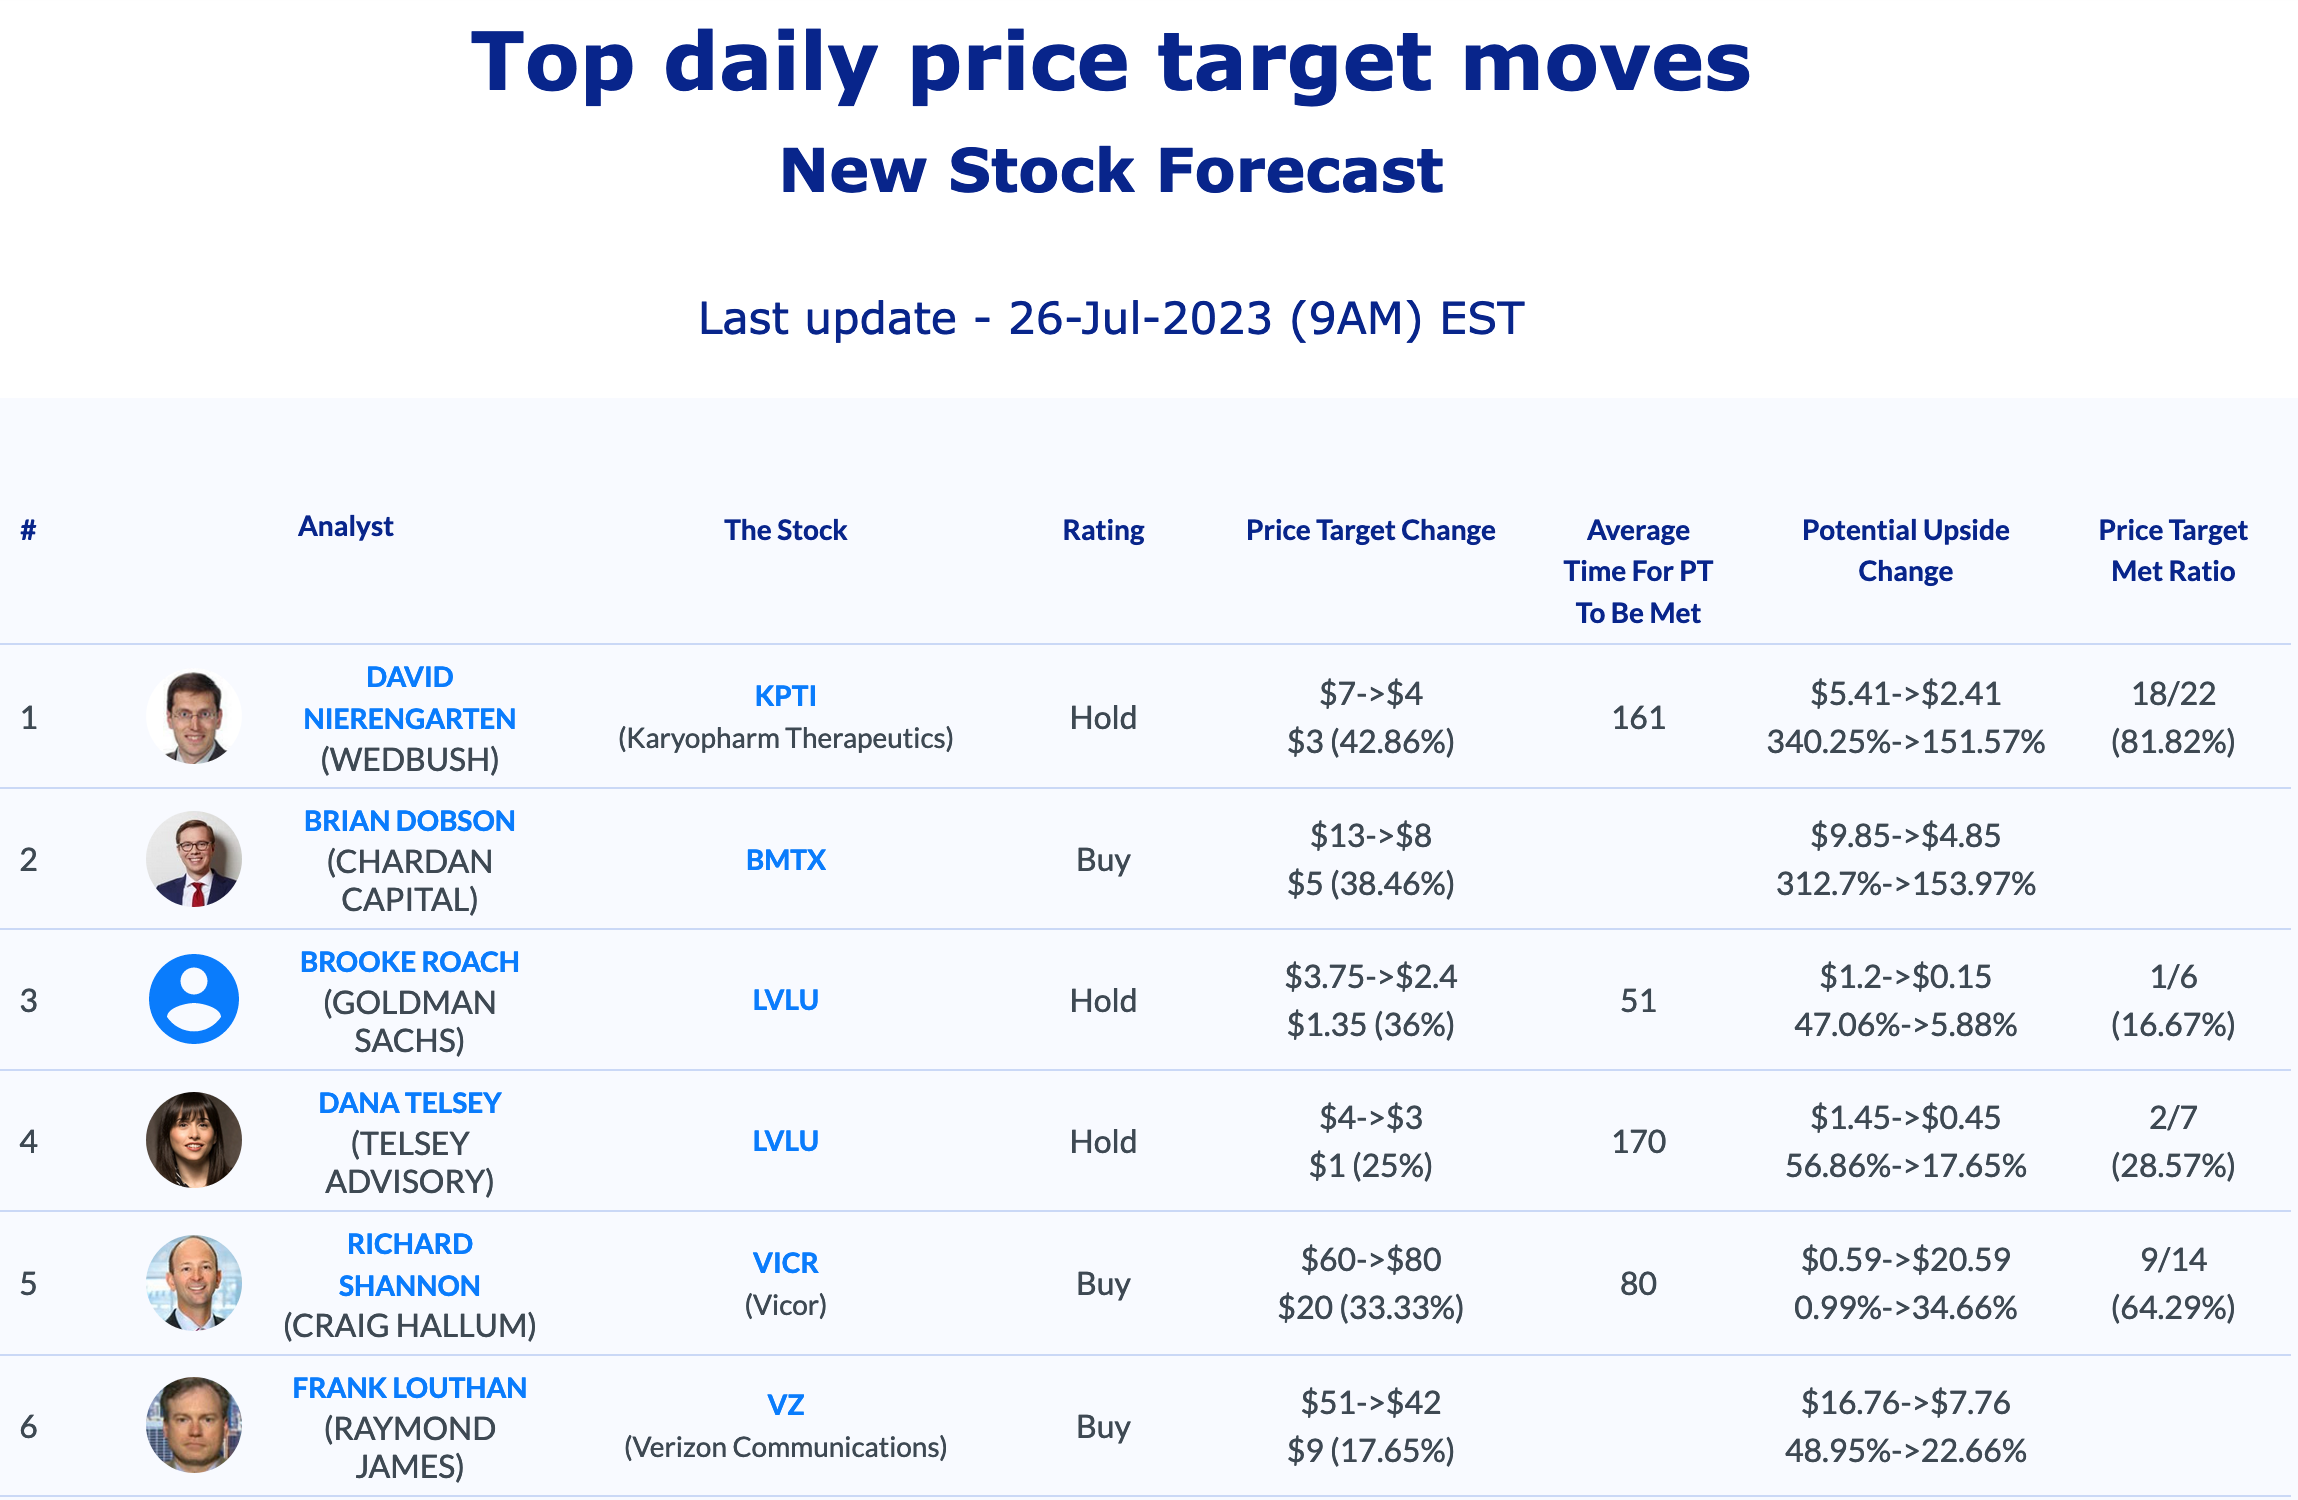
July 27, 2023: Selected stock price target news of the day: July 27, 2023
By: Matthew Otto
Meta Platforms Beats Q2 Expectations, Announces Plans for AI and Metaverse Expansion
Meta Platforms reported second-quarter results, with revenue up 11% to $32 billion and profits at $2.98 per share, both exceeding Wall Street predictions. The company also provided revenue guidance for Q3, which surpassed analyst estimates. CEO Mark Zuckerberg announced plans for new AI products and expressed optimism about Threads, Meta's Twitter competitor, and Reels, the TikTok competitor.
The firm reported an increase in active users, with "daily active people" reaching 3.07 billion and Facebook daily active users hitting 2.06 billion. Despite this, the headcount has decreased by 14% in comparison to last year, due to recent layoff announcements.
Ad impressions across Meta's family of apps rose by 34%, although the average price per ad decreased by 16%. In the Family of Apps segment, revenue increased by 12% to $31.7 billion, while in the Reality Labs segment, which focuses on VR and metaverse projects, revenue fell 39% to $276 million.
For 2023, Meta expects total expenses to range between $88 billion and $91 billion, an increase from previous projections due to legal expenses. It also anticipates capital expenditures to be between $27 billion and $30 billion, a decrease from previous estimates.
Meta plans to increase capital spending in 2024, focusing on investments in data centers and servers to support AI-related work. The company expects operating losses in the Reality Labs segment to rise in 2023 and again in 2024 due to product development efforts in augmented and virtual reality.
Wall Street Analysts Adjusts Higher on Meta’s Initiatives
- Oppenheimer's Jason Helfstein retains Outperform rating, adjusts price target from $350 to $385.
- UBS's Lloyd Walmsley continues with Buy rating, boosts price target from $335 to $400.
- Brian Nowak from Morgan Stanley upholds Overweight rating, elevates price target from $350 to $375.
- Goldman Sachs's Eric Sheridan persists with Buy rating, revises price target from $335 to $384.
- Credit Suisse's Stephen Ju maintains Outperform stance, enhances price target from $361 to $407.
- JMP Securities' Andrew Boone sustains Market Outperform rating, increases price target from $350 to $380.
- Ronald Josey from Citigroup sticks with Buy recommendation, amends price target from $360 to $385.
- Ross Sandler from Barclays holds Overweight rating, advances price target from $320 to $410.
- Needham's Laura Martin reiterates Underperform rating.
- Ken Gawrelski from Wells Fargo upgrades Meta Platforms from Equal-Weight to Overweight, escalates price target from $313 to $389.
- Deepak Mathivanan from Wolfe Research revises the price target upward to $390.
- RBC Capital's Brad Erickson adjusts the price target to $400.
- Youssef Squali from Truist Securities elevates the price target to $390.
Analyst Daniel Salmon (BMO) has currently the highest performing score on META with 21/24 (87.5%) price target fulfillment ratio. His price targets carry on average an $20.42 (8.97%) potential upside. META Platforms stock price reaches these price targets on average within 81 days.
Union Pacific Misses on Earnings and Revenue, Changes Management
Union Pacific Corporation reported its Q2 2023 results, indicating some challenges amid the changing business environment. The company's earnings per diluted share stood at $2.57 which is $0.17 worse than the analyst estimate of $2.7. Operating revenue also decreased by 5%, while the reportable derailment rate showed an improvement of 9%.
Revenue for the quarter came in at $6 billion versus the consensus estimate of $6.12 billion.
The company's net income for the second quarter was $1.6 billion, lower than the Q2 2022 net income of $1.8 billion. Union Pacific's CEO, Lance Fritz, attributed the results to softening consumer markets, inflation, a one-off labor expense, and increased workforce levels. Despite these challenges,
In terms of financial results, the operating revenue of $6 billion versus the consensus estimate of $6.12 billion. Revenue was driven by reduced fuel surcharge revenue, lower volumes, and an unfavorable business mix. However, this was somewhat offset by core pricing gains. Business volumes, as measured by total revenue carloads, were down 2%. The operating ratio experienced a 280 basis points increase to 63.0%. Operating income declined 12% to $2.2 billion. The company also reported a repurchase of 600,000 shares in Q2 2023, costing an aggregate of $120 million.
Union Pacific's operating performance showed mixed results. Quarterly freight car velocity saw an 8% improvement to 202 daily miles per car, and locomotive productivity improved by 2%. However, the average maximum train length declined slightly, and workforce productivity decreased 5%. There was a minor deterioration in the fuel consumption rate, but notably, the first half reportable derailment rate showed a significant improvement, dropping 9% to 2.45 per million train miles.
Management Change Ahead of Turbulent Times
Looking forward, the company expects a challenging demand and cost environment to pressure the 2023 outlook, with consumer-related volumes likely driving full year volume expectations below Industrial Production. Union Pacific plans a capital allocation of $3.6 billion for 2023, while maintaining a dividend of $1.30 per quarter, with no further share repurchases planned for the year.
The company also announced leadership changes, appointing Jim Vena as CEO, Beth Whited as president, and electing Mike McCarthy as chairman. Two new independent directors, Doyle Simons and John Wiehoff, have also been appointed to the Board.
Wall Street Analysts Reacts Positively to New Leadership
- JP Morgan's analyst Brian Ossenbeck upholds a Neutral rating and lifts the price target from $208 to $254.
- Mark Levin of Benchmark continues with a Buy rating and escalates the price target from $230 to $264.
- BMO Capital's Fadi Chamoun sustains an Outperform rating and advances the price target from $240 to $270.
- Ariel Rosa from Credit Suisse persists with an Outperform rating and hikes the price target from $235 to $262.
- Citigroup's Christian Wetherbee sticks with a Buy rating and enhances the price target from $235 to $270.
- Brandon Oglenski from Barclays retains an Overweight rating and boosts the price target from $230 to $285.
- Raymond James' Patrick Tyler Brown preserves a Strong Buy rating and lifts the price target from $230 to $270.
- Oliver Holmes of Atlantic Equities downgrades Union Pacific from Overweight to Neutral and sets a new price target at $244.
- Wolfe Research's Scott Group elevates the price target to $275.
- Bascome Majors from Susquehanna raises the price target to $240.
- Justin Long at Stephens revises the price target upward to $257.
- Jason Seidl from TD Cowen keeps an Outperform rating and increases the price target from $210 to $240.
Analyst Ravi Shanker (MORGAN STANLEY) has currently the highest performing score on UNP with 24/33 (72.73%) price target fulfillment ratio. His price targets carry on average an $-10.11 (-3.18%) potential downside. Union Pacific stock price reaches these price targets on average within 151 days.
ServiceNow Q2 2023 Earnings Surpass Expectations, Driven by Demand for AI Innovations
ServiceNow has reported its financial results for Q2 2023, exceeding guidance across all top-line growth and profitability metrics, which has prompted the company to raise its 2023 subscription revenues and operating margin guidance. Subscription revenues hit $2,075 million in Q2 2023, marking a 25% YoY growth, while total revenues amounted to $2,150 million, a 23% YoY growth. Current remaining performance obligations totaled $7.20 billion, a 25% YoY increase. The company concluded the quarter with 70 transactions over $1 million in net new ACV, a 30% YoY increase, and 45 customers with more than $20 million in ACV, a 55% YoY increase.
ServiceNow's Chairman and CEO, Bill McDermott, attributes these supercharged results to unprecedented demand for the company's organic innovation, particularly in the context of the AI world, which he claims is enabling substantial productivity increases. ServiceNow's Q2 performance has also been bolstered by a range of new solutions that embed generative AI across the Now Platform, and partnerships with industry leaders like NVIDIA and Accenture to implement new generative AI use cases.
In the second quarter, the company also announced an expanded partnership with KPMG to reimagine finance, supply chain, and procurement operations, along with a partnership with Cognizant to accelerate the adoption of AI-driven automation across various industries. The company was recently named to the Fortune 500 list and recognized as a Visionary in the 2023 Gartner® Magic Quadrant for Application Performance Monitoring (APM) and Observability.
ServiceNow's Q3 subscription revenue is forecasted to be in the range of $2.19 billion to $2.20 billion, exceeding analysts' average expectation of $2.15 billion. The company also reported an adjusted earning of $2.37 per share for Q2 2023, surpassing the profit estimate of $2.05 per share.
Financial Analysts Adjust Price Targets on ServiceNow
- Analyst John Difucci from Guggenheim confirms a Buy rating for ServiceNow, maintaining the price target at $657.
- Mark Murphy from JP Morgan retains an Overweight rating for ServiceNow, and raises the price target from $600 to $620.
- Brian Schwartz, an analyst from Oppenheimer, reaffirms an Outperform rating, keeping the price target at $640.
- Keith Bachman from BMO Capital sustains an Outperform rating for ServiceNow, and increases the price target from $515 to $630.
- Michael Turrin, an analyst from Wells Fargo, maintains an Overweight rating, and boosts the price target from $625 to $650.
- Raimo Lenschow from Barclays continues with an Overweight rating, but slightly reduces the price target from $646 to $644.
- Samad Samana from Jefferies holds a Buy rating, and uplifts the price target from $525 to $650.
- Jackson Ader, an analyst from MoffettNathanson, keeps an Outperform rating, and hikes the price target from $549 to $600.
- Jack Andrews from Needham reiterates a Buy rating, holding steady on the price target at $660.
- Alex Zukin from Wolfe Research, Rob Oliver from Baird, Karl Keirstead from UBS, Matthew Hedberg from RBC Capital, and Richard Davis from Canaccord Genuity, also increase their price targets to $670, $650, $650, $665, and $625, respectively.
Analyst Gregg Moskowitz (MIZUHO) has currently the highest performing score on NOW with 25/27 (92.59%) price target fulfillment ratio. His price targets carry on average an $47.97 (10.88%) potential upside. ServiceNow stock price reaches these price targets on average within 85 days
Daily stock Analysts Top Price Moves Snapshot
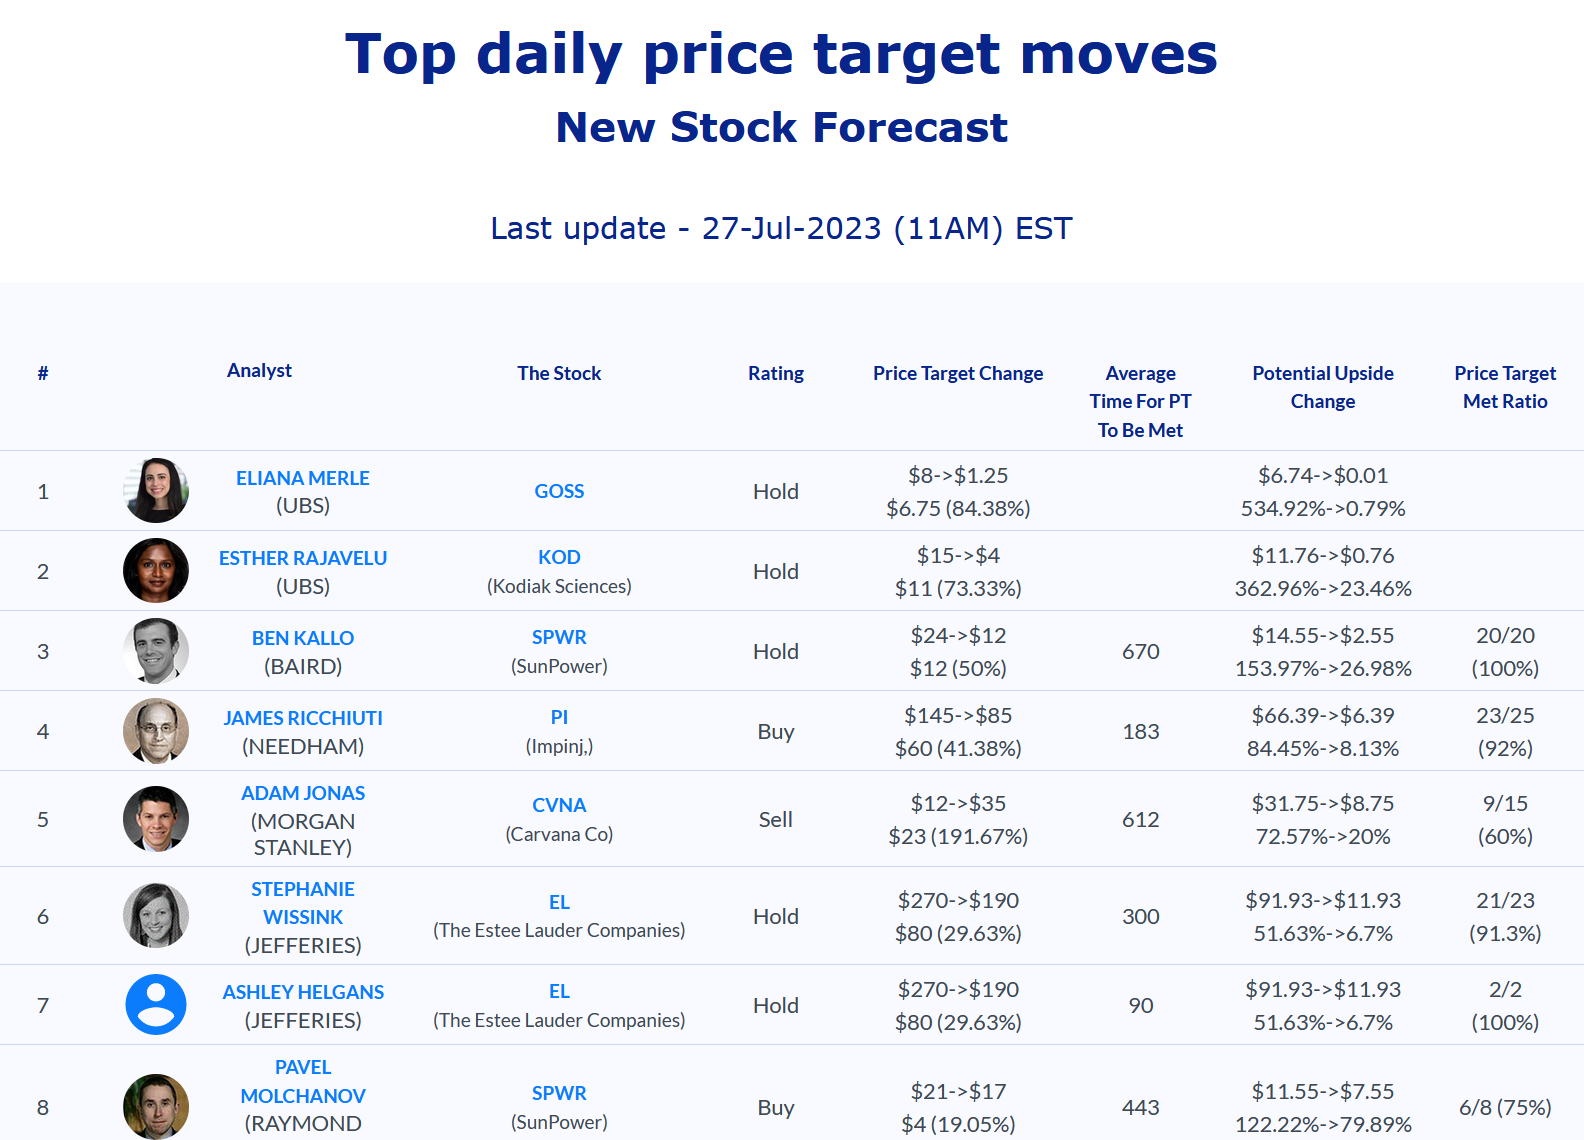
July 28, 2023: Selected stock price target news of the day: July 28, 2023
By: Matthew Otto
McDonald's Reports Global Sales Increase of 11.7%
McDonald's has reported robust second quarter results for 2023, The report highlights that the global comparable sales increased by 11.7% for the quarter. This growth spanned across all segments: U.S. sales saw an increase of 10.3%, International Operated Markets segment grew by 11.9%, and the International Developmental Licensed Markets segment jumped up by 14.0%.
In terms of digital sales, the company has reported over $8 billion for the quarter in its top six markets. This figure accounted for nearly 40% of systemwide sales in these markets, demonstrating the strength of McDonald's digital strategy.
The consolidated revenues increased by 14% and systemwide sales saw an increase of 12%. Further, the report shows a surge in the consolidated operating income, which increased by 81%. This sharp increase was partly attributed to McDonald's internal effort to modernize its ways of working, which they referred to as 'Accelerating the Organization'.
The report showed that the diluted earnings per share were at $3.17, marking an increase of 97%. This figure showed a 24% increase and was significantly higher than the estimated $2.78 per share.
In terms of total sales, McDonald's brought in $6.5 billion, which was higher than the projected $6.3 billion. The company attributes the growth in same-store sales to strategic menu price increases and a high volume of diners. Interestingly, McDonald's revealed that it has gained market share among higher-income consumers.
However, the company also observed a trend of reduced ordering from lower-income customers due to increased price sensitivity. This trend might pose challenges to McDonald's ability to continue raising prices in future. In spite of these potential headwinds, McDonald's was able to raise its projections for the fiscal year 2023 operating margin to about 46% from about 45%.
Wall Street Analysts Keep their Recommendations on McDonald
- Stephens & Co. analyst Joshua Long has reiterated an Overweight rating and a price target of $325.
- Wedbush analyst Nick Setyan has also maintained an Outperform rating and a price target of $330.
- John Ivankoe, an analyst from JPMorgan, has raised the price target for McDonald's to $320.
Analyst Brian Mullan (DEUTSCHE BANK) has currently the highest performing score on MCD with 19/19 (100%) price target fulfillment ratio. His price targets carry on average an $18.54 (8.98%) potential upside. McDonald's stock price reaches these price targets on average within 179 days.
Southwest Sees Lower Revenue Margins Next Year
Southwest Airlines has reported its Q2 2023 financial results. The company posted a net income of $683 million, or $1.08 per diluted share, and excluding special items, a net income of $693 million, or $1.09 per diluted share which is in-line with forecasts from analysts surveyed by FactSet, but lower than earnings of $1.30 per share it saw a year ago. The airline achieved record quarterly operating revenues of $7.04 billion which is over Wall Street estimates of $6.98 billion. The company's liquidity stood at $13.2 billion, significantly higher than its debt outstanding of $8.0 billion.
Southwest Airlines also expects a pre-tax profit contribution in full year 2023 ranging from $1.0 billion to $1.5 billion. The company projects an incremental year-over-year pre-tax profit of approximately $500 million, thanks to network optimization efforts and the continued maturation of development markets.
In the company's financial guidance, the company expects third-quarter 2023 RASM (Revenue per Available Seat Mile) to decrease by 3% to 7% year-over-year, and the economic fuel costs per gallon to be in the range of $2.55 to $2.65 and available seat miles, or capacity, to rise 12% year over year in the quarter. Indicating lower profitability in its outlook.
Analysts Adjust Ratings and Price Targets on Southwest Airlines Following Q2 2023 Financial Results
- Raymond James' analyst, Savanthi Syth, has downgraded from a Strong Buy to Outperform, concurrently lowering the price target from $47 to $40.
- Deutsche Bank's analyst Michael Linenberg has moved from a Buy to a Hold rating, while decreasing the price target from $52 to $38.
- BofA Securities' analyst Andrew Didora has downgraded from Buy to Neutral, in addition to lowering the price target from $45 to $35.
Analyst Jamie Baker (JPMORGAN) has currently the highest performing score on LUV with 14/21 (66.67%) price target fulfillment ratio. His price targets carry on average an $7.13 (19.07%) potential upside. Southwest Airlines stock price reaches these price targets on average within 199 days.
First Solar Beats Q2 2023 Expectations; Announces $1.1B Investment for New US Manufacturing Facility
First Solar has announced its Q2 2023 financial results, beating analysts' expectations. The company reported net sales of $811 million, a figure notably higher than the forecasted $711 million. This increase was primarily driven by a rise in the volume of modules sold and an increase in the average selling price of its modules.
The net income per diluted share for the quarter was reported at $1.59, an increase from $0.40 in Q1 2023.
Commenting on the company's performance, CEO Mark Widmar noted the firm's strengthened commercial, operational, and financial foundations, marked by a ramp-up in the production of its next-generation Series 7 modules and strong bookings. Widmar also announced a planned investment of up to $1.1 billion in a new 3.5 GW Series 7 US manufacturing facility, marking the company's fifth such facility in the country.
The company's 2023 guidance has been updated, with operating expenses now expected to range between $450 million and $475 million. The net cash balance is anticipated to be between $1.5 billion and $1.8 billion, and capital expenditures are projected at $1.7 billion to $1.9 billion. Other metrics remained unchanged.
Baird Adjusts Its Price Target on First Solar
- Baird analyst Ben Kallo raised the price target for First Solar to $229. Indicating a change from his trend in the last year by carrying potential upside.
Analyst Gordon Johnson (GLJ) has currently the highest performing score on FSLR with 4/9 (44.44%) price target fulfillment ratio. His price targets carry on average an $-24.36 (-23.55%) potential downside. First Solar stock price reaches these price targets on average within 54 days.
Daily stock Analysts Top Price Moves Snapshot

July 31, 2023: Selected stock price target news of the day: July 31, 2023
By Matthew Otto
Oatly comes short on Wall Street Expectations
Oatly Group announced its financial results for the second quarter and six months ended June 30, 2023. Although the company made steady progress towards its goal of achieving profitable growth by 2024, the financial results fell short of analysts expectations.
The company reported Q2 2023 earnings per share (EPS) of ($0.15), which was $0.03 worse than the analyst estimate of ($0.12). The reported revenue for the quarter was $196 million, significantly below the consensus estimate of $210.59 million.
Oatly reported a gross margin of 19.2% for the quarter, a substantial increase compared to the same period in the previous year. However, the company recorded a net loss attributable to shareholders of $86.7 million, which was an increase from a net loss of $72.0 million in Q2 2022.
During the quarter, Oatly successfully raised $465 million from financing transactions. The company also initiated a comprehensive improvement plan in Asia, a region where consumer behavior in the post-pandemic era did not align with the company's expectations. Additionally, Oatly plans to simplify its corporate functions and decrease overhead in its Americas segment, an action expected to bring about savings of approximately $85 million in 2024.
The company now forecasts a revenue growth on a constant currency basis in the range of 7% to 12% compared to the full year 2022
Oatly Faces Analysts' Downgrades and Price Target Adjustments Amid Q2 Performance
- Barclays' Andrew Lazar decided to retain his Overweight stance on Oatly, though he curtailed the price target from $3 to $2.
- RBC Capitals Nik Modi adjusted his rating for Oatly, downgrading from Outperform to Sector Perform.
- Truist Securities Bill Chappell revised his price target for Oatly downwards to $3.
Analyst John Baumgartner (MIZUHO) has currently the highest performing score on OTLY with 3/6 (50%) price target fulfillment ratio. His price targets carry on average an $1.69 (67.53%) potential upside. Oatly stock price reaches these price targets on average within 15 days.
Charter Reports Q2 2023 Earnings, Misses Analyst Estimates on EPS and Revenue
Charter Communications reported its financial and operating results for Q2 2023. Total residential and small and medium business ("SMB") internet customers rose by 77,000 during the quarter, boosting Charter's overall customer base to 30.6 million. Additionally, residential and SMB mobile lines saw a significant increase, with an added 648,000 lines leading to a total of 6.6 million mobile lines as of June 30, 2023.
Although Charter reported an EPS of $8.05. It fell short of analyst estimates by $0.02, which were expected to hit $8.07. Despite this minor deviation from projections, the company's overall performance demonstrated a healthy expansion with robust revenue figures. However, Charter's Q2 2023 revenue of $13.66 billion slightly underperformed the consensus estimate of $13.84 billion.
The company's total Q2 revenue grew by 0.5% year-over-year, amounting to $13.7 billion. This expansion was primarily driven by residential internet revenue growth of 3.1%, residential mobile service revenue growth of 29.8%, and other revenue growth of 28.5%. The revenue surge was mainly attributed to higher mobile device sales. However, Charter's net income attributable to shareholders for Q2 was $1.2 billion. During Q2 2023, Charter repurchased 1.1 million shares.
While Charter's residential internet customer base saw growth, the residential video customer base experienced a decrease by 189,000 in the second quarter of 2023. This downtick contrasts with a decline of 240,000 in Q2 2022. As of June 30, 2023, Charter had 14.1 million residential video customers.
The company continues to evolve its services and is set to deploy Xumo-branded streaming devices in late 2023. Additionally, residential wireline voice customers saw a decline of 225,000 during the second quarter of 2023. As of June 30, 2023, Charter had 7.2 million residential wireline voice customers.
Multiple Analysts Adjust Price Targets on Charter Communications Following Q2 Earnings Report
- Steven Cahall of Wells Fargo held steady with an Equal-Weight rating while elevating the price target from $410 to $450.
- Barclays analyst Kannan Venkateshwar stood firm with an Underweight rating on Charter, but boosted the price target from $273 to $325.
- Jessica Reif of BofA Securities advanced her price target to $450.
- Brett Feldman from Goldman Sachs escalated his price target to $510.
Analyst Steven Cahall (WELLS FARGO) has currently the highest performing score on CHTR with 11/12 (91.67%) price target fulfillment ratio. His price targets carry on average an $16 (2.33% potential upside. Charter Communications stock price reaches these price targets on average within 66 days.
Procter & Gamble Beats Q4 Estimates Despite Challenges in China; U.S. Demand Remains Strong
Procter & Gamble delivered a better-than-expected performance in its Q4 report, despite the headwinds presented by weak demand in China. The company surpassed analysts' sales and profit estimates, largely bolstered by several price increases it implemented.
China's slower-than-anticipated recovery post-pandemic has impacted numerous global companies, including L'Oreal and Coca-Cola, which are experiencing slowing demand across various regions. For P&G, total volumes decreased by 1% in Q4, largely attributed to weak demand in Greater China, while the average prices across P&G's products grew by 7%.
Interestingly, China, being P&G's second largest market after the U.S., had cushioned volume declines in the third quarter. Jason Benowitz, Senior Portfolio Manager at CI Roosevelt. Anticipates that the company's business in China will continue to be a significant variable in fiscal 2024. Given the current macroeconomic backdrop which brings increased forecasting difficulties.
Meanwhile, P&G is witnessing robust demand for its products such as Pampers diapers, Pantene shampoo. Oral-B toothpaste in the U.S., where consumer sentiment is reaching a two-year peak as inflation eases. The company's CFO, Andre Schulten, revealed a positive volume growth of 3% in the U.S. business.
P&G projects profit per share growth for fiscal 2024 to be in the range of 6% to 9%, which is approximately between $6.25 and $6.43, against analysts' predictions of $6.38. Despite supply chain and input costs showing stability as fiscal 2024 commences.
Despite the challenges, P&G's Q4 net sales increased by 5% to $20.55 billion, exceeding analysts' expectations of $19.98 billion. On an adjusted basis, the company reported earnings of $1.37 per share, surpassing the estimate of $1.32.
Analysts Update Price Targets on P&G
- Chris Carey from Wells Fargo maintains an Overweight rating, lifting the price target from $165 to $170.
- Deutsche Bank's Steve Powers holds a Buy position, revising the price target upward from $170 to $173.
- Robert E. Ottenstein of Evercore ISI has increased the price target to $175.
- RBC Capital analyst Nik Modi has raised the price target to $167.
- Edward Lewis from Atlantic Equities retains an Overweight rating and nudges the price target from $175 to $176.
Analyst Peter Grom (UBS) has currently the highest performing score on PG with 2/5 (40%) price target fulfillment ratio. His price targets carry on average an $14.6 (10.62%) potential upside. Procter & Gamble stock price reaches these price targets on average within 40 days.
Daily stock Analysts Top Price Moves Snapshot