
The analyst price target moves we wrote up each trading day in May 2025, 21 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
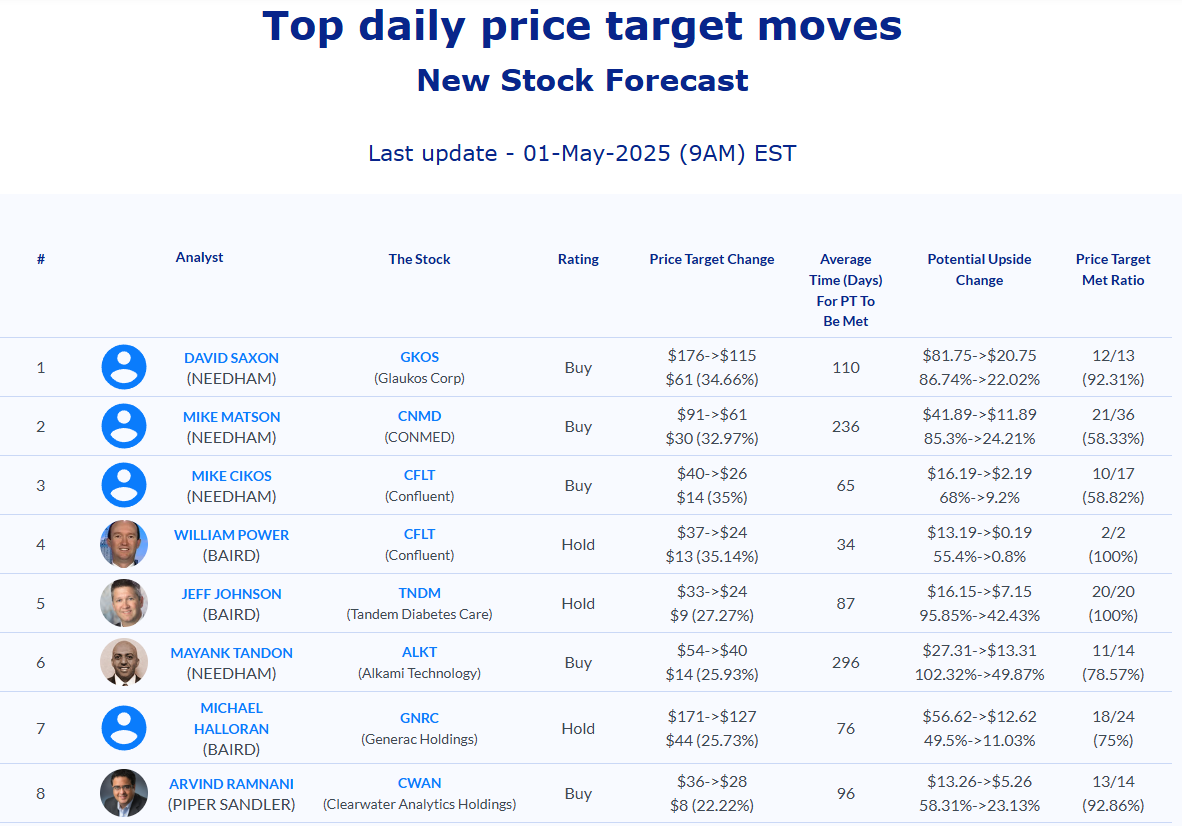
May 1, 2025: Analyst Price Target News: Meta, Microsoft, eBay (May 1st, 2025)
By: Matthew Otto
Meta Beats Q1 Expectations, Guides Higher Despite Ongoing Reality Labs Losses
Meta Platforms reported earnings per share (EPS) of $6.43, exceeding the consensus estimate of $5.24 by $1.19. Revenue reached $42.31 billion, surpassing analyst expectations of $41.48 billion and marking a 16% increase year-over-year.
Net income grew 35% to $16.64 billion, while operating income rose 27% to $17.56 billion, lifting the operating margin from 38% to 41%. Meta’s advertising business remained with a 5% increase in ad impressions and a 10% rise in average price per ad. Family daily active people hit 3.43 billion in March, up 6% year-over-year.
Meta also returned capital to shareholders with $13.40 billion in share repurchases and $1.33 billion in dividends. Meta ended the quarter with $70.23 billion in cash and equivalents, and free cash flow of $10.33 billion. Looking ahead, Meta forecasts Q2 revenue between $42.5 billion and $45.5 billion, bracketing the consensus estimate of $43.3 billion.
Meta’s Reality Labs division continues to weigh on results, posting an operating loss of $4.2 billion on revenue of $412 million in Q1. The unit, which oversees Meta’s VR and AR initiatives, has now accumulated over $60 billion in losses since late 2020. Although analysts had anticipated a slightly higher loss of $4.6 billion, they also expected stronger revenue of $492.7 million.
Analysts Lift Price Targets Following Q1 Beat and Upbeat Guidance
- UBS analyst Lloyd Walmsley maintained a Buy rating and lifted the price target from $650 to $683.
- Citigroup analyst Ronald Josey reiterated a Buy rating and boosted the price target from $655 to $690.
- JP Morgan analyst Doug Anmuth kept an Overweight rating and raised the price target from $610 to $675.
- Needham analyst Laura Martin reiterated an Underperform rating.
Which Analyst has the best track record to show on META?
Analyst Nat Schindler (SCOTIABANK) currently has the highest performing score on META with 4/4 (100%) price target fulfillment ratio. His price targets carry an average of $40.34 (8.32%) potential upside. Meta Platforms stock price reaches these price targets on average within 13 days.
eBay Reports Q1 2025 Earnings Above Expectations, Issues Mixed Q2 Guidance
eBay reported first quarter 2025 revenue of $2.6 billion, slightly ahead of the consensus estimate of $2.55 billion and representing a 1% increase year-over-year (2% on a currency-neutral basis). Gross Merchandise Volume (GMV) totaled $18.8 billion, also up 1% as reported and 2% when adjusted for foreign exchange.
Net income from continuing operations was $505 million, with diluted earnings per share of $1.06. On an adjusted basis, earnings per share reached $1.38, exceeding analyst expectations by $0.04. Operating cash flow for the quarter was $787 million, with $644 million in free cash flow. Operating margins were reported at 23.8%, with an adjusted margin of 29.8%.
Advertising revenue totaled $442 million, with $418 million generated from first-party ad products—up 13% year-over-year. eBay also partnered with Meta to extend reach through Facebook Marketplace and collaborated with OpenAI on a virtual shopping assistant.
For the second quarter of 2025, eBay expects earnings per share between $1.24 and $1.31, compared to the analyst consensus of $1.28. Revenue guidance was set between $2.59 billion and $2.66 billion, roughly in line with the consensus of $2.59 billion.
Analysts Lift Price Targets Following Q1 Results
- Evercore ISI Group analyst Mark Mahaney maintained an In-Line rating and raised the price target from $63 to $69.
- Baird analyst Colin Sebastian reiterated an Outperform rating and increased the price target from $68 to $75.
- Needham analyst Bernie McTernan kept a Buy rating and lifted the price target from $72 to $78.
Which Analyst has the best track record to show on EBAY?
Analyst Deepak Mathivanan (CANTOR FITZGERALD) currently has the highest performing score on EBAY with 7/8 (87.5%) price target fulfillment ratio. His price targets carry an average of $6.52 (10.27%) potential upside. eBay stock price reaches these price targets on average within 98 days.
Microsoft Reports Q3 Earnings Above Expectations; Azure and AI Drive Growth
Microsoft reported fiscal third-quarter earnings per share of $3.46, surpassing the consensus estimate of $3.23 by $0.23. Revenue totaled $70.1 billion, compared to analyst expectations of $68.53 billion.
Cloud revenue reached $42.4 billion, with the Intelligent Cloud segment contributing $26.8 billion, up 21% year-over-year. Azure revenue increased 33%, exceeding the projected 29.7%, with AI-related services accounting for 16 percentage points of that growth, compared to 13 points in the previous quarter.
Microsoft forecast constant-currency Azure growth of 34% to 35% in the fiscal fourth quarter, implying cloud revenue between $28.75 billion and $29.05 billion. Commercial bookings rose 18% from the prior year, driven in part by a new contract with OpenAI. Total company revenue grew 13% year-over-year.
Capital expenditures rose 53% year-over-year to $21.4 billion. The share of spending on longer-lived assets declined to approximately 50%, reflecting a reallocation toward shorter-lived assets such as semiconductors. Microsoft indicated that in fiscal 2026, capex will continue to rise but at a slower rate. CPUs and GPUs from suppliers including Intel, AMD, and Nvidia are central to this shift.
Analysts Raise Price Targets Following Q3 Cloud and AI Performance
- Evercore ISI Group analyst Kirk Materne maintained an Outperform rating and raised the price target from $435 to $500.
- JP Morgan analyst Mark Murphy kept an Overweight rating and increased the price target from $465 to $475.
- WestPark Capital analyst Curtis Shauger reiterated a Hold rating.
- Piper Sandler analyst Brent Bracelin maintained an Overweight stance while lifting the price target from $435 to $475.
Which Analyst has the best track record to show on MSFT?
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on MSFT with 26/28 (92.86%) price target fulfillment ratio. His price targets carry an average of $60.27 (14.89%) potential upside. Microsoft stock price reaches these price targets on average within 117 days.
Daily stock Analysts Top Price Moves Snapshot
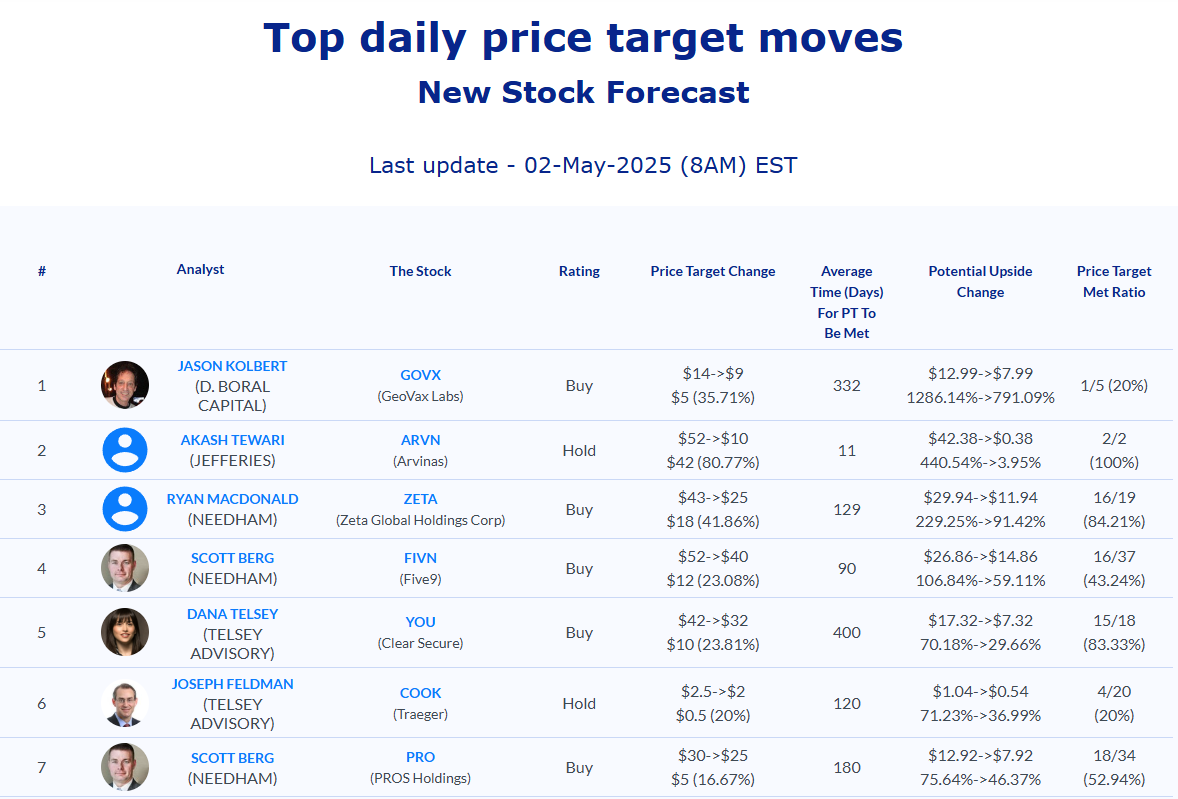
May 2, 2025: Analyst Price Target News: Apple, Amazon (May 2nd, 2025)
By: Matthew Otto
Apple Beats Q2 Estimates with Record EPS and Services Revenue Amid Rising Tariff Costs
Apple reported fiscal second-quarter results for the period ended March 29, 2025, delivering earnings per share (EPS) of $1.65, a $0.04 ahead of the consensus estimate of $1.61. Reported a revenue of $95.36 billion, topping the $94.22 billion expected by analysts. This represents a 5% year-over-year increase in revenue and an 8% rise in EPS.
Net income rose to $24.78 billion from $23.64 billion in the same quarter last year. iPhone sales reached $46.84 billion, beating expectations by $1 billion, while Mac and iPad revenues rose to $7.95 billion and $6.4 billion, respectively. Services revenue at $26.65 billion, up 11.65% year over year, though slightly below expectations. Gross margin remained stable at 47.1%, and operating cash flow came in at $24 billion.
CEO Tim Cook acknowledged rising cost pressures, noting that tariffs are expected to add $900 million in expenses in the June quarter. CFO Kevan Parekh projected revenue growth in the “low to mid-single digits” and a gross margin of approximately 46% for Q3. Regional performance was mixed, with Greater China revenue slightly lower at $16 billion, while the Americas grew nearly 8%.
Analysts Mixed Ratings as Q2 Results Outperform but Risks Emerge
- Jefferies analyst Edison Lee downgraded from Hold to Underperform but raised the price target from $167.88 to $170.62.
- DA Davidson analyst Gil Luria reaffirmed a Buy rating and boosted the price target from $230 to $250.
- Needham analyst Laura Martin reiterated Buy rating and a $225 price target.
- Rosenblatt analyst Barton Crockett shifted from Buy to Neutral and assigned a $217 price target.
- Citi analyst Atif Malik maintained a Buy rating but lowered the price target from $245 to $240.
- Morgan Stanley analyst Erik Woodring reiterated an Overweight rating and the price target at $235.
Which Analyst has the best track record to show on AAPL?
Analyst David Vogt (UBS) currently has the highest performing score on AAPL with 34/35 (97.14%) price target fulfillment ratio. His price targets carry an average of $5.4 (2.64%) potential upside. Apple stock price reaches these price targets on average within 160 days.
Amazon Tops Q1 2025 Earnings Estimates but AWS Growth and Q2 Guidance Stir Caution
Amazon.com reported first-quarter 2025 earnings per share (EPS) of $1.59, surpassing analyst expectations by $0.22. Revenue for the quarter reached $155.7 billion, slightly ahead of the $155.29 billion consensus estimate and up 9% year-over-year, or 10% on a constant currency basis. Operating income rose to $18.4 billion from $15.3 billion in Q1 2024. Net income jumped to $17.1 billion, compared to $10.4 billion a year ago.
AWS revenue increased 17% to $29.3 billion. Regionally, North America sales climbed 8% to $92.9 billion, and international segment sales grew 5% to $33.5 billion (8% adjusted for FX). Advertising revenue grew 19% year-over-year to $13.92 billion, while operating cash flow for the trailing twelve months rose 15% to $113.9 billion. Free cash flow declined to $25.9 billion from $50.1 billion.
For the second quarter of 2025, Amazon guided for net sales between $159.0 billion and $164.0 billion, representing 7% to 11% year-over-year growth and bracketing the consensus estimate of $161 billion. Amazon expects a roughly 10 basis point negative impact from foreign exchange rates. Operating income is forecasted between $13.0 billion and $17.5 billion, compared to $14.7 billion in Q2 2024 and below the average analyst estimate of $17.7 billion.
Analysts Stay Bullish Following Q1 Beat Despite Cautious Outlook
- JP Morgan analyst Doug Anmuth maintained an Overweight rating and raised the price target from $220 to $225.
- Needham analyst Laura Martin reiterated a Buy rating and a $220 price target.
- Telsey Advisory Group analyst Joseph Feldman maintained an Outperform rating and a $235 price target.
Which Analyst has the best track record to show on AMZN?
Analyst Barton Crockett (ROSENBLATT) currently has the highest performing score on AMZN with 12/13 (92.31%) price target fulfillment ratio. His price targets carry an average of $57.85 (25.25%) potential upside. Amazon.com stock price reaches these price targets on average within 151 days.
iRhythm Reports Q1 2025 Financial Performance with Increased Revenue and Gross Margin
iRhythm Technologies reported its financial results for the first quarter of 2025, with revenue reaching $158.7 million, a 20.3% increase compared to $131.9 million in the same period of 2024. This result surpassed the consensus estimate of $153.49 million.
Gross profit for the quarter was $109.2 million, reflecting a 24.8% increase from the prior year’s $87.5 million, while gross margin improved to 68.8%, up 250 basis points from 66.3% in Q1 2024. iRhythm reported a net loss of $30.7 million, or a diluted loss of $0.97 per share, compared to a net loss of $45.7 million, or a diluted loss of $1.47 per share, in Q1 2024.
Adjusted net loss for the quarter was $30.3 million, a slight improvement from the adjusted net loss of $38.1 million in the same period of 2024. Additionally, iRhythm exceeded analyst expectations with Q1 EPS of ($0.95), beating the consensus estimate of ($0.96).
For the full year 2025, iRhythm has raised its revenue guidance to a range of $690 million to $700 million, surpassing the consensus estimate of $681.7 million. iRhythm expects its adjusted EBITDA margin for FY2025 to range between 7.5% and 8.5% of revenues. Operating expenses for the first quarter of 2025 were $141.8 million, up from $125.7 million in Q1 2024.
Analysts Raise Price Targets Following Q1 2025 Results
- HC Wainwright & Co. analyst Mike Colonnese maintained a Buy rating and raised the price target from $480 to $521.
- Canaccord Genuity analyst Joseph Vafi maintained a Buy rating while increasing the price target from $409 to $464.
- BTIG analyst Marie Thibault kept a Buy rating and raised the price target from $135 to $140.
Which Analyst has the best track record to show on IRTC?
Analyst David Roman (GOLDMAN SACHS) currently has the highest performing score on IRTC with 2/3 (66.67%) price target fulfillment ratio. His price targets carry an average of $11.33 (10.06%) potential upside. iRhythm Technologies stock price reaches these price targets on average within 11 days.
Daily stock Analysts Top Price Moves Snapshot
May 5, 2025: Analyst Price Target News: Airbnb, Wendy’s (May 5th, 2025)
This week in analyst price targets: Airbnb delivered in-line Q1 results but issued a cautious Q2 forecast, drawing mixed analyst revisions. Wendy's reported Q1 global sales decline with continued net unit growth.
By: Matthew Otto
Wendy’s Reports Q1 2025 Results: Global Sales Decline, Continued Net Unit Growth
The Wendy’s Company reported global systemwide sales of $3.4 billion for the first quarter ended March 30, 2025, representing a 1.1% year-over-year decrease. This decline was primarily driven by a 2.6% drop in U.S. systemwide sales, partially offset by 8.9% growth in international markets.
Same-restaurant sales declined 2.1% globally, with the U.S. down 2.8% and international up 2.3%. Wendy’s opened 74 new restaurants and added 68 net new units, bringing its global restaurant count to 7,308. Digital sales mix increased to a record 20.3%. Total revenue for the quarter was $523.5 million, slightly below the consensus estimate of $529.7 million and down 2.1% from the prior year. U.S. company-operated restaurant margin declined 50 basis points to 14.8%, due to commodity inflation and lower traffic. General and administrative expenses rose 6.9% to $68.2 million.
Reported diluted earnings per share were $0.2, in line with analyst expectations, while adjusted EPS decreased 13% year-over-year. Adjusted EBITDA declined 2.6% to $124.5 million. Free cash flow increased 21.4% to $68 million, while cash flow from operations declined 14.6% to $85.4 million. Wendy’s returned $173.5 million to shareholders through dividends and share repurchases, including 8.2 million shares repurchased in the first quarter.
Wendy’s reaffirmed its full-year 2025 outlook for 2 to 3% global net unit growth and $100 to $110 million in capital expenditures but lowered its full-year EPS guidance to $0.92 to $0.98, below the current analyst consensus of $1. Full-year adjusted EBITDA is expected between $530 to $545 million, and free cash flow is projected at $250 to $270 million, excluding expenditures related to the franchise development fund.
Analysts Revise Ratings and Targets After Q1 Results and Outlook
- JP Morgan analyst John Ivankoe upgraded from Neutral to Overweight but reduced the price target from $17 to $15.
- Stephens & Co. analyst Jim Salera reiterated an Equal-Weight rating and a $14 price target.
- Evercore ISI analyst David Palmer trimmed the price target from $16 to $15.
- Loop Capital analyst Alton Stump lowered the price target from $21 to $15.
Which Analyst has the best track record to show on WEN?
Analyst Andrew Charles (TD SECURITIES) currently has the highest performing score on WEN with 10/16 (62.5%) price target fulfillment ratio. His price targets carry an average of $0.45 (3.59%) potential upside. The Wendy’s Company stock price reaches these price targets on average within 106 days.
Airbnb Delivers In-Line Q1 Results but Issues Cautious Q2 Forecast
Airbnb reported first-quarter earnings per share (EPS) of $0.24, beating the consensus estimate of $0.23 by $0.01. Revenue came in at $2.27 billion, slightly above the expected $2.26 billion, and up 6% from $2.1 billion a year earlier. Net income fell to $154 million, or $0.24 per share, compared to $264 million, or $0.41 per share, in Q1 2023.
Gross booking value grew 7% year over year to $24.5 billion, in line with estimates, while total nights and experiences booked rose 8% to 143.1 million, just under the 143.4 million forecasted. Growth outside North America was strong, with an 11% year-over-year increase in nights and experiences. Notably, Canadian guest bookings to Mexico surged 27% in March.
For Q2 2025, Airbnb issued revenue guidance of $2.99 billion to $3.05 billion, placing the midpoint ($3.02 billion) slightly below the consensus estimate of $3.03 billion. Airbnb has also removed 450,000 listings following updates to its host quality system in 2023 and teased new platform features expected to roll out later this month.
Analyst Lowers Price Target 150 Amid Mixed Q1 Results and Soft Q2 Outlook
- Susquehanna analyst Shyam Patil maintained a Positive rating but lowered the price target from $200 to $150.
Which Analyst has the best track record to show on ABNB?
Analyst Doug Anmuth (JPMORGAN) currently has the highest performing score on ABNB with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $9.31 (8.81%) potential upside. Airbnb stock price reaches these price targets on average within 37 days.
Ascendis Pharma Reports Q1 2025 Results: Revenue Beats Estimates, EPS Misses
Ascendis Pharma announced its financial results for the first quarter ended March 31, 2025, reporting total revenue of $108.6 million, exceeding the consensus estimate of $100.6 million. The increase was driven by $103.3 million in commercial product revenue, including $55.3 million from SKYTROFA® and $48.1 million from YORVIPATH®.
YORVIPATH revenue grew from $1.6 million in Q1 2024 following its U.S. launch, while SKYTROFA declined year-over-year from $70.1 million. Non-product revenue dropped to $5.3 million from $31.7 million in the prior-year quarter.
Ascendis reported a net loss of $101.8 million, or $(1.58) per share, which was $0.12 worse than the analyst estimate of $(1.47). Total operating expenses rose to $201.8 million, up from $147.7 million in Q1 2024. As of March 31, 2025, Ascendis had cash and cash equivalents of $557.7 million, down from $602.6 million at year-end 2024.
Analyst Upgrades Rating and Price Target Following Q1 2025 Results
- Morgan Stanley analyst Vikram Purohit upgraded from Equal-Weight to Overweight and the price target from $180 to $250.
Which Analyst has the best track record to show on ASND?
Analyst Jessica Fye (JPMORGAN) currently has the highest performing score on ASND with 19/23 (82.61%) price target fulfillment ratio. Her price targets carry an average of $72.94 (42.39%) potential upside. Ascendis Pharma stock price reaches these price targets on average within 145 days.
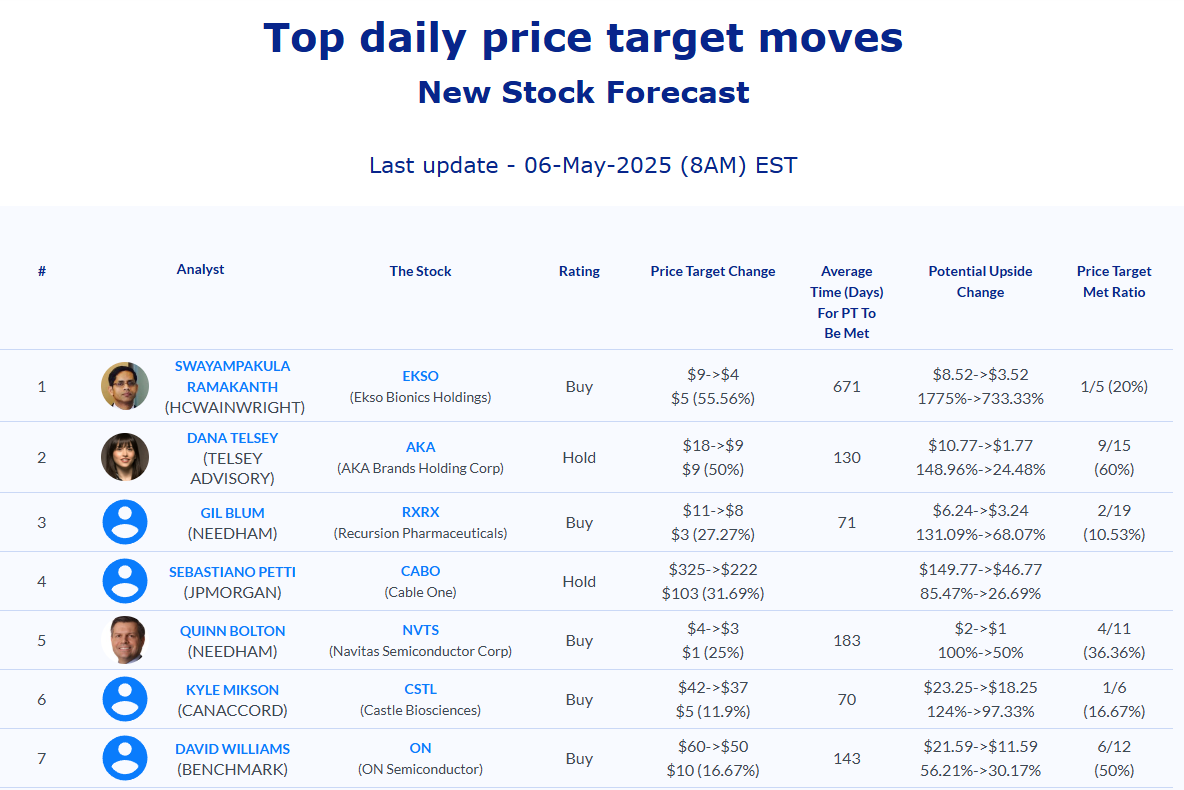
Daily stock Analysts Top Price Moves Snapshot

May 6, 2025: Analyst Price Target News: onsemi, Vertex Pharmaceuticals (May 6th, 2025)
This week in analyst price targets: onsemi reported a 20% revenue decline in Q1 while free cash flow rose 72%, drawing mixed analyst responses. Vertex Pharmaceuticals reported Q1 2025 results and revised its full-year revenue guidance.
By: Matthew Otto
onsemi Reports 20% Revenue Decline as Free Cash Flow Rises 72% in First Quarter
onsemi reported first quarter 2025 revenue of $1,445.7 million, a decline from $1,862.7 million in the same quarter a year ago and $1,722.5 million in the previous quarter. Free cash flow reached $455 million, up 72% year-over-year and accounting for 31% of total revenue.
onsemi returned approximately $300 million to stockholders through share repurchases, representing 66% of its free cash flow. Cash from operations totaled $602 million, and net income stood at $231.6 million. It recorded a gross margin of 40% and an operating margin of 18.3%, both below the 45.9% and 29% reported in the first quarter of 2024.
Revenue by segment also showed year-over-year and sequential declines. Power Solutions Group (PSG) revenue fell to $645.1 million, down 26% year-over-year and 20% sequentially. Advanced Solutions Group (AMG) posted $566.4 million, down 19% from the prior year. Intelligent Sensing Group (ISG) reported $234.2 million, reflecting a 20% year-over-year drop.
For the second quarter of 2025, onsemi forecasts revenue between $1,400 million and $1,500 million. Expected gross margin is between 36.5% and 38.5%, with operating expenses ranging from $285 million to $300 million. Net other expense, including interest, is projected at $11 million.
Analysts Lower Price Targets Following Q1 Results and Revenue Decline
- Benchmark analyst David Williams maintained a Buy rating but reduced the price target from $60 to $50.
- Needham analyst Quinn Bolton kept a Buy rating while trimming the price target from $57 to $50.
- Baird analyst Tristan Gerra lowered the price target from $42 to $34.
Which Analyst has the best track record to show on ON?
Analyst Anthony Stoss (CRAIG HALLUM) currently has the highest performing score on ON with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $2.07 (4.32%) potential upside. ON Semiconductor stock price reaches these price targets on average within 341 days.
BioCryst Posts Better-Than-Expected Q1 2025 Results and Raises Full-Year Revenue Guidance
BioCryst Pharmaceuticals reported total revenue of $145.5 million for the first quarter ended March 31, 2025, a 56.8% increase from $92.8 million in the same period last year. ORLADEYO® (berotralstat) net revenue totaled $134.2 million, up 51% from $88.9 million in Q1 2024, and exceeded the consensus estimate of $127.91 million. U.S. sales represented 89.5% of ORLADEYO revenue.
ORLADEYO is an oral, once-daily treatment to prevent hereditary angioedema (HAE) attacks. HAE is a rare genetic disorder that affects an estimated 1 in 50,000 people, or roughly 8,000 to 10,000 individuals in the U.S. alone. ORLADEYO offers a non-injectable option, with 84% of patients now on paid drug. BioCryst has filed to expand its use to children aged 2 to 11 via oral granules, which could extend access to a broader pediatric population.
BioCryst reported Q1 2025 earnings per share (EPS) of $0, $0.07 above the analyst estimate of ($0.07), compared to a net loss of $35.4 million, or ($0.17) per share, in Q1 2024. Operating income was $21.2 million, versus an operating loss of $14.5 million a year earlier. On a non-GAAP basis, operating income was $42.6 million, compared to a loss of $0.8 million.
Research and development expenses declined 19.8% year-over-year to $37.3 million, down from $46.5 million, primarily due to the discontinuation of the Factor D programs. Selling, general and administrative expenses increased 38.7% to $82.5 million, compared to $59.5 million in Q1 2024. Interest expense was $23.5 million, down 4.1% from $24.5 million. Cash, cash equivalents, restricted cash, and investments totaled $317.3 million as of March 31, 2025, compared to $338.4 million a year earlier. Net cash utilization in Q1 2025 was $25.5 million.
In April 2025, BioCryst repaid $75 million of Pharmakon debt, which is expected to reduce total interest expense by approximately $23.5 million over the life of the loan. For full year 2025, BioCryst raised its ORLADEYO revenue guidance to $580 to $600 million, above both the prior range of $535 to $550 million and the consensus estimate of $563.6 million. Projected operating expenses are $440 to $450 million, not including stock-based compensation.
Analysts Maintain Ratings, Adjust Price Targets Following Q1 2025 Results
- HC Wainwright & Co. analyst Andrew Fein reiterated with a Buy rating and a $30 price target.
- Needham analyst Serge Belanger maintained a Buy rating and raised the price target from $15 to $17.
Which Analyst has the best track record to show on BCRX?
Analyst Brian Abrahams (RBC) currently has the highest performing score on BCRX with 17/24 (70.83%) price target fulfillment ratio. His price targets carry an average of $4.18 (61.29%) potential upside. BioCryst Pharmaceuticals stock price reaches these price targets on average within 513 days.
Vertex Pharmaceuticals Reports Q1 2025 Financial Results and Revises Full-Year Revenue Guidance
Vertex Pharmaceuticals reported first-quarter 2025 revenue of $2.77 billion, falling short of the consensus estimate of $2.86 billion. Earnings per share (EPS) for the quarter were $4.06, missing the analyst estimate of $4.26 by $0.20.
Trikafta® / Kaftrio® sales reached $2.53 billion, reflecting a 2% increase from the same period in 2024. However, revenue outside the U.S. declined by 5% year-over-year, primarily due to lower sales in Russia.
Trikafta® (Kaftrio® in Europe) is a triple-combination therapy from Vertex Pharmaceuticals used to treat cystic fibrosis (CF), a genetic disease that affects around 92,000 people worldwide. The therapy targets the defective Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) protein caused by gene mutations, particularly F508del. Trikafta® / Kaftrio® is approved for patients with at least one F508del mutation and can benefit approximately 90% of all CF patients.
For the full year, Vertex revised its 2025 revenue guidance to a range of $11.85 billion to $12 billion, up slightly from the previous estimate of $11.75 billion to $12 billion. Vetex’s total expenses for Q1 2025, which include research and development (R&D) and selling, general, and administrative (SG&A) costs, amounted to $2.6 billion, an increase from $2.2 billion in Q1 2024.
Analysts React to Q1 Miss and Outlook with Mixed Rating Changes
- Needham analyst Joseph Stringer maintained a Hold rating.
- Leerink Partners analyst David Risinger downgraded from Outperform to Market Perform and the price target from $550 to $503.
- Scotiabank analyst Greg Harrison lowered his price target to $442.
- Morgan Stanley analyst Terence Flynn raised the price target to $464.
Which Analyst has the best track record to show on VRTX?
Analyst Mohit Bansal (WELLS FARGO) currently has the highest performing score on VRTX with 16/18 (88.89%) price target fulfillment ratio. His price targets carry an average of $21.6 (4.93%) potential upside. Vertex Pharmaceuticals stock price reaches these price targets on average within 284 days.
Daily stock Analysts Top Price Moves Snapshot
May 7, 2025: Analyst Price Target News: Datadog, CCC Intelligent Solutions (May 7th, 2025)
This week in analyst price targets: Datadog faced rising costs despite Q1 revenue growth and an updated forecast, drawing cautious analyst revisions. CCC Intelligent Solutions reported Q1 revenue growth with guidance below consensus.
By: Matthew Otto
CCC Reports Q1 2025 Revenue Growth; EPS Matches Estimates, Guidance Below Consensus
CCC Intelligent Solutions Holdings reported first quarter 2025 revenue of $251.6 million, an 11% increase from $227.2 million in the same period last year. It is slightly ahead of the consensus estimate of $249.76 million.
CCC delivered earnings per share (EPS) of $0.08, matching analyst expectations. Gross profit for the quarter was $185 million, with a profit margin of 74%. Adjusted gross profit totaled $192.5 million, with a 77% margin. Operating income, excluding adjustments, was $85.3 million, compared to $84.1 million a year earlier. Net income on an adjusted basis was $54.5 million.
CCC generated $58.5 million in cash from operations and reported free cash flow of $43.6 million, up from $39.6 million a year ago. Total cash stood at $130.3 million as of March 31, 2025, with total debt at $998.5 million.
For the second quarter of 2025, CCC expects revenue between $255.5 million and $257.5 million, below the consensus estimate of $259.4 million. Full-year 2025 revenue is projected to range from $1.046 billion to $1.056 billion, in line with the lower end of consensus expectations. EBITDA guidance is $99.0 million to $101 million for Q2 and $420 million to $428 million for the full year.
Analysts React to Q1 Results with Diverging Views on Outlook
- Barrington Research analyst Gary Prestopino reiterated an Outperform rating and a $14 price target.
- Piper Sandler analyst Arvind Ramnani kept a Neutral rating but lowered his price target from $11 to $9.
Which Analyst has the best track record to show on CCCS?
Analyst Arvind Ramnani (PIPER SANDLER) currently has the highest performing score on CCCS with 5/8 (62.5%) price target fulfillment ratio. His price targets carry an average of $0.7 (6.80%) potential upside. CCC Intelligent Solutions Holdings stock price reaches these price targets on average within 109 days.
Datadog Faces Rising Costs Despite Q1 Revenue Growth and Updated Forecast
Datadog reported revenue of $762 million for the first quarter of 2025, marking a 25% increase from the same period last year and exceeding analyst expectations of $741.5 million. It recorded operating cash flow of $272 million and free cash flow of $244 million. Earnings came in at $0.46 per diluted share, ahead of the $0.43 consensus estimate.
Datadog ended the quarter with $4.4 billion in cash, cash equivalents, and marketable securities. Raised its full-year 2025 revenue forecast to a range of $3.215 billion to $3.235 billion, up from a previous range of $3.18 billion to $3.2 billion, while projecting second-quarter revenue between $787 million and $791 million.
Customer momentum continued to build, with approximately 3,770 customers generating over $100,000 in annual recurring revenue, a 13% increase from 3,340 a year earlier.
Analysts Trim Price Targets Despite Q1 Results and Raised Guidance
- Canaccord Genuity analyst Kingsley Crane maintained a Buy rating, though adjusted the price target downward from $150 to $145.
- Needham analyst Mike Cikos kept a Buy rating, yet reduced the price target from $160 to $130.
Which Analyst has the best track record to show on DDOG?
Analyst Brent Thill (JEFFERIES) currently has the highest performing score on DDOG with 16/23 (69.57%) price target fulfillment ratio. His price targets carry an average of $46.8 (53.06%) potential upside. Datadog stock price reaches these price targets on average within 94 days.
CuriosityStream Surpasses Q1 2025 Expectations with Revenue Growth and Dividend Increase
CuriosityStream reported first-quarter 2025 revenue of $15.1 million, a 26% year-over-year increase from $12.0 million in Q1 2024. This performance surpassed the consensus estimate of $14.95 million. Achieved positive earnings per share (EPS) of $0.01, exceeding analyst expectations by $0.03, as the forecast was for a loss of $0.02 per share. Gross profit rose to $8.0 million, with a margin of 53.1%, compared to $5.3 million and 43.8% in the prior-year period.
CuriosityStream recorded net income of $0.3 million, a $5.4 million improvement over the $5 million net loss a year earlier, and adjusted EBITDA reached $1.1 million, up from an adjusted EBITDA loss of $2.8 million. Adjusted free cash flow grew to $2 million, compared to $1.2 million in Q1 2024. Operating cash flow improved to $1.9 million, from $0.7 million last year, and total cash, restricted cash, and held-to-maturity securities stood at $39.1 million with no outstanding debt. Operating expenses, including advertising, marketing, and G&A, declined 11% year-over-year to $7.9 million.
CuriosityStream also announced it is doubling its quarterly dividend to $0.08 per share, equating to an annualized rate of $0.32, with the next dividend payable on June 20, 2025, to shareholders of record as of June 6. CuriosityStream expanded its global distribution with new service launches in North and Latin America, and secured rights to over 210,000 hours of additional content.
Looking ahead, CuriosityStream expects Q2 2025 revenue between $16.0 million and $17.0 million, surpassing the consensus estimate of $13.73 million, reflecting anticipated year-over-year growth of 30% to 37%. Also expects adjusted free cash flow in the range of $2.0 million to $3.0 million.
Analysts Upgraded Following Q1 2025 Performance
- Barrington Research analyst James Goss upgraded from Market Perform to Outperform and set a price target of $6.
- Needham analyst Laura Martin maintained a Buy rating and raised the price target from $2.95 to $4.8.
Which Analyst has the best track record to show on CURI?
Analyst Laura Martin (NEEDHAM) currently has the highest performing score on CURI with 13/17 (76.47%) price target fulfillment ratio. Her price targets carry an average of $0.35 (13.21%) potential upside. CuriosityStream stock price reaches these price targets on average within 278 days.
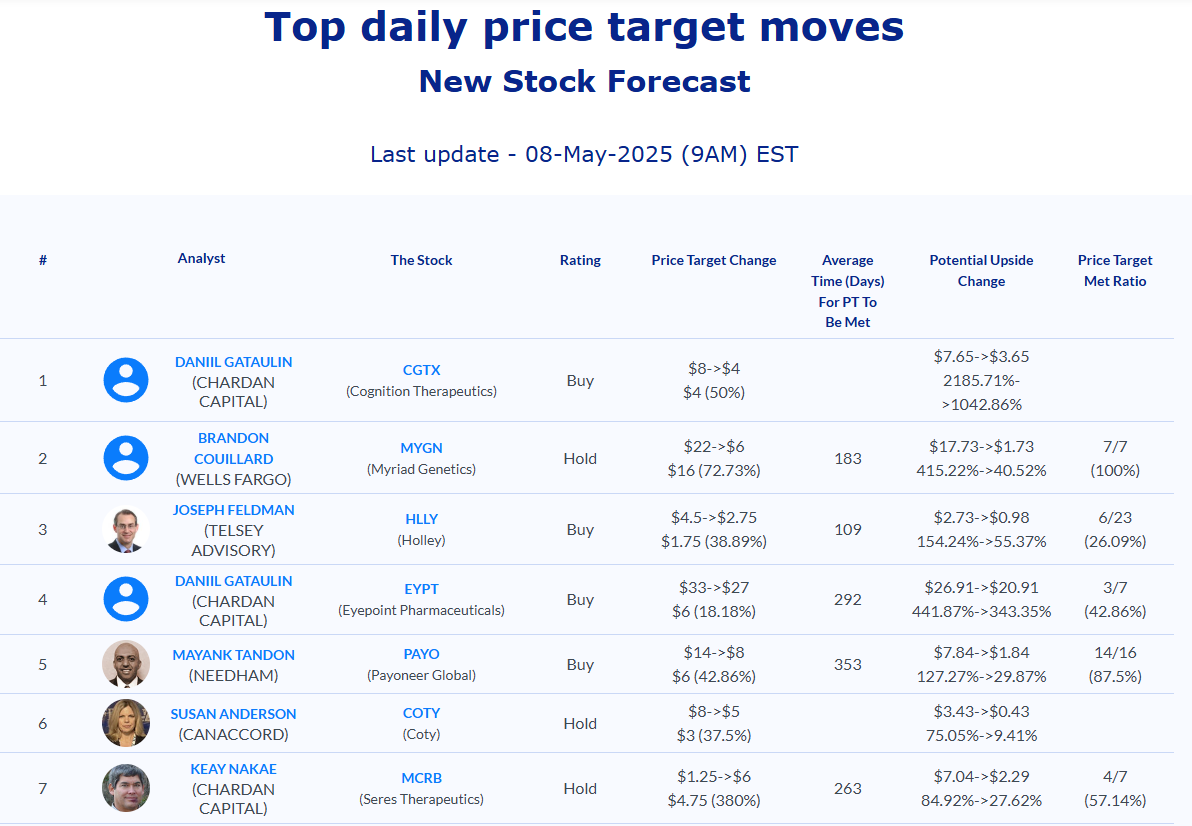
Daily stock Analysts Top Price Moves Snapshot

May 8, 2025: Analyst Price Target News: Carvana, Dutch Bros (May 8th, 2025)
This week in analyst price targets: Carvana reported Q1 2025 results driven by retail unit growth and expanded its long-term objectives. Dutch Bros reported Q1 results above expectations and reaffirmed its full-year guidance, drawing analyst price target increases.
By: Matthew Otto
Dutch Bros Reports Q1 Results Above Expectations, Reaffirms Full-Year Guidance
Dutch Bros reported its financial results for the first quarter ended March 31, 2025, with Q1 earnings per share (EPS) of $0.14, surpassing the analyst consensus of $0.11 by $0.03. Revenue totaled $355.2 million, beating estimates of $343.57 million and marking a 29.1% increase year-over-year from $275.1 million.
Company-operated shop revenues rose 31.6% to $326.4 million, while system same shop sales increased 4.7%, driven by a 1.3% increase in transactions. Company-operated same shop sales climbed 6.9%, with a 3.7% rise in transactions.
Dutch Bros opened 30 new shops during the quarter—25 of them company-operated—across 11 states. Net income rose to $22.5 million from $16.2 million in Q1 2024, while adjusted net income reached $24.8 million, up from $16.5 million. Adjusted EBITDA grew 19.7% to $62.9 million.
Gross profit from company-operated shops reached $71.5 million, with gross margin holding steady year-over-year at 21.9%, including 170 basis points of pre-opening costs. Contribution from company-operated shops rose 29.8% to $96.1 million, with a slight decline in contribution margin to 29.4%. Selling, general, and administrative expenses were $58.9 million (16.6% of revenue), while adjusted SG&A expenses came in at $53.5 million (15.1% of revenue).
For the full year, Dutch Bros reaffirmed its guidance, projecting revenue between $1.555 billion and $1.575 billion—slightly below the consensus estimate of $1.584 billion. Dutch Bros expects same shop sales growth of 2% to 4% and adjusted EBITDA of $265 to $275 million.
Analysts Adjust Price Targets Following Q1 Beat and Guidance
- Baird analyst David Tarantino maintained an Outperform rating and lifted the price target from $66 to $72.
- TD Securities analyst Andrew Charles reiterated a Buy rating and a $78 price target.
- Piper Sandler analyst Brian Mullan lowered the price target from $70 to $63.
Which Analyst has the best track record to show on BROS?
Analyst David Tarantino (BAIRD) currently has the highest performing score on BROS with 9/11 (81.82%) price target fulfillment ratio. His price targets carry an average of $12.92 (24.34%) potential upside. Dutch Bros stock price reaches these price targets on average within 20 days.
Carvana Reports Q1 2025 Results Driven by Retail Unit Growth and Expands Long-Term Objectives
Carvana reported its first quarter for fiscal 2025, reporting retail unit sales that rose 46% year-over-year to 133,898 vehicles. This contributed to $4.23 billion in total revenue, up 38% from $3.06 billion in Q1 2024.
Earnings per share came in at $1.51, well above the $0.67 consensus estimate. Reported also net income of $373 million (8.8% margin), adjusted EBITDA of $488 million (11.5% margin), and GAAP operating income of $394 million (9.3% margin). Approximately $158 million of net income was attributed to a favorable revaluation of warrants related to its partnership with Root Insurance.
Looking ahead, Carvana projects continued momentum in Q2 2025 with expected increases in both retail units sold and adjusted EBITDA. Also reaffirmed its full-year growth outlook and introduced a long-term strategic objective: to reach 3 million annual retail units sold with an adjusted EBITDA margin of 13.5% within the next 5 to 10 years.
Analyst Ratings Reflect Positive Outlook Following Q1 Results
- Baird analyst Colin Sebastian maintained a Neutral rating and raised the price target from $200 to $275.
- Needham analyst Chris Pierce reiterated a Buy rating and a price target of $340.
- Citi analyst Ronald Josey kept a Buy rating and raised the price target from $280 to $325.
- Wedbush analyst Scott Devitt lifted the price target to $290.
- BTIG analyst Marvin Fong maintained a Buy rating and raised the price target from $295 to $330.
Which Analyst has the best track record to show on CVNA?
Analyst Seth Basham (WEDBUSH) currently has the highest performing score on CVNA with 28/31 (90.32%) price target fulfillment ratio. His price targets carry an average of $-13.17 (-5.00%) potential downside. Carvana stock price reaches these price targets on average within 235 days.
Amplitude Reports First Quarter 2025 Results and Announces Share Repurchase Program
Amplitude reported a 10% year-over-year increase in first-quarter revenue, reaching $80 million for the period ending March 31, 2025. This performance exceeded analysts’ expectations, with revenue surpassing the consensus estimate of $79.81 million.
Annual Recurring Revenue (ARR) rose by 12%, totaling $320 million, up from $285 million in the first quarter of 2024. Remaining performance obligations grew 30%, reaching $325.9 million. Amplitude also reported an earnings per share (EPS) of $0, outperforming the analyst estimate of a $0.01 loss. The number of customers with ARR over $100,000 increased by 18%, totaling 617. Cash flow from operations and free cash flow were reported at $(8) million and $(9.2) million, respectively, showing a year-over-year decline.
Amplitude has provided guidance for Q2 2025, expecting EPS in the range of ($0.01) to $0.01, versus the consensus estimate of $0.01. For revenue, Amplitude projects a range of $80.3 million to $82.3 million, above the consensus of $80.26 million.
For the full year, Amplitude expects EPS between $0.05 and $0.1, exceeding the consensus of $0.07, with full-year revenue guidance ranging from $329 million to $333 million, surpassing the consensus estimate of $326.5 million. Additionally, Amplitude announced a $50 million share repurchase program, effective immediately.
Analysts Update Ratings and Price Targets After Q1 Performance and Outlook
- Baird analyst Rob Oliver maintained an Outperform rating but lowered the price target from $17 to $14.
- Needham analyst Scott Berg reiterated a Buy rating and a $16 price target.
- Piper Sandler analyst Brent Bracelin continued an Overweight rating and raised the price target from $14 to $15.
Which Analyst has the best track record to show on AMPL?
Analyst Taylor Mcginnis (UBS) currently has the highest performing score on AMPL with 8/11 (72.73%) price target fulfillment ratio. Her price targets carry an average of $1.15 (9.70%) potential upside. Amplitude stock price reaches these price targets on average within 64 days.
Daily stock Analysts Top Price Moves Snapshot
May 9, 2025: Analyst Price Target News: Cloudflare, Peloton (May 9th, 2025)
This week in analyst price targets: Cloudflare reported Q1 2025 revenue growth but guidance fell below street expectations, drawing cautious analyst revisions. Peloton shares slid on a wider-than-expected Q3 loss despite a slight revenue beat.
By: Matthew Otto
Cloudflare Reports Revenue Growth in Q1 2025; Guidance Below Street Expectations
Cloudflare reported first quarter revenue of $479.1 million, a 27% increase year-over-year and ahead of the consensus estimate of $469.65 million. Earnings per share for the quarter were $0.16, matching analyst expectations.
Operating income totaled $56 million, or 12% of revenue, while Cloudflare recorded a loss from operations of $53.2 million, or 11% of revenue. Net income was $58.4 million, with diluted earnings per share of $0.16. Gross profit reached $369.3 million, representing a margin of 77.1%, compared to $301.1 million and 79.5% in the prior year.
For the second quarter of fiscal 2025, Cloudflare expects revenue of $500 to $501 million. Below the $500.9 million consensus, and earnings per share of $0.18, versus the $0.19 expected by analysts. For the full fiscal year, Cloudflare projects revenue between $2.09 billion and $2.094 billion, in line with consensus, and earnings per share of $0.79 to $0.8, compared to the Street estimate of $0.82.
Analysts React to Q1 Beat with Mixed Rating and Target Adjustments
- Jefferies analyst Brent Thill maintained a Hold rating and reduced the price target from $170 to $150.
- Needham analyst Mike Cikos kept a Buy rating and raised the price target from $145 to $160.
- Mizuho analyst Gregg Moskowitz lifted the price target to $155.
- CapitalOne analyst Connor Murphy upgraded to Overweight.
- Scotiabank analyst Patrick Colville lowered the price target to $135.
Which Analyst has the best track record to show on NET?
Analyst Adam Borg (STIFEL) currently has the highest performing score on NET with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $8.34 (5%) potential upside. Cloudflare stock price reaches these price targets on average within 18 days.
Peloton Shares Slide on Wider-Than-Expected Q3 Loss Despite Slight Revenue Beat
Peloton Interactive reported mixed financial results for its fiscal third quarter ended March 31, posting a net loss of $0.12 per share. This is $0.05 worse than the analyst estimate of a $0.07 loss. Revenue for the quarter totaled $624 million, narrowly beating the consensus forecast of $623.03 million.
On a year-over-year basis, total revenue declined 13%, with Connected Fitness Products revenue falling 27% to $205.5 million and Subscription revenue down 4% to $418.5 million. Gross margin improved to 42.4%, up from 39.3% a year ago.
Peloton ended the quarter with 2.88 million paid Connected Fitness subscriptions, a 6% decrease year-over-year, though 10,000 above the high end of its guidance. Average Net Monthly Connected Fitness Churn remained stable at 1.3%.
For the fourth quarter and full fiscal year 2025, Peloton guided revenue in the range of $2.455 billion to $2.47 billion, which brackets the $2.46 billion consensus estimate. Additionally, Peloton raised its FY25 Adjusted EBITDA guidance to $330 to $350 million and expects to generate approximately $250 million in free cash flow.
Analysts Hold Steady Following Mixed Q3 Results and Weak Guidance
- Needham analyst Bernie McTernan reiterated a Hold rating.
- Telsey Advisory Group analyst Dana Telsey maintained a Market Perform rating but trimmed the price target from $9 to $8.
Which Analyst has the best track record to show on PTON?
Analyst Doug Anmuth (JPMORGAN) currently has the highest performing score on PTON with 14/28 (50%) price target fulfillment ratio. His price targets carry an average of $2 (40.00%) potential upside. Peloton Interactive stock price reaches these price targets on average within 123 days.
Hut 8 Highlights Infrastructure Expansion and Hashrate Growth in Q1 Update
In the first quarter of 2025, Hut 8 reported revenue of $21.8 million, a decrease from $51.7 million in the prior-year period, driven primarily by lower Bitcoin production volumes. Hut 8 recorded a net loss of $134.3 million and an Adjusted EBITDA of ($117.7) million, compared to net income of $250.7 million and Adjusted EBITDA of $297 million in Q1 2024.
The quarter reflected investment activity, including the execution of a major ASIC fleet upgrade that resulted in a 79% increase in deployed hashrate to 9.3 EH/s and a 37% improvement in fleet efficiency to 20 J/TH by quarter-end. Despite lower production—167 Bitcoin mined versus 716 in Q1 2024—Hut 8 reported a weighted average revenue per Bitcoin of $92,224, up from $51,769 in the same period last year. The cost to mine one Bitcoin rose to $58,757, reflecting increased energy costs and infrastructure transition.
Hut 8 ended the quarter with a reserve of 10,264 Bitcoin valued at approximately $847.2 million and total energy capacity under management of 1,020 MW. Also advanced its infrastructure platform with the launch of American Bitcoin, a majority-owned subsidiary focused on industrial-scale mining and strategic Bitcoin accumulation.
Key developments included ongoing construction at the 205 MW Vega site—over 70% of capital expenditures incurred—and groundbreaking at the 592-acre River Bend campus in Louisiana. Hut 8’s development pipeline stood at ~10,800 MW, including ~2,600 MW under exclusivity. Power revenue for the quarter totaled $4.4 million, digital infrastructure contributed $1.3 million, and compute-related operations, including mining and GPU services, generated $16.1 million.
Analysts Remain Bullish Amid Strategic Investments and Operational Progress
- Needham analyst John Todaro reiterated a Buy rating and a $21 price target.
- HC Wainwright & Co. analyst Mike Colonnese reaffirmed a Buy rating and a $25 price target.
- Rosenblatt analyst Chris Brendler maintained a Buy rating but trimmed his price target from $21 to $17.5.
Which Analyst has the best track record to show on HUT?
Analyst Mike Colonnese (HC WAINWRIGHT) currently has the highest performing score on HUT with 8/13 (61.54%) price target fulfillment ratio. His price targets carry an average of $15.98 (113.98%)potential upside. Hut 8 stock price reaches these price targets on average within 66 days.
Daily stock Analysts Top Price Moves Snapshot

May 12, 2025: Analyst Price Target News: Amphastar, Lantronix (May 12th, 2025)
By: Matthew Otto
Blend Reports Q1 2025 Operational Metrics Despite Revenue Miss and Lower EPS
Blend Labs reported its third consecutive quarter of year-over-year growth. Platform revenue for the first quarter reached $26.8 million, which is below the consensus estimate of $43.2 million. Blend Labs posted an earnings per share (EPS) loss of $0.01, underperforming analyst expectations by $0.02.
Software platform revenue grew 12% year-over-year to $24.3 million, led by a 45% increase in Consumer Banking Suite revenue to $9.6 million, partially offset by a 3% decline in Mortgage Suite revenue to $14.6 million.
Blend also recorded its first quarter of positive free cash flow at $15.5 million, with $20.1 million in cash provided by operating activities. Remaining performance obligations surged 70% year-over-year to $158.1 million.
Operating losses narrowed to $7.7 million from $21.2 million a year ago, while adjusted operating income turned positive at $1 million. For the second quarter, Blend expects platform revenue between $30.5 million and $32.5 million and full-year operating expenses of $85 million to $90 million.
Analyst Reaffirms Rating Following Q1 Metrics and Software Momentum
- Canaccord Genuity analyst Joseph Vafi maintained a Buy rating and a $5.25 price target.
Which Analyst has the best track record to show on BLND?
Analyst Michael Turrin (WELLS FARGO) currently has the highest performing score on BLND with 8/13 (61.54%) price target fulfillment ratio. His price targets carry an average of $1.89 (60.77%) potential upside. Blend Labs stock price reaches these price targets on average within 79 days.
Amphastar Tops Earnings Estimates Despite Revenue Miss and Decline in Profitability
Amphastar Pharmaceuticals reported net revenues of $170.5 million for the first quarter ended March 31, 2025. This is below the consensus estimate of $174.35 million and down 1% from $171.8 million in the same period last year.
Earnings per share came in at $0.74, exceeding analyst expectations by $0.05. Net income was $25.3 million, or $0.51 per share, compared to $43.2 million, or $0.81 per share, a year ago. Gross profit was $85.3 million with a margin of 50%, down from 52.4% last year, impacted by pricing pressure on epinephrine and higher labor costs. Operating cash flow totaled $35.1 million. Adjusted net income for the quarter was $36.9 million, compared to $55.3 million in Q1 2024.
BAQSIMI® led Amphastar’s product growth, generating $38.4 million in sales—a 177% year-over-year increase—following the assumption of global distribution. BAQSIMI® is designed to treat severe hypoglycemia—an acute and potentially life-threatening drop in blood glucose levels—in people with diabetes. According to the Centers for Disease Control and Prevention (CDC), over 37 million Americans have diabetes, and roughly 7 million of them use insulin, putting them at direct risk for severe hypoglycemic events.
Clinical studies and real-world data suggest that among insulin users, 20% to 40% may experience at least one severe hypoglycemic episode annually. That translates to approximately 1.4 to 2.8 million people in the U.S. each year who could potentially benefit from an emergency rescue treatment like BAQSIMI®.
Product revenues rose 8% year-over-year, though overall net revenues decreased due to the absence of $14.2 million in transitional revenue from BAQSIMI® recorded in Q1 2024. Selling, distribution, and marketing expenses increased 27%, while R&D expenses rose 18% to $20.1 million, driven by expanded clinical activities and FDA filing costs. Amphastar’s pipeline includes multiple biosimilar and proprietary candidates targeting market segments worth over $10 billion in aggregate.
Analyst Adjusts Price Target Amid Revenue Miss and Margin Pressure
- JP Morgan analyst Ekaterina Knyazkova downgraded from Overweight to Neutral and lowered the price target from $45 to $30.
Which Analyst has the best track record to show on AMPH?
Analyst David Amsellem (PIPER SANDLER) currently has the highest performing score on AMPH with 10/15 (66.67%) price target fulfillment ratio. His price targets carry an average of $3.71 (13.11%) potential upside. Amphastar Pharmaceuticals stock price reaches these price targets on average within 337 days.
Lantronix Reports Third Quarter FY2025 Results and Provides Fourth Quarter Outlook
Lantronix reported third-quarter fiscal 2025 earnings of $0.03 per share, which was $0.05 below the analyst estimate of $0.08. Revenue for the quarter was $28.5 million, falling short of the consensus estimate of $34.09 million. This represents a slight decrease from the $28.6 million reported in Q3 FY2024.
For the fourth quarter of fiscal 2025, Lantronix expects earnings to be between $0.00 and $0.02 per share, compared to the consensus estimate of $0.03. Lantronix forecasts Q4 revenue in the range of $26.5 million to $30.5 million, missing the consensus estimate of $30.12 million.
Analysts Maintain Ratings, Adjust Price Targets After Q3 Results
- Canaccord Genuity analyst George Gianarikas maintained a Buy rating but lowered the price target from $4.5 to $3.
- Needham analyst Ryan Koontz kept a Buy rating but reduced the price target from $5.5 to $4.5.
Which Analyst has the best track record to show on LTRX?
Analyst Jaeson Schmidt (LAKE STREET) currently has the highest performing score on LTRX with 2/7 (28.57%) price target fulfillment ratio. His price targets carry an average of $1.9 (90.48%) potential upside. Lantronix stock price reaches these price targets on average within 612 days.
Daily stock Analysts Top Price Moves Snapshot

May 13, 2025: Analyst Price Target News: Rapid7, Xenon, Agenus (May 13th, 2025)
By: Matthew Otto
Xenon Reports Q1 2025 Results and Advances Late-Stage and Early-Stage Pipeline
Xenon Pharmaceuticals reported a Q1 2025 net loss of $65.0 million, or ($0.83) per share, which was $0.08 better than the analyst consensus estimate of ($0.91). Revenue for the quarter was $7.5 million, exceeding the consensus estimate of $1.25 million.
Research and development expenses increased to $61.2 million from $44.3 million in Q1 2024. General and administrative expenses rose to $19.0 million, up from $14.8 million year-over-year. Cash, cash equivalents, and marketable securities totaled $691.1 million as of March 31, 2025.
Looking ahead, Xenon anticipates completing enrollment in the Phase 3 X-TOLE2 study for focal onset seizures (FOS) in the coming months, with topline data expected in early 2026. FOS affects approximately 2.2 million people in the U.S. and is the most common form of epilepsy in adults. If successful, azetukalner could provide a new treatment option for patients who are refractory to current therapies—up to 30% of epilepsy patients remain uncontrolled despite available medications.
Xenon is also expanding azetukalner’s use into neuropsychiatric conditions, with its second Phase 3 study in major depressive disorder (MDD), X-NOVA3, and a new trial in bipolar depression (BPD) set to begin mid-year. MDD affects over 21 million U.S. adults annually, while BPD impacts approximately 7 million.
Analysts Adjust Price Targets Following Q1 Beat and Pipeline Progress
- Needham analyst Serge Belanger reiterated a Buy rating while lowering the price target from $60 to $55.
- Chardan Capital analyst Rudy Li reaffirmed a Buy rating and a $55 price target.
- Wells Fargo analyst Mohit Bansal reduced the price target to $47.
- HC Wainwright & Co. analyst Douglas Tsao reiterated a Buy rating and a $53 price target.
Which Analyst has the best track record to show on XENE?
Analyst Laura Chico (WEDBUSH) currently has the highest performing score on XENE with 8/12 (66.67%) price target fulfillment ratio. Her price targets carry an average of $4.03 (9.60%) potential upside. Xenon Pharmaceuticals stock price reaches these price targets on average within 413 days.
Agenus Reports Progress in Cancer Drug Development and First Quarter 2025 Results
Agenus shared its first quarter 2025 results and important updates on its experimental cancer treatment—a drug combination called botensilimab (BOT) and balstilimab (BAL). New data from ongoing studies show this treatment is working in cancers that usually don’t respond to other immunotherapy drugs. These include colorectal cancer (CRC), triple-negative breast cancer (TNBC), liver cancer, and certain types of sarcomas.
Globally, more than 1.4 million people are diagnosed annually with CRC, including approximately 85% with MSS tumors—representing a patient population of over 1 million individuals who may benefit from new treatment options like BOT/BAL. Similarly, over 300,000 cases of TNBC and 400,000 cases of liver cancer are diagnosed annually, many of whom have limited options after first-line treatments.
Financially, Agenus reported a Q1 2025 net loss of $26.4 million, or ($1.03) per share, in line with its reported earnings per share. Revenue for the quarter came in at $24.07 million, below $28.0 million in the same period last year. Agenus reduced operational cash usage to $25.6 million, compared to $38.2 million in Q1 2024, and ended the quarter with $18.5 million in cash and cash equivalents, down from $40.4 million as of December 31, 2024.
Analysts Maintain Ratings as Clinical Progress and Cost Discipline Continue
- HC Wainwright & Co. analyst Emily Bodnar reiterated her Neutral rating.
- Baird analyst Colleen Kusy maintained a Neutral stance and raised her price target from $3 to $4.
Which Analyst has the best track record to show on AGEN?
Analyst Emily Bodnar (HC WAINWRIGHT) currently has the highest performing score on AGEN with 3/9 (33.33%) price target fulfillment ratio. Her price targets carry an average of $3.58 (104.68%) potential upside. Agenus stock price reaches these price targets on average within 285 days.
Rapid7 Reports Q1 2025 Financial Results and Strategic Updates
Rapid7 reported its first quarter in 2025, with annualized recurring revenue (ARR) of $837 million, reflecting a 4% increase year-over-year. Total revenue for Q1 reached $210.25 million, exceeding analysts' expectations of $208.24 million. Product subscriptions revenue grew by 4% to $204 million, while professional services revenue declined by 23% to $6.3 million.
Rapid7’s operating income for the quarter stood at $32 million, with net income of $2.1 million, or $0.03 per share. Delivered earnings per share (EPS) of $0.43, which was $0.09 better than the consensus estimate of $0.34. Additionally, Rapid7 generated $30 million in net cash from operating activities and reported free cash flow of $25 million, demonstrating strong financial discipline.
Looking ahead, Rapid7 provided its guidance for the second quarter and full-year 2025. For Q2, Rapid7 anticipates revenue between $211 million and $213 million, below the consensus estimate of $217.7 million, and EPS between $0.43 and $0.46, in line with analyst expectations of $0.46.
For the full year, Rapid7 expects revenue in the range of $853 million to $863 million, which is below the consensus of $861.2 million. Full-year EPS guidance is projected between $1.78 and $1.91, compared to the consensus estimate of $1.84.
Analysts Adjust Price Targets Amidst Q1 Results and Market Uncertainty
- Baird analyst Shrenik Kothari maintained a Neutral rating and raised the price target from $26 to $28.
- DA Davidson analyst Rudy Kessinger downgraded from Neutral to Underperform and the price target from $29 to $21.
- Scotiabank analyst Patrick Colville lowered the price target to $29.
- Piper Sandler analyst Rob Owens adjusted the price target downward to $30.
- Truist Securities analyst Joel Fishbein reduced the price target to $28.
Which Analyst has the best track record to show on RPD?
Analyst Brian Essex (JPMORGAN) currently has the highest performing score on RPD with 11/13 (84.62%) price target fulfillment ratio. His price targets carry an average of $1.18 (3.39%) potential upside. Rapid7 stock price reaches these price targets on average within 39 days.
Daily stock Analysts Top Price Moves Snapshot
May 14, 2025: Analyst Price Target News: On Holding, Airbnb (May 14th, 2025)
This week in analyst price targets: On Holding reported Q1 sales and raised its full-year 2025 outlook amid continued global demand, drawing analyst price target increases. Airbnb launched a redesigned app with expanded services and experiences.
By: Matthew Otto
On Holding Reports Q1 Sales, Raises Full-Year 2025 Outlook Amid Continued Global Demand
On Holding reported first-quarter 2025 earnings per share (EPS) of $0.19, exceeding the analyst consensus estimate of $0.17. Revenue for the quarter reached $812.5 million, ahead of the $761.5 million consensus forecast. Net sales rose 43% year-over-year, or 40% on a constant currency basis, supported by a 45.3% increase in direct-to-consumer (DTC) sales and a 41.5% increase in wholesale sales.
The Asia-Pacific region led geographic growth with a 130.1% increase in net sales to $134.8 million, while the Americas and EMEA grew by 32.7% and 33.6%, respectively. Product-wise, footwear sales climbed 40.5% to $756.1 million, apparel rose 93.1% to $42.3 million, and accessories nearly doubled to $8.4 million. Gross profit rose 43.5% to $483.6 million, with a gross profit margin of 59.9%, up from 59.7% the prior year.
Net income declined 38% year-over-year to $63 million, bringing the net income margin to 7.8%, down from 18%. Adjusted EBITDA increased 54.8% to $133.2 million, with an adjusted EBITDA margin of 16.5%, up from 15.2%. Adjusted net income totaled $78.2 million, and adjusted diluted EPS came in at $0.23, down from $0.36 a year earlier. Cash and cash equivalents decreased 5.7% to $968.6 million, while net working capital increased 20.3% to $666.6 million.
Despite raising guidance for constant currency growth to 28%, On lowered its full-year 2025 revenue outlook to $3.19 billion, down from a previous estimate of $3.28 billion and below the $3.32 billion analyst consensus. On reaffirmed its expected full-year gross profit margin range of 60% to 60.5% and adjusted EBITDA margin range of 16.5% to 17.5%.
Analysts Raise Price Targets Following Q1 Beat and Updated Guidance
- Telsey Advisory Group analyst Cristina Fernandez maintained an Outperform rating and a price target of $65.
- Needham analyst Tom Nikic kept a Buy rating and lifted the price target from $55 to $62.
- KeyBanc analyst Ashley Owens raised the price target to $68.
- Baird analyst Jonathan Komp boosted the price target to $70.
- Truist Securities analyst Joseph Civello maintained a Buy rating and increased the price target from $61 to $69.
Which Analyst has the best track record to show on ONON?
Analyst Jim Duffy (STIFEL) currently has the highest performing score on ONON with 10/12 (83.33%) price target fulfillment ratio. His price targets carry an average of $13.98 (32.50%) potential upside. On Holding stock price reaches these price targets on average within 186 days.
Silicon Labs Posts Q1 Results, Beats Estimates and Projects Growth in Q2
Silicon Labs reported Q1 2025 revenue of $178 million, compared to $147 million in Q1 2024. Revenue for the Industrial & Commercial segment was $96 million, up 47% year-over-year. Revenue for the Home & Life segment was $82 million, up 99% year-over-year. Gross margin was 55.4%.
Operating expenses were $105 million. Operating loss was $7 million. Diluted earnings per share were ($0.08), compared to the analyst estimate of ($0.09). The revenue consensus estimate was $175.7 million.
For Q2 2025, Silicon Labs expects revenue between $185 million and $200 million, versus the consensus estimate of $187.9 million. Expected diluted earnings per share are in the range of ($0.01) to $0.19, compared to the consensus estimate of $0.03.
Analysts Reaffirm Positive Outlook Following Q1 Beat and Upbeat Guidance
- Benchmark analyst Cody Acree reiterated a Buy rating and the $160 price target.
- Needham analyst Quinn Bolton maintained a Buy rating and a $150 price target.
- Citi analyst Atif Malik raised the price target from $138 to $140.
- JPMorgan analyst Peter Peng reaffirmed an Overweight rating and a $160 price target.
Which Analyst has the best track record to show on SLAB?
Analyst Blayne Curtis (BARCLAYS) currently has the highest performing score on SLAB with 12/14 (85.71%) price target fulfillment ratio. His price targets carry an average of $-14.32 (-15.18%) potential downside. Silicon Labs stock price reaches these price targets on average within 46 days.
Airbnb Launches Redesigned App with Expanded Services and Experiences
Airbnb released a redesigned app that allows users to book additional services during their home stays, such as catering, spa treatments, and personal training. These services will initially be available in 260 cities.
Airbnb stated that service providers average 10 years of experience and that a dedicated vetting team, which includes legal professionals, will review certifications and licenses. The app update is part of Airbnb’s plan to invest between $200 million and $250 million into a new business segment aimed at expanding beyond home rentals.
The update also expands Airbnb’s experiences offering, which was first launched in 2016. The new experiences tab categorizes activities into 19 types and is available in 650 cities. Experiences include architectural tours, live performances, and workouts.
Airbnb is also preparing for a partnership related to the 2026 Winter Olympics in Milan. Additional app updates include social features allowing users to see other attendees at experiences and a messaging system that supports photo and video sharing.
Analyst Retains Rating Amid Efforts to Broaden Revenue Streams
- Needham analyst Bernie McTernan reiterates Airbnb from Hold to Hold.
Which Analyst has the best track record to show on ABNB?
Analyst Doug Anmuth (JPMORGAN) currently has the highest performing score on ABNB with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $9.31 (8.81%) potential upside. Airbnb stock price reaches these price targets on average within 37 days.
Daily stock Analysts Top Price Moves Snapshot

May 15, 2025: Analyst Price Target News: Cisco, Jack in the Box (May 15th, 2025)
This week in analyst price targets: Cisco beat Q3 estimates and lifted its outlook on strong AI infrastructure momentum, driving broad analyst price target increases. Jack in the Box reported Q2 2025 results amid sales declines and impairment charges.
By: Matthew Otto
Cisco Beats Q3 Estimates, Lifts Outlook on Strong AI Infrastructure Momentum
Cisco Systems delivered results for its fiscal third quarter, with adjusted earnings per share of $0.96, $0.04 above the consensus estimate of $0.92. Revenue reached $14.15 billion, ahead of both the $14.04 billion analyst forecast and the $12.7 billion posted a year earlier—an 11% year-over-year increase.
Net income rose to $2.49 billion, or $0.62 per share, compared with $1.89 billion, or $0.46 per share, in the prior-year period. Networking revenue grew 8% to $7.07 billion, surpassing StreetAccount’s estimate of $6.81 billion. Security revenue surged 54% to $2.01 billion, driven in part by the integration of Splunk, although it came in below the $2.17 billion consensus.
For Q4 2025, Cisco expects EPS between $0.96 and $0.98, compared to the consensus estimate of $0.95. Revenue is forecast at $14.5 billion to $14.7 billion, slightly above the expected $14.52 billion.
For the full fiscal year 2025, Cisco projects EPS of $3.77 to $3.79, ahead of the $3.72 consensus, and revenue between $56.5 billion and $56.7 billion versus the $56.4 billion estimate. CEO Chuck Robbins said Cisco is ahead of schedule on its AI infrastructure goals, reporting over $600 million in orders this quarter and bringing the fiscal year total to over $1.25 billion—surpassing the $1 billion mark one quarter early.
Analyst Price Target Hikes Following Strong Q3 and Guidance
- Barclays analyst Tim Long maintained an Equal-Weight rating but lifted the price target from $61 to $66.
- JP Morgan analyst Samik Chatterjee reiterated an Overweight rating and increased the price target from $70 to $73.
- Wells Fargo analyst Aaron Rakers upgraded from Equal-Weight to Overweight and the price target from $72 to $75.
- Citi analyst Atif Malik kept a Buy rating and boosted the price target to $71 from $68.
- Evercore ISI analyst Amit Daryanani raised the price target from $67 to $72.
Which Analyst has the best track record to show on CSCO?
Analyst Tim Long (BARCLAYS) currently has the highest performing score on CSCO with 21/22 (95.45%) price target fulfillment ratio. His price targets carry an average of $-2.84 (-4.45%) potential downside. Cisco Systems stock price reaches these price targets on average within 535 days.
Jack in the Box Reports Q2 2025 Results Amid Sales Declines and Impairment Charges
Jack in the Box reported financial results for the second quarter ended April 13, 2025, highlighting declines in same-store and systemwide sales across both the Jack in the Box and Del Taco brands. Same-store sales decreased 4.4%, with franchise locations down 4.5% and company-owned units down 4%. Systemwide sales declined 4.9%. Del Taco same-store sales declined 3.6%, with a 4.2% decline in franchise locations and a 1.7% drop in company-operated stores; systemwide sales fell 4.5%.
Restaurant-level margin at Jack in the Box was $18.7 million, or 19.6%, down from $23.3 million, or 23.6%, in the prior year. Del Taco restaurant-level margin was $6.1 million, or 12.8%, compared to $11.4 million, or 16.8%, last year. Net restaurant count decreased by seven for Jack in the Box and increased by two for Del Taco.
For the quarter, Jack in the Box reported operating EPS of $1.2, exceeding the analyst consensus estimate of $1.07 by $0.13. Total revenue was $336.7 million, which came in below the consensus estimate of $345.76 million and declined 7.8% from $365.3 million in the prior year, largely due to Del Taco refranchising activity.
Jack in the Box posted a GAAP diluted loss per share of ($7.47), reflecting a $203.2 million non-cash goodwill and intangible impairment charge related to Del Taco. Net loss was $142.2 million, versus net income of $25 million a year earlier. Adjusted EBITDA came in at $66.5 million, down from $75.7 million. SG&A expense increased to $35.5 million due to changes in the value of corporate-owned life insurance policies.
Analysts Adjust Price Targets Following Q2 Miss and Impairment Charge
- Loop Capital analyst Alton Stump maintained a Buy rating but trimmed the price target from $65 to $61.
- Barclays analyst Jeffrey Bernstein continued with Equal-Weight rating and reduced the price target from $24 to $23.
- TD Securities analyst Andrew Charles reiterated a Hold rating and a $31 price target.
Which Analyst has the best track record to show on JACK?
Analyst Andrew Charles (TD SECURITIES) currently has the highest performing score on JACK with 19/37 (51.35%) price target fulfillment ratio. His price targets carry an average of $5.25 (20.39%) potential upside. Jack in the Box stock price reaches these price targets on average within 185 days.
Global-e Posts Q1 Growth but Narrow Losses Persist Amid Market Uncertainty
Global-e Online announced its financial results for the first quarter of 2025, reporting a revenue of $189.9 million, surpassing the consensus estimate of $187.75 million. This is driven by $84.0 million in service fees and $105.9 million in fulfillment services.
Gross Merchandise Value increased 34% year over year to $1.24 billion, while gross profit rose 31% to $86.3 million. Operating profit before certain costs reached $31.6 million, compared to $21.3 million in the prior year, and the net loss narrowed to $17.9 million from $32.1 million a year earlier. Earnings per share for the quarter was ($0.11), beating analyst expectations by $0.02. Gross margin remained steady at 45.4%.
Looking ahead, Global-e expects Q2 revenue between $204 million and $211 million, slightly below the consensus estimate of $212.3 million. For the full year, revenue is projected between $917 million and $967 million, which is above the consensus forecast of $938.8 million.
Analysts Price Targets Decline Despite Mixed Q1 2025 Results
- Wells Fargo analyst Andrew Bauch continued as Overweight but lowered the price target from $45 to $40.
- Benchmark analyst Mark Zgutowicz maintained a Buy rating but adjusted the price target down from $55 to $52.
- Needham analyst Scott Berg reiterated a Buy rating and the price target at $40.
Which Analyst has the best track record to show on GLBE?
Analyst James Faucette (MORGAN STANLEY) currently has the highest performing score on GLBE with 13/14 (92.86%) price target fulfillment ratio. His price targets carry an average of $8.76 (23.52%) potential upside. Global-e Online stock price reaches these price targets on average within 156 days.
Daily stock Analysts Top Price Moves Snapshot
May 16, 2025: Analyst Price Target News: Applied Materials, Doximity (May 16th, 2025)
This week in analyst price targets: Applied Materials posted mixed Q2 results amid export challenges and segment weakness. Doximity exceeded Q4 but issued below-consensus guidance for fiscal 2026, triggering analyst price target cuts.
By: Matthew Otto
Applied Materials Posts Mixed Q2 Results Amid Export Challenges and Segment Weakness
Applied Materials reported second-quarter fiscal 2025 revenue of $7.10 billion, up 7% year over year but slightly below the consensus estimate of $7.12 billion. Earnings per share came in at $2.39, surpassing analyst expectations by $0.08.
Gross margin was 49.2%, and operating margin reached 30.7%, both up 1.7 percentage points from the prior year. Net income rose 24% to $2.14 billion. Applied Materials generated $1.57 billion in cash from operations and returned $2.00 billion to shareholders through $1.67 billion in share repurchases and $325 million in dividends.
The Semiconductor Systems segment delivered $5.26 billion in revenue, up from $4.90 billion a year earlier but below estimates of $5.32 billion. Revenue from China accounted for 25% of total sales, down from 43% last year, as U.S. export controls continued to weigh on results. The Display segment saw revenue rise to $259 million with a sharp increase in margin to 26.3% from 2.8%.
For the third quarter, Applied Materials expects earnings per share between $2.15 and $2.55, compared to the consensus of $2.31, and revenue in the range of $6.7 billion to $7.7 billion, versus the consensus of $7.2 billion.
Analysts Adjust Price Targets Following Q2 Beat and Cautious Outlook
- Needham analyst Charles Shi reiterated a Buy rating and the price target at $195.
- Citi analyst Atif Malik kept a Buy rating and raised his price target from $170 to $190.
- Evercore ISI analyst Mark Lipacis lowered the price target to $209.
- JPMorgan analyst Harlan Sur maintained a Buy rating but cut the price target from $240 to $210.
- Morgan Stanley analyst Joseph Moore revised the price target down from $164 to $162.
Which Analyst has the best track record to show on AMAT?
Analyst Toshiya Hari (GOLDMAN SACHS) currently has the highest performing score on AMAT with 22/25 (88%) price target fulfillment ratio. His price targets carry an average of $30.74 (17.95%) potential upside. Applied Materials stock price reaches these price targets on average within 112 days.
Doximity Exceeds Q4 but Issues Below-Consensus Guidance for 2026
Doximity reported financial results with fourth quarter revenue up 17% year-over-year to $138.3 million, beating the consensus estimate of $134.03 million. Earnings per share of $0.38, surpassing analyst expectations of $0.27 by $0.11.
Subscription revenue for the quarter was $131.9 million, while net income grew to $62.5 million, up from $40.6 million a year ago. Adjusted EBITDA increased 24% year-over-year to $69.7 million, representing a margin of 50.4%. Operating cash flow reached $98.5 million, a 54% increase, and free cash flow came in at $97.0 million, up 56% from the prior year.
For fiscal year 2025, Doximity generated revenue of $570.4 million, up 20% from the previous year, with subscription revenue of $543.8 million. Net income rose to $223.2 million, representing a margin of 39.1%. Doximity reported adjusted EBITDA of $313.8 million, up 36% year-over-year, and free cash flow of $266.7 million, a 50% increase.
Looking forward, Doximity expects Q1 fiscal 2026 revenue between $139 million and $140 million, compared to the consensus estimate of $143.4 million. Full-year FY2026 revenue is projected to be in the range of $619 million to $631 million, below the consensus forecast of $639.4 million. Adjusted EBITDA guidance stands at $71 to $72 million for Q1 and $333 to $345 million for the full year.
Analysts Lower Price Targets Following Soft FY2026 Guidance
- Canaccord Genuity analyst Richard Close reiterated a Hold rating but reduced the price target from $71 to $50.
- Needham analyst Scott Berg maintained a Buy rating but lowered the price target from $82 to $67.
- Raymond James analyst Brian Peterson cut the price target from $83 to $65.
Which Analyst has the best track record to show on DOCS?
Analyst Brian Peterson (RAYMOND JAMES) currently has the highest performing score on DOCS with 6/6 (100%) price target fulfillment ratio. His price targets carry an average of $3.77 (4.76%) potential upside. Doximity stock price reaches these price targets on average within 50 days.
Foot Locker Reports Q1 Preliminary Results and Agrees to $2.4 Billion Acquisition
Foot Locker released preliminary results for the first quarter ended May 3, 2025, reporting a net loss of $363 million, compared to a profit of $8 million in the same quarter last year. Noted a 2.6% drop in comparable sales, with North American same-store sales down 0.5%.
Earnings per share fell to a loss of $3.81, compared to earnings of $0.09 in the prior-year period. When excluding impairment and tax-related charges, Foot Locker estimates a smaller loss of $6 million, or $0.07 per share, versus adjusted earnings of $21 million, or $0.22 per share, in the year-ago quarter.
In a separate announcement, Foot Locker confirmed it has agreed to be acquired by DICK’S Sporting Goods in a deal valuing at approximately $2.4 billion. Shareholders will have the option to receive either $24.00 in cash or 0.1168 shares of DICK’S stock for each Foot Locker share. The transaction, unanimously approved by both boards, is expected to close in the second half of 2025.
Mixed Analyst Ratings Amid Acquisition and Earnings News
- Barclays analyst Adrienne Yih downgraded from Overweight to Equal-Weight but raised the price target from $14 to $24.
- Telsey Advisory Group analyst Cristina Fernandez maintained a Market Perform rating and increased the price target from $20 to $24.
- Citi analyst Paul Lejuez raised the price target from $20 to $24.
Which Analyst has the best track record to show on FL?
Analyst Jay Sole (UBS) currently has the highest performing score on FL with 9/13 (69.23%) price target fulfillment ratio. His price targets carry an average of $3.63 (20.90%) potential upside. Foot Locker stock price reaches these price targets on average within 147 days.
Daily stock Analysts Top Price Moves Snapshot
May 19, 2025: Analyst Price Target News: Okta, Endava (May 19th, 2025)
This week in analyst price targets: Okta topped Q1 estimates but signaled slower growth ahead in its FY26 outlook, drawing mixed analyst revisions as investors weighed near-term caution against improving security platform fundamentals.
By: Matthew Otto
Celcuity Reports First Quarter 2025 Results and Updates on Clinical Pipeline Progress
Celcuity reported a net loss of $37 million for the first quarter ended March 31, 2025, or ($0.86) per share. This result was $0.14 below the analyst estimate of ($0.72) and compared to a loss of $21.6 million, or ($0.64) per share, in the first quarter of 2024. Operating expenses increased 60% year-over-year to $36.1 million. This includes $32.2 million in research and development costs and $3.9 million in general and administrative expenses. Cash used in operations was $35.9 million, up from $17.1 million in the same period last year.
As of March 31, 2025, Celcuity held $205.7 million in cash, cash equivalents, and short-term investments, which it expects will support clinical operations through 2026. R&D spending increased by $11.6 million, of which $5.9 million was attributed to employee and consulting expenses and $5.7 million to clinical trial-related activities.
The VIKTORIA-1 Phase 3 trial is evaluating gedatolisib in patients with HR+/HER2- advanced breast cancer. A condition diagnosed in approximately 300,000 women annually in the U.S. and EU combined. The VIKTORIA-2 Phase 3 trial is scheduled to begin dosing patients in the second quarter of 2025 and will include a safety run-in of 12 to 36 participants. Additionally, the CELC-G-201 study in metastatic castration-resistant prostate cancer, affecting over 80,000 men in the U.S., is expected to report Phase 1b safety data in late Q2 2025. A separate collaboration with Dana-Farber Cancer Institute and Massachusetts General Hospital will investigate gedatolisib in combination therapies for endometrial cancer, which sees approximately 60,000 new diagnoses annually in the U.S.
Analyst Maintains Rating and Target Following Results and Updates
- HC Wainwright & Co. analyst Swayampakula Ramakanth reiterated a Buy rating and a $27 price target.
Which Analyst has the best track record to show on CELC?
Analyst Alexander Nowak (CRAIG HALLUM) currently has the highest performing score on CELC with 3/5 (60%) price target fulfillment ratio. His price targets carry an average of $9.34 (52.89%) potential upside. Celcuity stock price reaches these price targets on average within 271 days.
Bit Digital Reports First Quarter 2025 Results with Shift Toward Cloud and Colocation Services
Bit Digital reported first quarter 2025 revenue of $25.1 million, a 17% decrease compared to $30.2 million in the same period last year and below the consensus estimate of $28.69 million. Reported a net loss of $0.32 per diluted share, compared to earnings of $0.43 per share in the prior-year quarter and below the analyst estimate of a $0.03 loss.
Bitcoin mining revenue declined 64% to $7.8 million from $21.9 million in Q1 2024. Cloud services revenue increased 84% to $14.8 million, up from $8.1 million. Colocation services, not present in the prior-year quarter, contributed $1.6 million. ETH staking revenue increased 72% year-over-year to $0.6 million.
As of March 31, 2025, digital asset mining accounted for 31% of total revenue, compared to 72% a year ago and 40% in the previous quarter. Bit Digital ended the quarter with $61.3 million in cash, cash equivalents, and restricted cash, and total liquidity of approximately $141.4 million, which includes USDC and digital assets.
Operationally, Bit Digital earned 83.3 bitcoins, down 80% from 417.1 bitcoins in Q1 2024. Earned 211 ETH during the quarter and reported holdings of 417.6 BTC and 24,434.2 ETH, valued at approximately $34.5 million and $44.5 million, respectively, as of March 31. The active bitcoin hash rate was 1.5 EH/s, down from 2.2 EH/s in Q1 2024, while the total deployed fleet reached 20,854 miners with a maximum potential hash rate of 2.4 EH/s. ETH actively staked a total of approximately 21,568.
Adjusted EBITDA was negative $44.5 million, compared to positive $58.5 million in the prior-year quarter. Reflecting a $49.2 million mark-to-market loss on digital assets versus a $45.7 million gain in Q1 2024. During the quarter, Bit Digital signed contracts totaling over 200 NVIDIA H200 GPUs, a five-year colocation agreement with Cerebras Systems for 5MW of capacity, and two new GPU service orders with Boosteroid totaling 701 servers. Subsequent to quarter-end, Bit Digital signed agreements for 616 additional H200 GPUs and entered into a definitive agreement to acquire a data center property in North Carolina.
Analyst Reiterates Rating and Target Despite Q1 Miss
- HC Wainwright & Co. analyst Kevin Dede reiterated a Buy rating and a $7 price target.
Which Analyst has the best track record to show on BTBT?
Analyst Kevin Dede (HC WAINWRIGHT) currently has the highest performing score on BTBT with 7/14 (50%) price target fulfillment ratio. His price targets carry an average of $5.24 (297.73%) potential upside. Bit Digital stock price reaches these price targets on average within 127 days.
Endava Reports Q3 FY2025 Profit Growth Despite Revenue Miss and Lowers Outlook
Endava reported third quarter fiscal 2025 revenue of $260 million, an 11.7% increase year over year, though it came in below the consensus estimate of $266 million. Earnings per share for the quarter were $0.45, exceeding analyst expectations by $0.04. Profit before tax reached $18.1 million, compared to a loss of $0.7 million in the same period last year, while net profit totaled $14.5 million, reversing a net loss of $2.2 million a year earlier. Operating cash flow was $25 million, up from $4 million in Q3 FY2024.
For Q4 FY2025, Endava expects EPS between $0.29 and $0.32, well below the consensus of $0.6, and revenue in the range of $248 to $250 million, compared to analysts’ expectations of $359 million. For the full fiscal year, Endava now forecasts EPS between $1.47 and $1.50 and revenue between $1.028 and $1.031 billion. Both under the consensus estimates of $2.10 for EPS and $1.434 billion for revenue.
Analyst Downgrades Following Q3 Revenue Miss and Reduced Guidance
- JP Morgan analyst Puneet Jain downgraded from Overweight to Neutral and announced an $18 price target.
Which Analyst has the best track record to show on DAVA?
Analyst Mayank Tandon (NEEDHAM) currently has the highest performing score on DAVA with 10/21 (47.62%) price target fulfillment ratio. His price targets carry an average of $3.22 (21.79%) potential upside. Endava stock price reaches these price targets on average within 93 days.
Daily stock Analysts Top Price Moves Snapshot
May 20, 2025: Analyst Price Target News: JPMorgan, ZIM Integrated (May 20th, 2025)
This week in analyst price targets: JPMorgan projected a decline in investment banking fees with a cautious 2025 outlook. ZIM Integrated beat Q1 expectations with higher revenue, earnings, and strong volume growth.
By: Matthew Otto
ZIM Beats Q1 Expectations with Higher Revenue, Earnings, and Strong Volume Growth
ZIM Integrated Shipping Services reported first quarter 2025 revenue of $2.01 billion, exceeding the consensus estimate of $1.82 billion. Marking a 28% increase from $1.56 billion in the prior-year period. Net income rose to $296 million, or $2.45 per diluted share, which was $0.71 above the analyst estimate of $1.74. Earnings before interest and taxes (EBIT) totaled $464 million, compared to $167 million a year earlier.
ZIM carried 944 thousand twenty-foot equivalent units (TEUs), a 12% increase from the first quarter of 2024. The average freight rate per TEU rose 22% year-over-year to $1,776. EBIT and net income margins improved to 23% and 15%, respectively. Cash generated from operating activities reached $855 million, up from $326 million, and free cash flow increased to $787 million from $303 million in the prior-year period.
ZIM ended the quarter with $3.37 billion in total cash, up from $3.14 billion at year-end 2024. Net debt declined to $2.49 billion from $2.88 billion, reducing the net leverage ratio to 0.6x from 0.8x. ZIM’s board declared a dividend of $0.74 per share, totaling $89 million, representing approximately 30% of first-quarter net income. Capital expenditures for the quarter rose to $78 million from $24 million a year earlier.
For the full year 2025, ZIM reaffirmed its outlook, expecting to generate between $1.6 billion and $2.2 billion in earnings before interest, taxes, depreciation, and amortization (EBITDA), and between $350 million and $950 million in EBIT.
Mixed Analyst Reactions Following Q1 Results and Guidance
- Jefferies analyst Omar Nokta maintained a Hold rating, yet raised the price target from $16 to $17.
- Clarksons Platou analyst Frode Mørkedal downgraded to Neutral.
Which Analyst has the best track record to show on ZIM?
Analyst Omar Nokta (JEFFERIES) currently has the highest performing score on ZIM with 15/23 (65.22%) price target fulfillment ratio. His price targets carry an average of $-1.11 (-6.49%) potential downside. ZIM Integrated Shipping Services stock price reaches these price targets on average within 268 days.
Daniel Heaf Named CEO as Bath & Body Works Targets Growth and Exceeds Q1 Expectations
Bath & Body Works has appointed Daniel Heaf as its new Chief Executive Officer, effective immediately. He succeeds Gina Boswell, who joined in December 2022 and had recently taken a medical leave of absence.
Heaf was most recently Nike’s Chief Transformation and Strategy Officer before the role was eliminated following leadership changes at Nike. He brings experience from leading Nike Direct, where he managed 45,000 employees and 9,000 stores across 41 countries, and from overseeing digital transformation at Burberry. Heaf has relocated to Columbus, Ohio, near Bath & Body Works’ headquarters, and has already begun engaging with company leadership.
The leadership transition comes as Bath & Body Works seeks to accelerate growth by targeting new customer segments, including tweens and men, while expanding its international footprint. Bath & Body Works also reaffirmed its full-year guidance on Monday after preannouncing stronger-than-expected first-quarter results. Revenue for Q1 rose 3% year over year to $1.42 billion, while earnings per share reached $0.49—up from $0.38 a year earlier and above internal forecasts.
Analysts Raise Price Targets Amid Leadership Change and Q1 Beat
- UBS analyst Jay Sole maintains a Neutral rating while increasing the price target from $32 to $36.
- Barclays analyst Adrienne Yih kept an Equal-Weight rating but lifted the price target from $31 to $35.
- Telsey Advisory Group analyst Dana Telsey reiterated an Outperform rating and the price target at $43.
- Citi analyst Paul Lejuez raised the price target to $42.
Which Analyst has the best track record to show on BBWI?
Analyst Matthew Boss (JPMORGAN) currently has the highest performing score on BBWI with 8/13 (61.54%) price target fulfillment ratio. His price targets carry an average of $12.35 (43.11%) potential upside. Bath & Body Works stock price reaches these price targets on average within 75 days.
JPMorgan Projects Decline in Investment Banking Fees; Provides Cautious Outlook
JPMorgan Chase reported that second-quarter investment banking fees are expected to fall by a mid-teens percentage year-over-year, declining by around 13% to 17%, according to Co-CEO Troy Rohrbaugh. Trading revenue is anticipated to rise by a mid-to-high single digit range, or approximately 5% to 9%.
Chief Financial Officer Jeremy Barnum noted that net interest income (NII) could increase by $1 billion from prior expectations, but JPMorgan maintained its 2025 full-year NII forecast at $94.5 billion. JPMorgan previously reported $90.2 billion in NII for 2024.
JPMorgan continues to target a 15% share of U.S. consumer deposits, up from its current 11.3%, and aims to expand its credit card market share from 17.3% to 20% of national spending volume. Expects net charge-off rates on credit card loans to rise from 3.6% in 2025 to between 3.6% and 3.9% in 2026.
JPMorgan’s 2025 technology budget is set at $18 billion. It plans to reduce operations headcount in consumer banking by approximately 10% over the next five years, reflecting efficiency measures and automation.
Analyst Raises Target Amid Mixed Revenue Outlook and Economic Uncertainty
- Baird analyst David George maintained a Neutral rating and raised the price target from $220 to $235.
Which Analyst has the best track record to show on JPM?
Analyst Chris Kotowski (OPPENHEIMER) currently has the highest performing score on JPM with 19/19 (100%) price target fulfillment ratio. His price targets carry an average of $20.65 (9.37%) potential upside. JPMorgan Chase stock price reaches these price targets on average within 299 days.
Daily stock Analysts Top Price Moves Snapshot
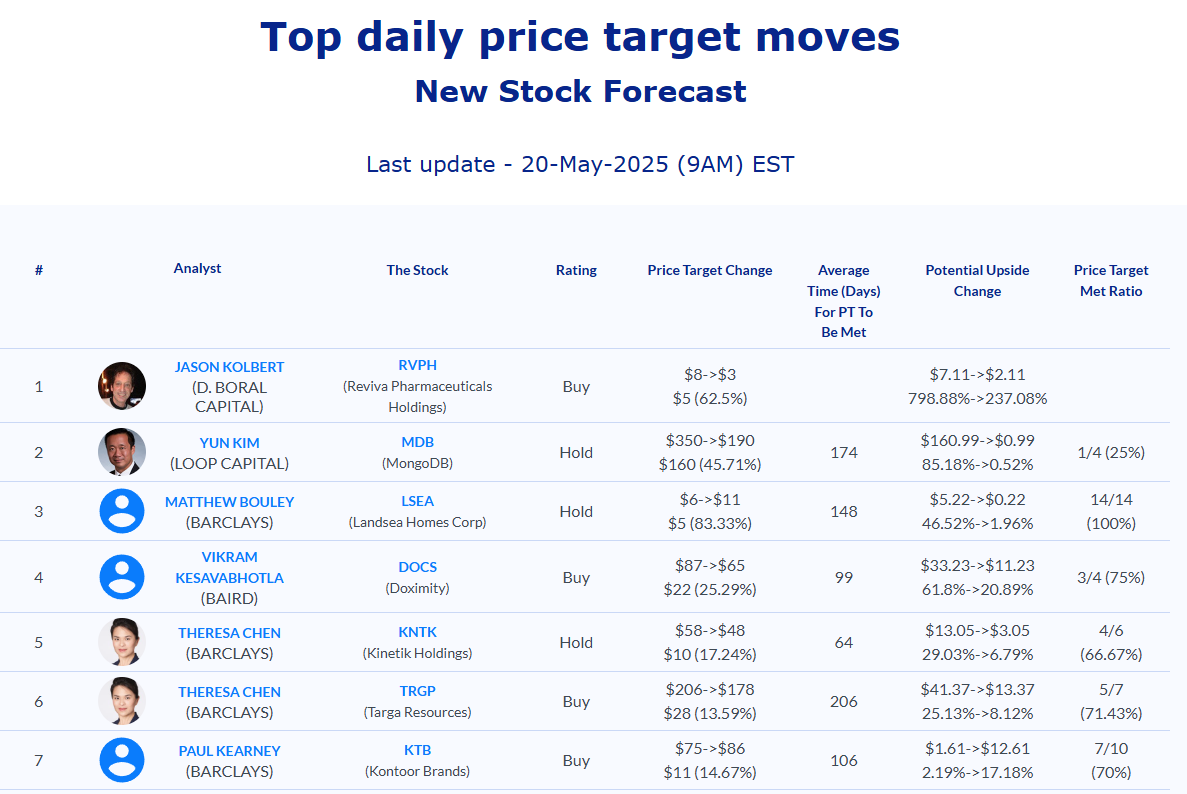
May 21, 2025: Analyst Price Target News: Palo Alto Networks, Home Depot (May 21st, 2025)
By: Matthew Otto
Palo Alto Delivers Q3 Results With Revenue and EPS Beats, Guides Above Expectations
Palo Alto Networks reported fiscal third-quarter 2025 revenue of $2.3 billion. A 15% increase from $2 billion in the prior-year period and ahead of the consensus estimate of $2.28 billion. Earnings per share were $0.8, exceeding analyst expectations by $0.03.
Net income for the quarter was $262.1 million, or $0.37 per share, compared to $278.8 million, or $0.39 per share, a year ago. Next-Generation Security annual recurring revenue rose 34% year over year to $5.1 billion, while remaining performance obligation increased 19% to $13.5 billion. Gross margin for the quarter came in at 76%, below analyst projections of 77.2%. Capital expenditures were $68.3 million, under the forecasted $70.8 million.
For the fourth quarter of fiscal 2025, Palo Alto Networks expects earnings per share between $0.87 and $0.89, compared to consensus estimates of $0.87. Also forecasts revenue in the range of $2.49 billion to $2.51 billion, closely aligned with the $2.5 billion consensus. It anticipates Next-Generation Security ARR to grow to between $5.52 billion and $5.57 billion, and remaining performance obligation to increase to $15.2 billion to $15.3 billion.
For the full year, expected revenue is in the range of $9.17 billion to $9.19 billion, representing 14% growth, with operating margin projected between 28.2% and 28.5%, and adjusted free cash flow margin between 37.5% and 38.0%.
Analyst Ratings Diverge as Price Targets Shift Post-Q3 Results
- Guggenheim analyst John Difucci reaffirmed a Sell rating and the price target at $130.
- KeyBanc analyst Eric Heath maintained an Overweight rating and price target at $220.
- Bernstein analyst Peter Weed reiterated an Outperform rating but lowered the price target from $229 to $225.
- Deutsche Bank analyst Brad Zelnick maintained a positive outlook and increased the price target from $195 to $200.
- Evercore ISI analyst Peter Levine raised the price target from $215 to $220.
- Stifel analyst Adam Borg reiterated a Buy rating and a $225 price target.
- Truist Securities analyst Joel Fishbein reiterated a Buy rating and a $205 price target.
Which Analyst has the best track record to show on PANW?
Analyst Stephen Bersey (HSBC) currently has the highest performing score on PANW with 2/4 (50%) price target fulfillment ratio. His price targets carry an average of $-12.27 (-7.29%) potential downside. Palo Alto Networks stock price reaches these price targets on average within 4 days.
Home Depot Posts Q1 Revenue Beat but Misses EPS Target, Reaffirms Full-Year Forecast
Home Depot reported first-quarter fiscal 2025 earnings per share of $3.56, missing analyst estimates by $0.03. Net earnings totaled $3.4 billion, down from $3.6 billion in the same quarter last year. Revenue came in at $39.86 billion, exceeding the consensus estimate of $39.25 billion and representing a 9.4% increase year over year.
Comparable sales declined 0.3%, including a 0.2% increase in the U.S., while foreign exchange rates negatively impacted companywide comparable sales by approximately 70 basis points. The operating margin for the quarter stood at 12.9%, compared to 13.9% in the prior-year period.
Home Depot reaffirmed its fiscal 2025 guidance, which assumes a 52-week year versus 53 weeks in fiscal 2024. Expects approximately 2.8% growth in total sales and 1% growth in comparable sales. Also anticipates opening around 13 new stores and maintaining a gross margin near 33.4%, with an operating margin of about 13%. Capital expenditures are projected to be roughly 2.5% of total sales. The effective tax rate is expected to be 24.5%, and net interest expense is forecasted at $2.2 billion. Diluted earnings per share are projected to decline approximately 3% from $14.91 in fiscal 2024, while adjusted earnings per share are expected to decline about 2% from $15.24.
Analysts Adjust Price Targets While Maintaining Ratings
- Guggenheim analyst Steven Forbes reiterated a Buy rating and a price target of $450.
- Bernstein analyst Zhihan Ma kept a Market Perform rating but raised the price target from $380 to $398.
- Baird analyst Peter S. Benedict maintained coverage while trimming the price target from $430 to $425.
Which Analyst has the best track record to show on HD?
Analyst Steven Shemesh (RBC) currently has the highest performing score on HD with 5/6 (83.33%) price target fulfillment ratio. His price targets carry an average of $30.71 (7.81%) potential upside. Home Depot stock price reaches these price targets on average within 14 days.
Bilibili Reports Strong Q1 2025 Results with Earnings Surpassing Expectations
Bilibili announced its financial results for the first quarter ended March 31, 2025, with total net revenues of $965.1 million, exceeding the consensus estimate of approximately $952.8 million. Reported earnings per share of $0.12, outperforming analyst expectations by $0.05 per share.
Gross profit increased 58% year over year to $349.9 million, with gross margin improving to 36.3% from 28.3% in the same period of 2024. Bilibili narrowed its net loss to $1.5 million, compared to a loss of approximately $89.6 million a year earlier, while operating profit reached $2.1 million, reversing the previous year’s operating loss of about $117.3 million.
Key revenue drivers included a 20% increase in advertising revenue to $275.3 million and a 76% surge in mobile game revenue to $238.6 million, fueled by the performance of the licensed game San Guo: Mou Ding Tian Xia. Value-added services contributed $386.9 million, up 11% year over year. Operating cash flow more than doubled to $179.4 million. Average daily active users rose to 106.7 million, with average daily time spent per user reaching 108 minutes.
Analyst Upgrades and Ratings Highlight Positive Outlook
- HSBC upgraded Bilibili from Hold to Buy and the price target from $21.5 to $22.5.
- Benchmark analyst Fawne Jiang reiterated a Buy rating with a $30 price target.
Which Analyst has the best track record to show on BILI?
Analyst Jiong Shao (BARCLAYS) currently has the highest performing score on BILI with 11/11 (100%) price target fulfillment ratio. His price targets carry an average of $4.91 (25.72%) potential upside. Bilibili stock price reaches these price targets on average within 47 days.
Daily stock Analysts Top Price Moves Snapshot

May 22, 2025: Analyst Price Target News: Snowflake, Wix (May 22nd, 2025)
By: Matthew Otto
Snowflake Posts Q1 Beat and Raises FY2026 Product Revenue Outlook
Snowflake reported first-quarter fiscal 2026 revenue of $1.04 billion, surpassing the consensus estimate of $1.01 billion and reflecting 26% year-over-year growth. Product revenue contributed $996.8 million, also up 26% year-over-year.
Reported earnings per share of $0.24, exceeding analyst expectations by $0.03. Net revenue retention remained strong at 124%, and Snowflake now has 606 customers with trailing 12-month product revenue greater than $1 million, a 27% increase from the prior year. Snowflake also serves 754 Forbes Global 2000 customers, up 4% year-over-year.
Remaining performance obligations totaled $6.7 billion, up 34% year-over-year. Product gross profit reached $754.1 million, representing a margin of 76%, while operating income was $91.7 million, or 9% of revenue. Adjusted free cash flow stood at $206.3 million, equivalent to 20% of revenue.
Looking ahead, Snowflake provided second-quarter fiscal 2026 guidance with product revenue expected between $1.035 billion and $1.04 billion, indicating 25% year-over-year growth. Operating income for the quarter is projected at an 8% margin, with a weighted-average share count of 371 million.
For the full fiscal year, the company raised its product revenue outlook to $4.325 billion, up from a prior target of $4.28 billion, also representing 25% annual growth. Full-year guidance includes a product gross profit margin of 75%, operating income margin of 8%, and adjusted free cash flow margin of 25%, based on 372 million diluted shares.
Analysts Boost Price Targets Following Strong Q1 and Raised Outlook
- Needham analyst Mike Cikos maintained a Buy rating and increased the price target from $215 to $230.
- Barclays analyst Raimo Lenschow lifted the price target from $203 to $219.
- Scotiabank analyst Patrick Colville raised the price target to $230.
- Stifel analyst Brad Reback kept a Buy rating and increased the price target from $210 to $220.
- Baird analyst William Power increased the price target to $215.
- Raymond James analyst Simon Leopold revised the target upward from $196 to $212.
- Wells Fargo analyst Michael Turrin raised the price target to $225.
Which Analyst has the best track record to show on SNOW?
Analyst David Hynes (CANACCORD) currently has the highest performing score on SNOW with 8/10 (80%) price target fulfillment ratio. His price targets carry an average of $55.8 (33.98%) potential upside. Snowflake stock price reaches these price targets on average within 103 days.
Accenture Drives AI and Insurance Transformation with Strategic Partnerships
Accenture, in partnership with Dell Technologies and NVIDIA, has developed an on-premises AI deployment solution targeting enterprises with strict data residency, latency, and compliance requirements. The integrated system combines Accenture’s AI Refinery™ platform with Dell infrastructure and NVIDIA AI Enterprise software. It is designed to operate within environments requiring sub-5ms latency, 99.99% uptime, and adherence to data sovereignty laws across jurisdictions such as the EU, U.S., and APAC.
According to internal benchmarks, the use of prevalidated NVIDIA Enterprise AI Factory allows Accenture to claim the designs reduces deployment time by approximately 40% and lowers five-year infrastructure costs by up to 30% compared to fully cloud-based alternatives. Modular orchestration frameworks included in the platform allow for AI model updates and redeployment cycles to be cut from several weeks to under 72 hours.
In a separate project, Accenture has signed a multi-year agreement with OP Financial Group to modernize the IT systems of Pohjola Insurance. OP Financial Group oversees more than $112.86 billion in assets and serves over 4.5 million customers. The transformation includes migrating approximately 80 insurance applications to a cloud-based Guidewire platform, consolidating legacy infrastructure, and reducing overall IT maintenance costs by an estimated 25% to 30%.
Accenture will assume responsibility for the insurance division’s application lifecycle management and implement generative AI tools expected to decrease customer inquiry response times from 3 hours to under 10 minutes. Automation initiatives are projected to eliminate 20% to 25% of manual processing across claims and policy administration. Time to market for new insurance products is expected to accelerate by 40% to 50%.
Analyst Raises Price Target Amid AI and Transformation Initiatives
- UBS analyst Kevin Mcveigh maintained a Buy rating and raised the price target from $390 to $395.
Which Analyst has the best track record to show on ACN?
Analyst Arvind Ramnani (PIPER SANDLER) currently has the highest performing score on ACN with 28/34 (82.35%) price target fulfillment ratio. His price targets carry an average of $69.76 (24.46%) potential upside. Accenture stock price reaches these price targets on average within 176 days.
Wix Tops Q1 Estimates with Revenue Growth and Strong Outlook
Wix.com reported its first quarter of 2025, with total bookings reaching $510.9 million, up 12% year-over-year, and revenue of $473.3 million, surpassing the consensus estimate of $472 million. Earnings per share came in at $1.69, exceeding analyst expectations by $0.06. Creative Subscriptions revenue rising 11% to $337.7 million and Business Solutions revenue increasing 18% to $136 million.
Partners revenue grew 24% year-over-year to $171.6 million, while transaction revenue totaled $58.9 million, up 19%. Creative Subscriptions annual recurring revenue reached $1.373 billion by quarter-end, an increase of 10% from the prior year. Free cash flow for the quarter was $142.4 million, supported by $145.5 million in operating cash and $3.1 million in capital expenditures, maintaining a 30% margin.
During the quarter, Wix repurchased $200 million worth of shares and expanded its share repurchase authorization by an additional $200 million, bringing the total to $400 million. Looking ahead, Wix expects second-quarter revenue in the range of $485 to $489 million, compared to the current consensus estimate of $488.2 million.
Full-year 2025 guidance remains unchanged, with projected bookings of $2.025 to $2.06 billion, reflecting 11% to 13% year-over-year growth, and total revenue expected to reach $1.97 to $2 billion, up 12% to 14%. Also continues to forecast $590 to $610 million in free cash flow this year and remains on track to meet its Rule of 45 target by year-end.
Analysts Maintain Buy Ratings Amid Mixed Price Target Changes
- UBS analyst Chris Zhang maintained a Buy rating but lowered the price target from $255 to $230.
- Needham analyst Bernie McTernan reiterated a Buy rating and the price target at $250.
- Cantor Fitzgerald analyst Deepak Mathivanan reiterated an Overweight rating with a $200 price target.
- Wells Fargo analyst Alec Brondolo reduced the price target to $173.
- Citi analyst Ygal Arounian maintained a Buy rating but lowered the price target from $238 to $220.
Which Analyst has the best track record to show on WIX?
Analyst Mark Zgutowicz (BENCHMARK) currently has the highest performing score on WIX with 11/13 (84.62%) price target fulfillment ratio. His price targets carry an average of $56.35 (27.67%) potential upside. Wix.com stock price reaches these price targets on average within 332 days.
Daily stock Analysts Top Price Moves Snapshot
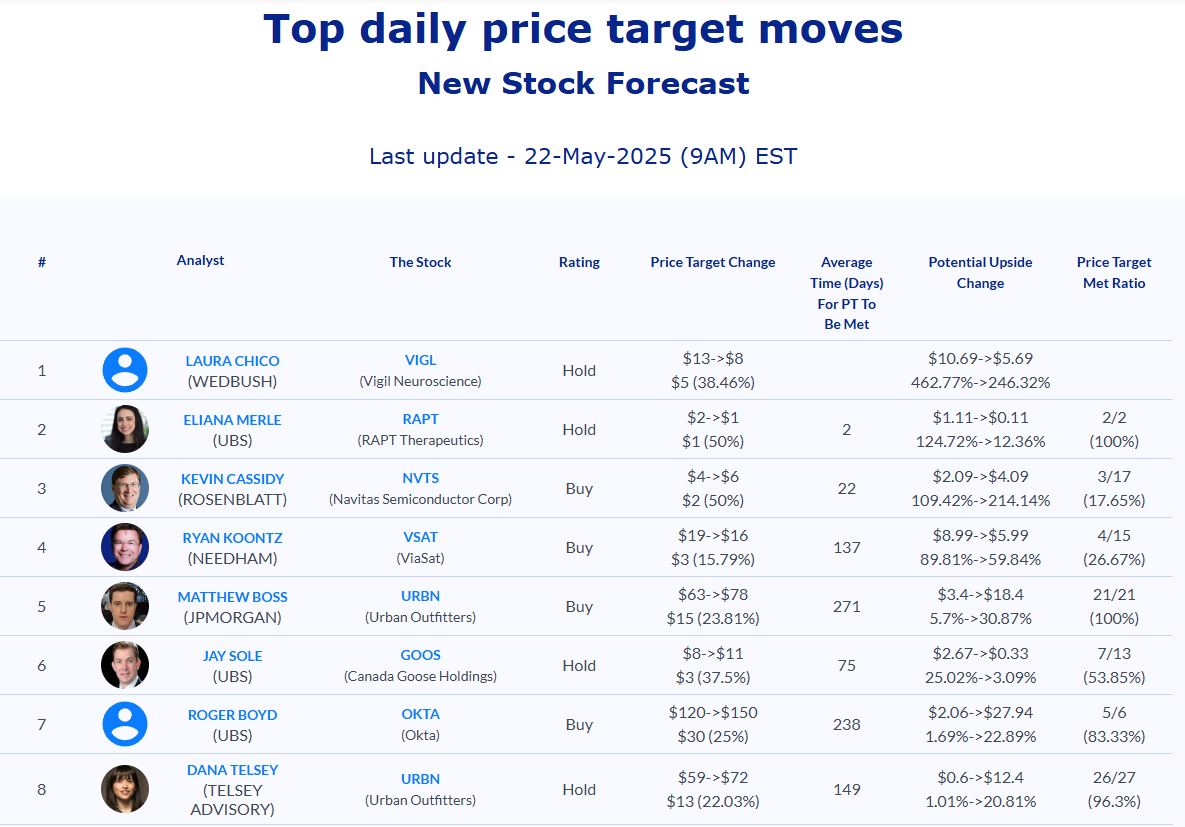
May 23, 2025: Analyst Price Target News: Analog Devices, Workday, Deckers (May 23rd, 2025)
By: Matthew Otto
Analog Devices Reports Q2 Results and Issues Upbeat Q3 Guidance Amid Market Volatility
Analog Devices (ADI) delivered its financial results for its fiscal second quarter ended May 3, 2025, with revenue of $2.64 billion surpassing the consensus estimate of $2.51 billion. Adjusted earnings per share came in at $1.85, $0.15 above analyst expectations of $1.7.
Reported 22% year-over-year revenue growth, with double-digit increases across all end markets. Gross margin rose to 61%, while operating income surged 76% to $678 million. Adjusted operating margin improved to 41.2%, and adjusted gross margin reached 69.4%.
ADI generated $819 million in operating cash flow and $729 million in free cash flow during the quarter, returning $740 million to shareholders through dividends and repurchases. Automotive sales grew 24% to $849.5 million, and consumer segment revenue rose 30%.
For the third quarter of fiscal 2025, ADI expects revenue between $2.65 billion and $2.85 billion, above the consensus forecast of $2.62 billion. Adjusted EPS is projected to range from $1.82 to $2.02, compared to analyst expectations of $1.82.
Mixed Analyst Revisions Following Q2 Beat and Q3 Outlook
- Benchmark analyst David Williams maintained a Buy rating but lowered the price target from $275 to $260.
- Needham analyst Quinn Bolton reiterated a Hold rating.
- Wells Fargo analyst Joe Quatrochi raised the price target to $205.
- Cantor Fitzgerald analyst C.J. Muse reiterated a Neutral rating with a $250 price target.
- Evercore ISI analyst Mark Lipacis raised the price target to $280 from $231.
- UBS analyst Timothy Arcuri lowered the price target to $285 from $295.
Which Analyst has the best track record to show on ADI?
Analyst Tore Svanberg (STIFEL) currently has the highest performing score on ADI with 13/14 (92.86%) price target fulfillment ratio. His price targets carry an average of $48.73 (27.65%) potential upside. Analog Devices stock price reaches these price targets on average within 491 days.
Deckers Brands Reports Revenue Growth and Strong Q4 Earnings, Issues Lower Q1 Guidance
Deckers Brands posted record financial results for fiscal year 2025, with revenue rising 16.3% to $4.99 billion and diluted earnings per share increasing 30.2% to $6.33. Growth was led by the HOKA and UGG brands, which saw annual revenue gains of 23.6% and 13.1%, respectively.
Gross margin expanded to 57.9% from 55.6%, while operating income grew to $1.18 billion from $927.5 million a year earlier. Wholesale revenue increased 17.4% to $2.86 billion, and direct-to-consumer revenue rose 14.8% to $2.13 billion. International markets drove growth with a 26.3% increase in sales to $1.8 billion, compared to 11.3% growth in domestic sales.
For the fourth quarter, Deckers reported revenue of $1.02 billion, slightly above the consensus estimate of $1.01 billion, and diluted EPS of $1, which exceeded the analyst estimate of $0.59 by $0.41. HOKA and UGG brands posted Q4 revenue increases of 10% and 3.6%, respectively. Wholesale revenue rose 12.3% year-over-year, while direct-to-consumer sales declined 1.2%. International sales grew 19.9% to $374.1 million, while domestic sales were flat at $647.7 million.
Looking ahead, Deckers guided Q1 FY 2026 revenue in the range of $890 million to $910 million, below the consensus estimate of $925.3 million. Expected EPS for the quarter is between $0.62 and $0.67, also below the consensus estimate of $0.79.
Analyst Ratings Reflect Cautious Outlook Following Fiscal 2025 Results
- Telsey Advisory Group analyst Dana Telsey downgraded from Outperform to Market Perform and the price target from $240 to $120.
- Keybanc analyst Ashley Owens lowered the rating from Overweight to Sector Weight.
- Needham analyst Tom Nikic kept a Buy rating but reduced the price target from $150 to $120.
- Truist Securities analyst Joseph Civello lowered the price target to $130 from $225.
- Stifel analyst Jim Duffy reiterated a Hold rating with a $127 price target.
- Baird analyst Jonathan Komp lowered the price target to $140.
Which Analyst has the best track record to show on DECK?
Analyst Dana Telsey (TELSEY ADVISORY) currently has the highest performing score on DECK with 21/24 (87.5%) price target fulfillment ratio. Her price targets carry an average of $112.09 (87.63%) potential upside. Deckers Brands stock price reaches these price targets on average within 86 days.
Workday Exceeds Q1 Revenue and EPS Estimates, Updates Fiscal 2026 Guidance
Workday announced first quarter fiscal 2026 results for the period ending April 30, 2025, with total revenues of $2.240 billion. This surpassed the consensus estimate of $2.22 billion and marked a 12.6% increase compared to the same quarter last year. Subscription revenues grew 13.4% to $2.059 billion. Earnings per share came in at $2.23, beating the analyst estimate of $2.01 by $0.22.
Operating income was $39 million, or 1.8% of revenues, down from $64 million, or 3.2%, in the prior year due to $166 million in restructuring expenses. Adjusting for these expenses, operating income improved to $677 million, or 30.2% of revenues, compared to $515 million, or 25.9%, in the previous year. The 12-month subscription revenue backlog increased 15.6% to $7.63 billion, while total subscription backlog rose 19.1% to $24.62 billion. Workday generated operating cash flow of $457 million and free cash flow of $421 million.
For the fiscal second quarter ending July 31, 2025, Workday expects subscription revenue of $2.16 billion, representing 13.5% growth, and an operating margin of approximately 28.0%. Updated its full fiscal year 2026 guidance with subscription revenue forecasted at $8.8 billion, up 14.0%, and an operating margin target of 28.5%. Cash, cash equivalents, and marketable securities totaled $7.97 billion at the end of the quarter.
Mixed Analyst Ratings and Price Target Following Q1 and Updated Guidance
- DA Davidson analyst Gil Luria maintained a Neutral rating and raised the price target from $230 to $250.
- Needham analyst Scott Berg reiterated a Buy rating and the price target at $300.
- WestPark Capital analyst Curtis Shauger maintained a Buy rating and increased the price target from $315 to $328.
- Piper Sandler analyst Brent Bracelin kept a Neutral rating and raised the price target from $230 to $255.
- JPMorgan analyst Mark Murphy kept an Overweight rating but lowered the price target to $295 from $310.
- Oppenheimer analyst Ken Wong lowered the price target to $300.
- Stifel analyst Brad Reback maintained a Hold rating and reduced the price target from $310 to $275.
Which Analyst has the best track record to show on WDAY?
Analyst Brad Zelnick (DEUTSCHE BANK) currently has the highest performing score on WDAY with 17/21 (80.95%) price target fulfillment ratio. His price targets carry an average of $45.31 (17.79%) potential upside. Workday stock price reaches these price targets on average within 86 days.
Daily stock Analysts Top Price Moves Snapshot

May 27, 2025: Analyst Price Target News: Booz Allen Hamilton (May 27th, 2025)
This week in analyst price targets: Booz Allen Hamilton reported FY25 results and set its FY26 guidance, drawing analyst price target revisions as investors assessed the company's government services pipeline and margin trajectory.
By: Matthew Otto
U.S. Steel’s Sale to Nippon Steel Raises U.S. Oversight Prospects and Political Stakes
U.S. Steel may come under U.S. government control if a proposed $14.9 billion acquisition by Japan’s Nippon Steel moves forward. President Donald Trump stated on Sunday that "it will be controlled by the United States," referring to the pending deal that would give Nippon Steel full ownership of U.S. Steel.
Trump also said he would not support the transaction without assurances of U.S. control, adding that the agreement was influenced by lawmakers urging him to secure the terms. Although the specific mechanism for U.S. control remains unclear, Japanese media have reported that Nippon Steel is considering issuing a golden share to the U.S. government, giving it veto power over key management decisions.
Under the terms of the deal announced on Friday, Nippon Steel plans to invest $14 billion into U.S. Steel’s domestic operations, including up to $4 billion allocated for a new steel mill. Trump claimed the merger would generate as many as 70,000 jobs.
U.S. Steel, headquartered in Pennsylvania and employing over 22,000 people, produced 14.5 million metric tons of steel in 2023, compared to Nippon Steel’s 44 million tons. The Committee on Foreign Investment in the United States (CFIUS) has reviewed the transaction twice, but a final decision has not been made.
Analyst Downgrades Reflect Caution as Acquisition Uncertainty Grows
- Jefferies analyst Christopher LeFemina downgraded from Buy to Hold, yet raised the price target from $50 to $55.
- Wolfe Research analyst Timna Tanners lowered from Outperform to Peer Perform.
Which Analyst has the best track record to show on X?
Analyst Bill Peterson (JPMORGAN) currently has the highest performing score on X with 8/9 (88.89%) price target fulfillment ratio. His price targets carry an average of $-3.82 (-9.13%) potential downside. U.S. Steel stock price reaches these price targets on average within 126 days.
Blue Bird School Bus Foundation Supports Ten Georgia Nonprofits Supporting Children’s Services
The Blue Bird School Bus Foundation, the charitable arm of Blue Bird Corporation, allocated $53,300 in donations to ten Georgia-based nonprofit organizations dedicated to supporting children's education, health, and safety.
Grants ranged from $2,500 to $12,500, with the largest award of $12,500 given to Safe Kids Central Georgia. This funding is expected to help approximately 1,000 low-income families by providing free car seats and safety education, which aim to reduce the risk of injury for children during car travel.
Since its founding in 2015, the Foundation has donated more than $600,000 to over 85 nonprofits in Georgia, impacting an estimated 50,000 children and families. Alongside financial support, Blue Bird has provided three all-electric school buses since December 2023 to organizations in Georgia, Pennsylvania, and California. The bus donated to Peach County Schools serves roughly 1,500 students by supporting daily transportation and field trips with zero-emission vehicles.
Analyst Reiterates Rating, Cites Ongoing Community Support
- Needham analyst Chris Pierce reiterated a Buy rating and a $49 price target.
Which Analyst has the best track record to show on BLBD?
Analyst Chris Pierce (NEEDHAM) currently has the highest performing score on BLBD with 2/9 (22.22%) price target fulfillment ratio. His price targets carry an average of $11.77 (31.61%) potential upside. Blue Bird Corporation stock price reaches these price targets on average within 38 days.
Booz Allen Hamilton Reports FY25 Results and Sets FY26 Guidance
Booz Allen Hamilton announced its financial results for the fourth quarter and full fiscal year 2025. Full-year revenue increased 12.4% year-over-year to $12 billion, with organic revenue growth of 11.6%. Adjusted EBITDA rose 11.9% to $1.315 billion, maintaining an EBITDA margin of 11%.
Adjusted net income grew 13.4% to $815 million, while adjusted diluted EPS increased 15.5% to $6.35. Free cash flow surged to $911 million from $192 million in the prior year. Backlog reached a record $37.0 billion, up 15.3%, supported by a trailing 12-month book-to-bill ratio of 1.39x.
In the fourth quarter, revenue totaled $2.97 billion, slightly below the consensus estimate of $3.03 billion. Adjusted diluted EPS was $1.61, exactly in line with analyst expectations. Adjusted net income increased 17.3% to $203 million, and adjusted EBITDA rose 10.5% to $316 million, with a margin improvement to 10.6%. The quarterly book-to-bill ratio was 0.71x.
For fiscal 2026, Booz Allen projects revenue between $12 and $12.5 billion, compared to the consensus of $12.04 billion, and adjusted diluted EPS in the range of $6.2 to $6.55, slightly bracketing the consensus estimate of $6.35.
Analyst Keeps Rating Despite Lowered Price Target Amid FY25 Results
- Wells Fargo analyst Matthew Akers maintained an Overweight rating but lowered the price target from $148 to $135.
Which Analyst has the best track record to show on BAH?
Analyst David Strauss (BARCLAYS) currently has the highest performing score on BAH with 11/11 (100%) price target fulfillment ratio. His price targets carry an average of $9.26 (7.08%) potential upside. Booz Allen Hamilton stock price reaches these price targets on average within 107 days.
Daily stock Analysts Top Price Moves Snapshot
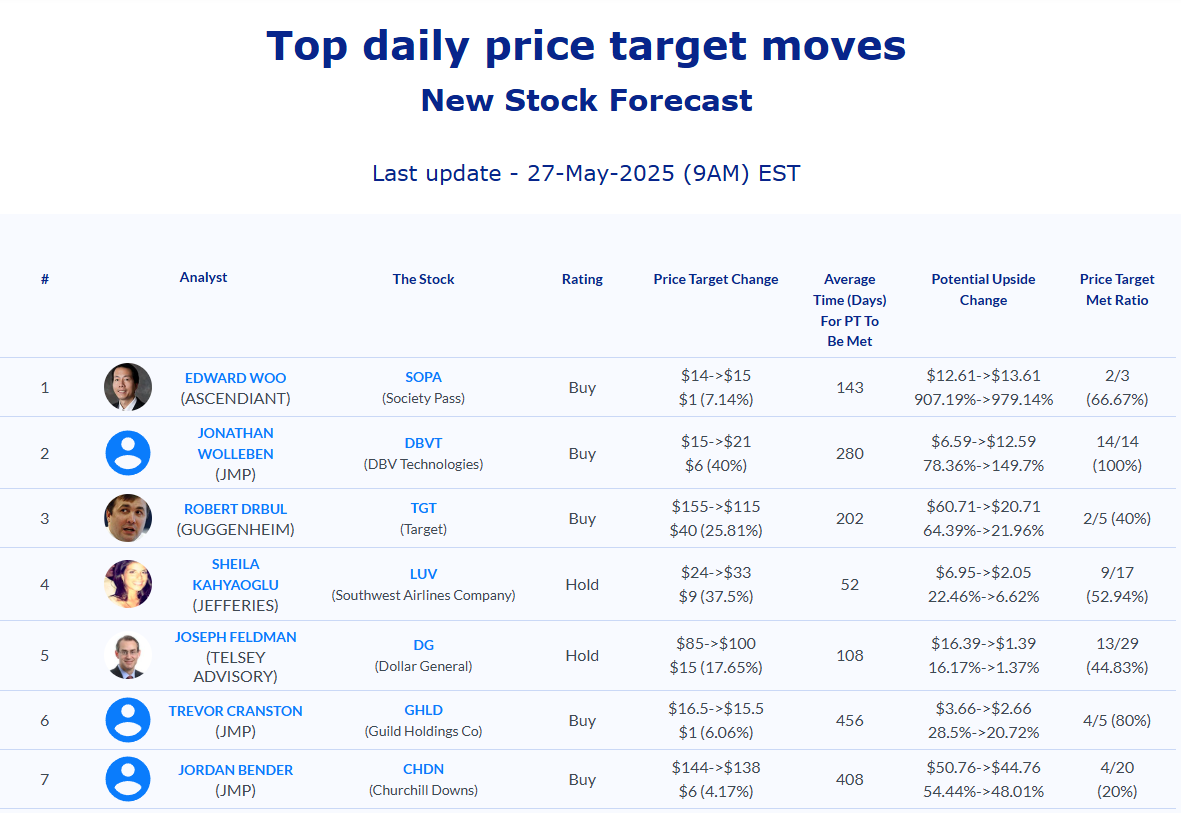
May 28, 2025: Analyst Price Target News: Okta, Salesforce Informatica Deal (May 28th, 2025)
This week in analyst price targets: Okta topped Q1 estimates but signaled slower FY26 growth, drawing cautious analyst revisions. Salesforce announced its acquisition of Informatica to expand enterprise data and AI capabilities.
By: Matthew Otto
Okta Tops Q1 Estimates but Signals Slower Growth Ahead in FY26 Outlook
Okta reported financial results for the first quarter of fiscal 2026, posting earnings per share of $0.86, beating the analyst consensus of $0.77. Revenue rose 12% year-over-year to $688 million, ahead of the $680.33 million estimate. Subscription revenue grew 12% to $673 million.
Remaining performance obligations (RPO) increased 21% year-over-year to $4.084 billion, while current RPO, expected to be recognized over the next 12 months, grew 14% to $2.227 billion. Operating income rose to $184 million, or 27% of total revenue, compared to 22% a year earlier. Net income improved to $158 million, with diluted earnings per share up from $0.65 in the prior year. Operating cash flow reached $241 million, while free cash flow totaled $238 million—both equal to 35% of revenue.
For the second quarter, Okta expects revenue between $710 million and $712 million, and earnings per share of $0.83 to $0.84. For the full fiscal year 2026, Okta projects revenue of $2.85 billion to $2.86 billion, in line with the $2.86 billion consensus, and earnings per share of $3.23 to $3.28, above the $3.2 average analyst estimate.
Analysts Mostly Positive Despite Some Price Target Cuts Following Q1 Results
- WestPark Capital analyst Casey Ryan kept a Buy rating and a price target of $140.
- Needham analyst Mike Cikos maintained a Buy rating while increasing the price target from $115 to $125.
- Evercore ISI analyst Kirk Materne raised the price target from $122 to $130.
- KeyBanc analyst Eric Heath lowered the price target from $155 to $140.
- TD Cowen analyst Shaul Eyal raised the price target from $110 to $115.
- Jefferies analyst Brent Thill trimmed the price target from $135 to $130.
- Loop Capital analyst Yun Kim reaffirmed a Buy rating and the price target at $140.
- Truist Securities analyst Joel Fishbein Jr. kept a Hold rating with a $100 price target.
- Guggenheim analyst John DiFucci cut the price target from $140 to $138.
Which Analyst has the best track record to show on OKTA?
Analyst Mike Cikos (NEEDHAM) currently has the highest performing score on OKTA with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $27.84 (31.94%) potential upside. Okta stock price reaches these price targets on average within 41 days.
DICK’S Sporting Goods Beats Q1 Estimates and Maintains Full-Year Guidance
DICK’S Sporting Goods reported first-quarter earnings per share of $3.37, exceeding the analyst estimate of $3.20 by $0.17. Revenue for the quarter reached $3.17 billion, also ahead of the $3.12 billion consensus.
Comparable sales increased 4.5%, driven by both higher average ticket and transaction volume. Operating margin was 11%, and net income totaled $264 million. DICK’S opened six new stores—two House of Sport and four Field House locations—and invested $265 million in gross capital expenditures, a 68% increase year over year. Share repurchases rose to $299 million, up 163% from the same quarter last year, while inventory levels increased 12% to $3.57 billion.
For fiscal year 2026, DICK’S reaffirmed its guidance, projecting earnings per share in the range of $13.8 to $14.4, compared to the consensus estimate of $14.34. Revenue is expected between $13.6 billion and $13.9 billion, closely aligned with the $13.86 billion analyst forecast. DICK’S declared a quarterly dividend of $1.2125 per share and reiterated plans to acquire Foot Locker in a transaction valued at approximately $2.4 billion.
Analysts Reaffirm Bullish Stance Following Q1 Beat
- Telsey Advisory Group analyst Joseph Feldman maintained an Outperform rating and the price target at $220.
- DA Davidson analyst Michael Baker reiterated a Buy rating and a $273 price target.
Which Analyst has the best track record to show on DKS?
Analyst Anthony Chukumba (LOOP CAPITAL) currently has the highest performing score on DKS with 13/13 (100%) price target fulfillment ratio. His price targets carry an average of $-4.02 (-2.18%) potential downside. DICK’S Sporting Goods stock price reaches these price targets on average within 79 days.
Salesforce to Acquire Informatica to Expand Enterprise Data and AI Capabilities
Salesforce has entered into an agreement to acquire Informatica for approximately $8 billion in equity value, net of its existing stake. The all-cash deal is expected to close in early fiscal year 2027, which begins February 1, 2026. Approximately 63% of Informatica's voting shares have approved the transaction through written consent, eliminating the need for a broader shareholder vote.
Salesforce will finance the acquisition using a mix of available cash and newly issued debt. This is Salesforce’s largest transaction since acquiring Slack Technologies for $27.7 billion in 2021, and follows previous deals including Tableau Software for $15.7 billion in 2019.
The acquisition adds Informatica’s portfolio of data integration, governance, metadata management, and Master Data Management (MDM) to Salesforce’s existing data infrastructure. Informatica currently serves over 5,000 customers, including 84 of the Fortune 100, and reported $1.6 billion in revenue for fiscal year 2023.
Analysts Maintain Positive Outlook Amid Acquisition News
- WestPark Capital analyst Curtis Shauger reiterated a Buy rating and the price target at $320.
- Needham analyst Scott Berg reaffirmed a Buy rating and a price target of $400.
- Loop Capital analyst Yun Kim maintained a Hold rating and a $300 price target.
- Morgan Stanley analyst Keith Weiss reiterated an Overweight rating and a $393 price target.
Which Analyst has the best track record to show on CRM?
Analyst Gil Luria (D.A. DAVIDSON) currently has the highest performing score on CRM with 10/11 (90.91%) price target fulfillment ratio. His price targets carry an average of $-36.26 (-15.35%) potential downside. Salesforce stock price reaches these price targets on average within 43 days.
Daily stock Analysts Top Price Moves Snapshot
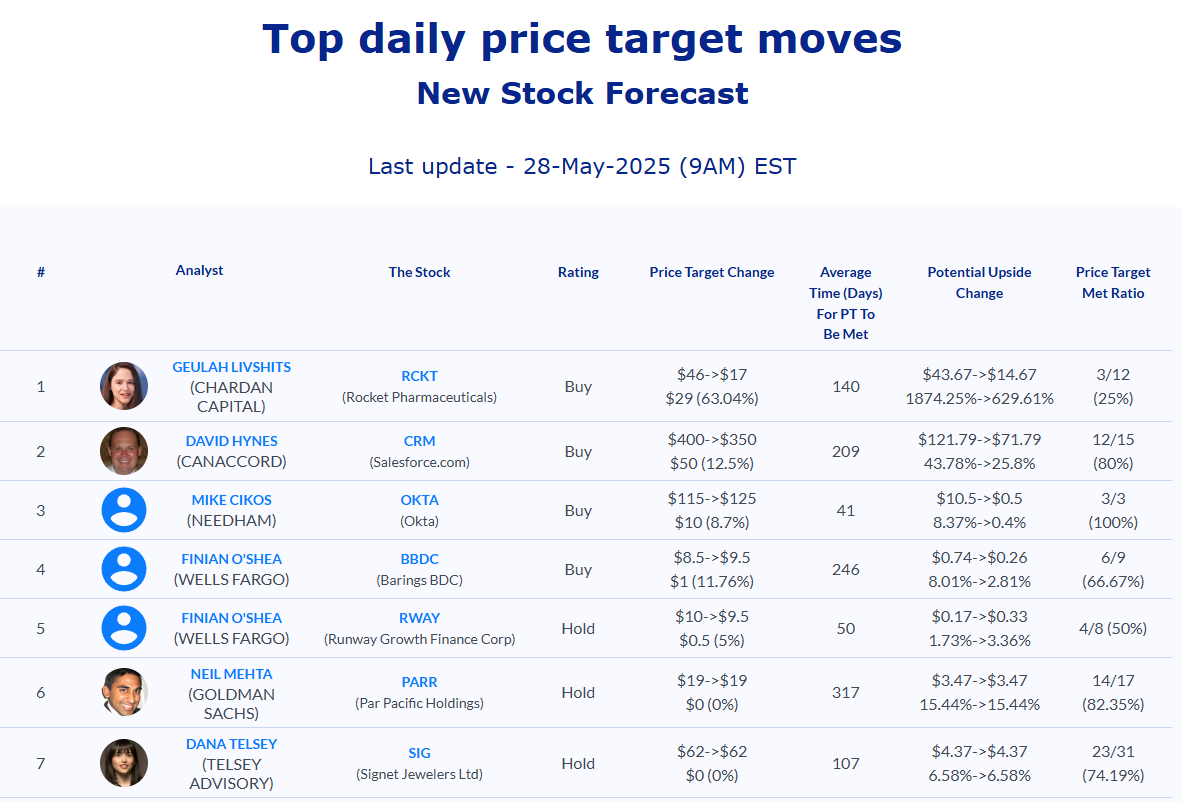
May 29, 2025: Analyst Price Target News: NVIDIA, SentinelOne, C3.ai (May 29th, 2025)
By: Matthew Otto
SentinelOne Reports Revenue Growth in Q1 FY26 but Lowers Full-Year Outlook
SentinelOne reported first quarter fiscal 2026 revenue of $229 million, up 23% year-over-year and slightly above the consensus estimate of $228.34 million. Earnings per share came in at $0.02, matching analyst expectations.
Annualized recurring revenue rose 24% to $948.1 million, while the number of customers with annual contracts over $100,000 increased 22% to 1,459. SentinelOne maintained a gross margin of 79% and improved its operating margin to negative 2% from negative 6% a year ago. Net income margin stood at 3%, compared to 0% in the prior year. Free cash flow margin rose to 20%, up two points year-over-year, and the company ended the quarter with $1.2 billion in cash, cash equivalents, and investments.
SentinelOne revised its full-year revenue guidance downward to a range of $996 million to $1.001 billion, below the previous forecast of $1.01 billion to $1.012 billion and under the $1.01 billion consensus estimate. For the second quarter of fiscal 2026, it expects revenue of $242 million, compared to the $245 million analyst consensus.
Analysts React to Revised Outlook with Downgrades and Price Target Cuts
- JP Morgan analyst Brian Essex downgraded from Overweight to Neutral and the price target from $22 to $19.
- WestPark Capital analyst Casey Ryan reiterated a Buy rating but reduced the price target from $31 to $25.
- Bernstein analyst Peter Weed maintained an Outperform rating and trimmed the price target from $27 to $25.
- Wedbush analyst Daniel Ives lowered the price target to $23.
Which Analyst has the best track record to show on S?
Analyst Rob Owens (PIPER SANDLER) currently has the highest performing score on S with 9/13 (69.23%) price target fulfillment ratio. His price targets carry an average of $9.77 (53.59%) potential upside. SentinelOne stock price reaches these price targets on average within 31 days.
NVIDIA Reports Record Q1 Revenue Amid AI Demand and China Export Setback
NVIDIA reported first-quarter fiscal 2026 revenue of $44.1 billion, up 12% from the previous quarter and 69% year-over-year, surpassing the consensus estimate of $43.31 billion. Earnings per diluted share came in at $0.76, or $0.81 excluding certain charges. Adjusted for a $4.5 billion charge related to excess inventory and purchase obligations tied to H20 chips impacted by new U.S. export restrictions, earnings per share would have been $0.96, above the analyst estimate of $0.93.
NVIDIA’s data center division, which includes AI chips, generated $39.1 billion in revenue, up 73% year-over-year and accounting for nearly 90% of total revenue. Gaming revenue hit a record $3.8 billion, up 42%, while automotive and robotics revenue rose 72% to $567 million. Net income increased 26% to $18.8 billion from the year-ago period.
Due to recent export controls on its H20 chips bound for China, NVIDIA incurred a $4.5 billion charge and was unable to ship $2.5 billion in expected revenue. Excluding this impact, product margins would have been 71.3%, compared to the reported 61%. For the second quarter, NVIDIA expects revenue of $45 billion, plus or minus 2%, below the consensus forecast of $45.21 billion. The outlook reflects an estimated $8 billion revenue loss from the H20 restriction.
Product margins are projected at around 72%, with expectations to reach the mid-70% range later in the year. Operating expenses are projected to be $5.7 billion on a reported basis and $4 billion on an adjusted basis. Other income is estimated at $450 million, and the expected tax rate is 16.5%, excluding one-time items.
Analysts Remain Bullish Following Q1 Results and Guidance
- Benchmark analyst Cody Acree reiterated a Buy rating and the price target at $190.
- Needham analyst Quinn Bolton reaffirmed a Buy rating and a $160 price target.
- Summit Insights analyst Kinngai Chan upgraded from Hold to Buy.
- Rosenblatt analyst Hans Mosesmann kept a Buy rating and boosted the price target from $178 to $200.
Which Analyst has the best track record to show on NVDA?
Analyst John Vinh (KEYBANK) currently has the highest performing score on NVDA with 21/22 (95.45%) price target fulfillment ratio. His price targets carry an average of $48.65 (37.04%) potential upside. NVIDIA stock price reaches these price targets on average within 128 days.
C3 AI Reports 26% Quarterly Revenue Growth and Expands Strategic Partnerships in FY25
C3.ai reported fourth quarter revenue of $108.7 million, up 26% year-over-year and ahead of the consensus estimate of $108.53 million. Earnings per share for the quarter came in at ($0.16), beating analyst expectations of ($0.20) by four cents.
Subscription revenue rose 9% to $87.3 million, making up 80% of total revenue. Combined subscription and prioritized engineering services revenue increased 22% to $104.4 million, representing 96% of total revenue. Gross profit for the quarter totaled $75.2 million, with a gross margin of 69%. For the full fiscal year ended April 30, 2025, revenue reached $389.1 million, an increase of 25% from the prior year, while subscription revenue rose 18% to $327.6 million.
During FY25, C3.ai closed 264 agreements—up 38% year-over-year—including 174 initial production deployment agreements, a 41% increase. C3.ai saw momentum across sectors, including more than 100% year-over-year revenue growth in both its Generative AI and State & Local Government businesses. C3 AI renewed and expanded its partnership with Baker Hughes through June 2028, and closed 193 partner-driven agreements, a 68% increase from the prior year.
Looking ahead, C3 AI expects fiscal year 2026 revenue in the range of $447.5 million to $484.5 million, compared to the analyst consensus of $466 million.
Analysts Offer Mixed Price Target Following Q4 Earnings and Guidance
- Needham analyst Mike Cikos maintained a Hold rating.
- Morgan Stanley analyst Sanjit Singh raised the price target to $22.
- Canaccord Genuity analyst David Hynes Jr. lowered the price target to $28.
- Wedbush analyst Daniel Ives reduced the price target to $35.
- DA Davidson analyst Lucky Schreiner raised the price target from $18 to $25.
Which Analyst has the best track record to show on AI?
Analyst Gil Luria (D.A. DAVIDSON) currently has the highest performing score on AI with 8/9 (88.89%) price target fulfillment ratio. His price targets carry an average of $-2.06 (-10.27%) potential downside. C3.ai stock price reaches these price targets on average within 53 days.
Daily stock Analysts Top Price Moves Snapshot
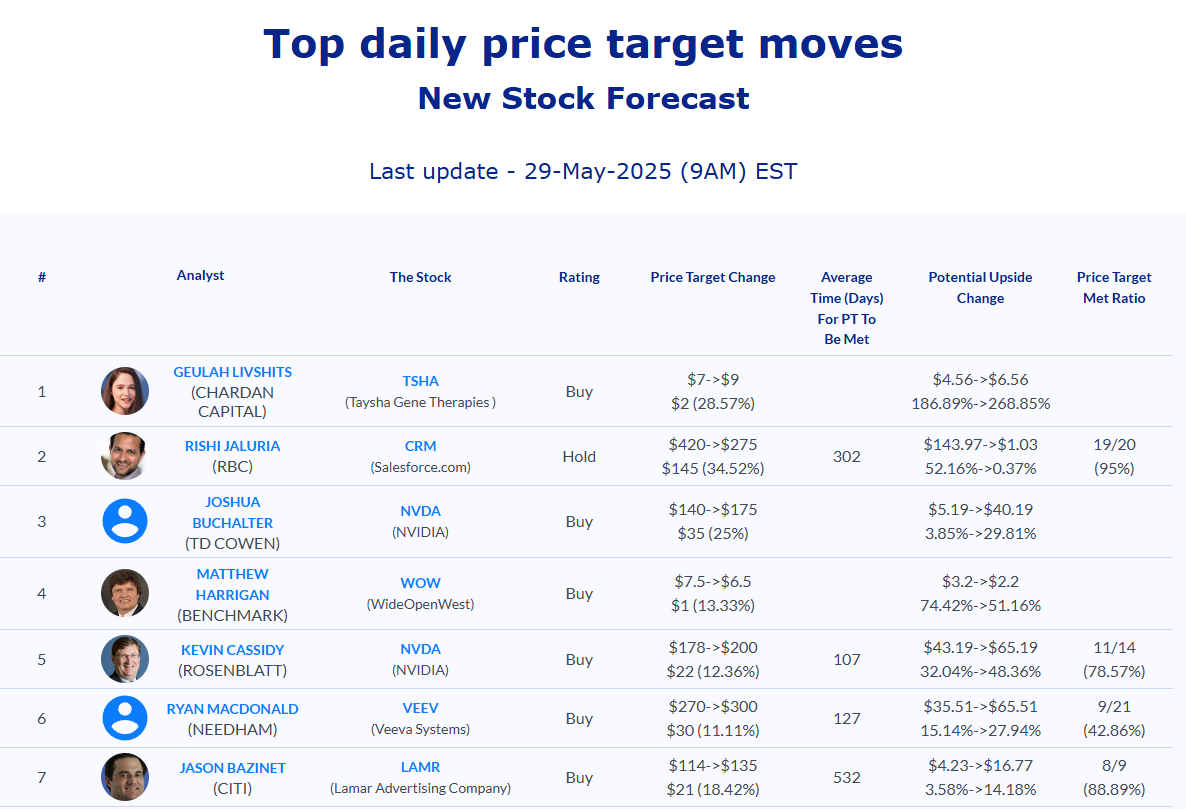
May 30, 2025: Analyst Price Target News: Marvell, Ambarella (May 30th, 2025)
By: Matthew Otto
Marvell Technology Reports Q1 FY2026 Results, Guides Above Consensus on AI-Driven Strength
Marvell Technology reported financial results for the first quarter of fiscal year 2026, posting revenue of $1.895 billion, a 63% increase year-over-year and above the consensus estimate of $1.88 billion. Also beat earnings expectations, reporting earnings per share (EPS) of $0.62, ahead of the analyst estimate of $0.61.
Net income totaled $177.9 million, while adjusted net income was $540 million. Gross margin was reported at 50.3%, with adjusted gross margin at 59.8%. Cash flow from operations reached $332.9 million.
Marvell’s data center segment led performance, generating $1.44 billion—accounting for 76% of total revenue—driven by demand for custom AI silicon and electro-optics products. However, its consumer segment declined 29% sequentially to $63.1 million, primarily due to seasonal gaming weakness, while the industrial segment saw a 12% sequential revenue decline.
For the second quarter of fiscal 2026, Marvell projects revenue of approximately $2 billion, plus or minus 5%, compared to the consensus estimate of $1.982 billion. It expects EPS of $0.67 plus or minus $0.05, in line with the analyst consensus of $0.67. Gross margin is expected to range between 50% and 51%, with total operating expenses forecast at $735 million and adjusted expenses at $495 million.
Analysts Maintain Positive Sentiment Despite Target Adjustments
- Benchmark analyst Cody Acree reiterated a Buy rating and a $95 price target.
- Needham analyst Quinn Bolton kept a Buy rating but revised the price target downward from $100 to $85.
- Evercore ISI analyst Mark Lipacis lowered his price target from $135 to $133.
- Cantor Fitzgerald analyst C.J. Muse reaffirmed a Neutral rating and a $60 price target.
- Oppenheimer analyst Rick Shafer continued to rate as Outperform and a $95 price target.
- KeyBanc analyst John Vinh maintained his Overweight rating, though trimmed the price target from $115 to $90.
Which Analyst has the best track record to show on MRVL?
Analyst Aaron Rakers (WELLS FARGO) currently has the highest performing score on MRVL with 1/2 (50%) price target fulfillment ratio. His price targets carry an average of $24.85 (21.58%) potential upside. Marvell Technology stock price reaches these price targets on average within 8 days.
Ambarella Reports Q1 FY2026 Results with Revenue Growth and Positive Earnings
Ambarella announced its financial results for the first quarter of fiscal year 2026, reporting earnings per share (EPS) of $0.07, exceeding the consensus estimate of $0.04 by $0.03. Revenue for the quarter totaled $85.9 million, beating the analyst forecast of $84.01 million and representing a 57.6% increase from $54.5 million in the same quarter last year.
Gross margin was reported at 62%, down from 63.4% a year ago. Net income reached $3 million, a turnaround from a net loss of $10.5 million in the prior-year period. Operating expenses were approximately $55.2 million, compared to $56.8 million in the previous year, reflecting improved operational efficiency. Diluted shares outstanding during the quarter totaled approximately 42.9 million.
Looking ahead, Ambarella projects second-quarter revenue in the range of $86 million to $94 million, with expected gross margin between 60.5% and 62%, and operating expenses between $52.5 million and $55.5 million. Ambarella has raised its full-year revenue growth forecast to between 19% and 25%, targeting a midpoint of approximately $348 million.
Analysts Adjust Price Targets Following Q1 FY2026 Results
- Needham analyst Quinn Bolton reaffirmed a Buy rating while lowering the price target from $110 to $90.
- Northland analyst Gus Richard raised the price target from $70 to $75.
- Stifel analyst Tore Svanberg reiterated a Buy rating with an $80 price target.
Which Analyst has the best track record to show on AMBA?
Analyst Tore Svanberg (STIFEL) currently has the highest performing score on AMBA with 19/30 (63.33%) price target fulfillment ratio. His price targets carry an average of $36.89 (85.57%) potential upside. Ambarella stock price reaches these price targets on average within 127 days.
Bath & Body Works Reports Q1 2025 Results and Reaffirms Full-Year Guidance
Bath & Body Works reported first quarter fiscal 2025 earnings per diluted share of $0.49, surpassing the analyst consensus estimate of $0.42 by $0.07. Reported net sales of $1.4 billion for the quarter ended May 3, 2025, reflecting a 2.9% increase compared to the prior year. The result was below the consensus estimate of $1.42 billion. Operating income rose to $209 million from $187 million in Q1 2024, while net income increased to $105 million from $87 million.
Looking ahead, Bath & Body Works maintained its fiscal year 2025 guidance, expecting full-year net sales growth of 1% to 3% over the $7.31 billion reported in 2024 and earnings per diluted share between $3.25 and $3.6. The guidance includes anticipated impacts from current U.S. and global tariff rates, as well as approximately $300 million allocated to share repurchases.
Bath & Body Works projects second quarter net sales to be flat to up 2% versus $1.53 billion in Q2 2024, with earnings per diluted share expected between $0.33 and $0.38. Additionally, Bath & Body Works issued preliminary fiscal 2026 guidance for earnings per diluted share of $3.25 to $3.6, compared to the current consensus estimate of $3.57.
Analysts Adjust Price Targets Amid Market Conditions
- Telsey Advisory Group analyst Dana Telsey maintained an Outperform rating, yet reduced the price target from $43 to $38.
- Morgan Stanley analyst Alex Straton lowered the price target from $43 to $41.
Which Analyst has the best track record to show on BBWI?
Analyst Jay Sole (UBS) currently has the highest performing score on BBWI with 6/9 (66.67%) price target fulfillment ratio. His price targets carry an average of $2.54 (7.59%) potential upside. Bath & Body Works stock price reaches these price targets on average within 62 days.
Daily stock Analysts Top Price Moves Snapshot
