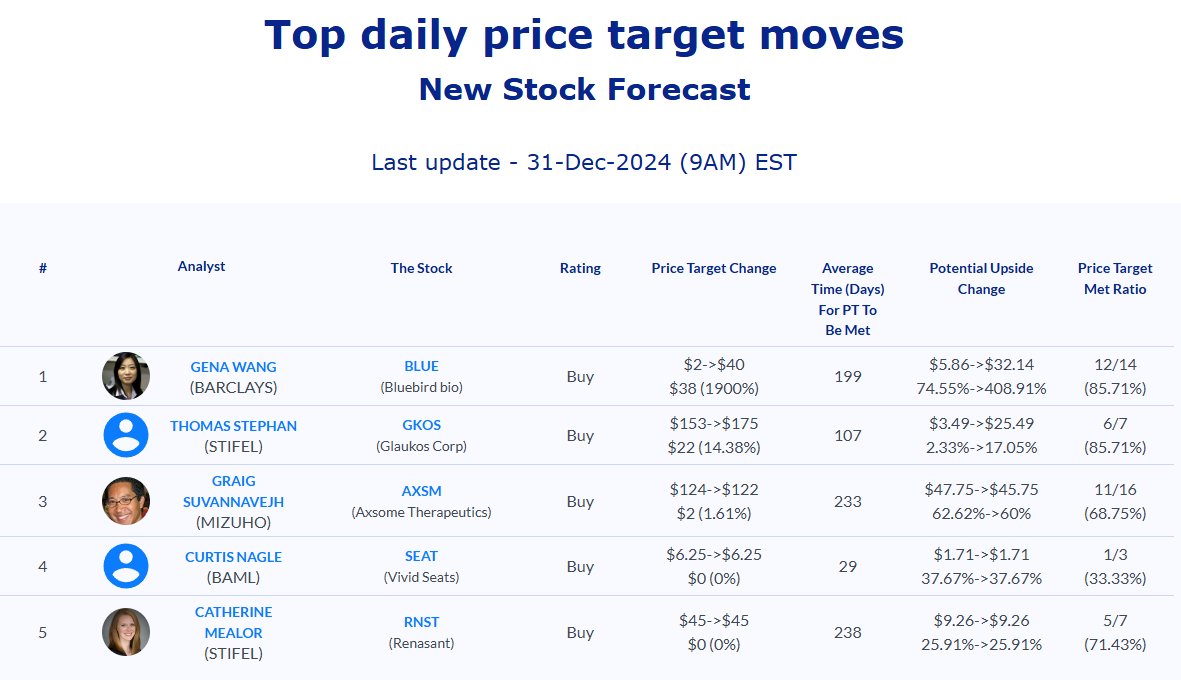
The analyst price target moves we wrote up each trading day in December 2024, 21 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
December 2, 2024: Selected stock price target news of the day: December 2nd, 2024
By: Matthew Otto
Autodesk Reports Q3 FY2025 Results: Revenue and Earnings Beat Expectations Amid Investor Concerns
Autodesk delivered solid third-quarter fiscal 2025 results, reporting adjusted earnings per share (EPS) of $2.17, beating analyst estimates by $0.05, and revenue of $1.57 billion, exceeding the consensus estimate of $1.56 billion. Additionally, Autodesk saw an 11% year-over-year revenue increase, driven by steady adoption of its design software across key industries, including construction, architecture, and animation.
Design revenue rose 9% to $1.30 billion, while revenue from the Make segment surged 28% to $171 million. Subscription revenue, which represents 97% of total revenue, grew 11%. Meanwhile, GAAP operating margin declined by 2 percentage points to 22%, and non-GAAP operating margin decreased by 3 percentage points to 36%.
Looking ahead, Autodesk provided guidance for the fourth quarter, expecting EPS between $2.10 and $2.16, compared to a consensus of $2.12. It forecasts Q4 revenue between $1.623 billion and $1.638 billion, ahead of the $1.62 billion consensus. For the full fiscal year, Autodesk raised the midpoint of its annual revenue outlook to $6.125 billion and adjusted EPS to a range of $8.29 to $8.35.
Analysts Mixed Opinions Amid Revenue and EPS Beats
- UBS analyst Taylor McGinnis initiated coverage with a Buy rating, while setting a price target of $350.
- Citigroup analyst Tyler Radke maintained a Buy rating and raised the price target from $358 to $361.
- HSBC analyst Stephen Bersey downgraded from Buy to Hold and announced a price target of $290.
- Mizuho analyst Matthew Broome kept a Neutral rating but adjusted the price target upwards from $260 to $280.
- Piper Sandler analyst Clarke Jeffries maintained a Neutral rating and raised the price target from $257 to $311.
Which Analyst has the best track record to show on ADSK?
Analyst Michael Funk (BAML) currently has the highest performing score on ADSK with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $26.6 (10.29%) potential upside. Autodesk stock price reaches these price targets on average within 105 days.
Dell Technologies Reports Q3 Revenue Growth Driven by ISG Performance and AI Demand
Dell Technologies reported fiscal Q3 2025 revenue of $24.4 billion, a 10% year-over-year increase, though it fell short of analyst expectations of $24.67 billion. Earnings per share (EPS) were $1.58, up 16%, while non-GAAP EPS came in at $2.15, surpassing the consensus estimate of $2.06.
Net income rose 12% to $1.12 billion. Operating income grew 12% to $1.7 billion on a GAAP basis and $2.2 billion non-GAAP. However, fourth-quarter guidance of $24 to $25 billion in revenue and $2.50 adjusted EPS trailed Wall Street forecasts of $25.57 billion and $2.65, respectively.
The Infrastructure Solutions Group (ISG) achieved $11.4 billion in revenue, up 34%, driven by a 58% surge in servers and networking sales to $7.4 billion, fueled by high AI demand. Dell reported $2.9 billion in AI server shipments and $3.6 billion in booked future orders.
Meanwhile, Client Solutions Group (CSG) revenue dipped 1% to $12.1 billion, with commercial client revenue rising 3% to $10.1 billion, offset by an 18% drop in consumer sales to $2 billion. Dell ended the quarter with $6.6 billion in cash and investments, alongside cash flow from operations of $1.6 billion.
Analysts Adjust Price Targets Amid Mixed Q3 Results
- Deutsche Bank analyst Sidney Ho maintained a Buy rating but adjusted the price target downward from $144 to $142.
- Melius Research analyst Ben Reitzes kept a Buy rating and raised the price target from $140 to $155.
- Mizuho analyst Vijay Rakesh retained an Outperform rating while lowering the price target from $155 to $150.
- Citigroup analyst Asiya Merchant held a Buy rating yet reduced the price target from $160 to $156.
- Barclays analyst Tim Long maintained an Equal-Weight rating and lifted the price target from $106 to $115.
- Wells Fargo analyst Aaron Rakers stayed with an Overweight rating and raised the price target from $140 to $160.
Which Analyst has the best track record to show on DELL?
Analyst Toni Sacconaghi (BERNSTEIN) currently has the highest performing score on DELL with 8/8 (100%) price target fulfillment ratio. His price targets carry an average of $24.46 (21.17%) potential upside. Dell Technologies stock price reaches these price targets on average within 133 days.
HP Reports Fiscal 2024 Results, Meets Q4 Estimates, and Issues Cautious FY2025 Guidance
HP announced its fiscal 2024 results, delivering mixed performance amidst ongoing challenges in the personal computing market. For the fourth quarter, HP reported GAAP and non-GAAP diluted EPS of $0.93, aligning with analyst expectations. Quarterly revenue reached $14.1 billion, exceeding the consensus estimate of $13.99 billion and reflecting a 1.7% year-over-year increase.
For the full fiscal year, HP’s net revenue was $53.6 billion, down 0.3% from the prior year, with non-GAAP diluted EPS of $3.38, within the guidance range of $3.35 to $3.45 and up from $3.28 in fiscal 2023.
Looking ahead, HP issued cautious guidance for fiscal 2025, expecting first-quarter adjusted EPS in the range of $0.70 to $0.76, below the consensus estimate of $0.86. For the full fiscal year, HP projects adjusted EPS between $3.45 and $3.75, with a midpoint aligned with the consensus estimate of $3.60.
Analysts Adjust Ratings and Price Targets After Fiscal 2024 Results
- HSBC analyst Stephen Bersey downgraded from Buy to Hold and the price target from $39 to $38.
- TD Cowen analyst Krish Sankar maintained a Hold rating but raised the price target from $32 to $39.
- Citigroup analyst Asiya Merchant kept a Neutral rating yet reduced the price target from $37 to $36.5.
- Barclays analyst Tim Long reiterated an Equal-Weight rating and raised the price target from $32 to $35.
Which Analyst has the best track record to show on HPQ?
Analyst Erik Woodring (MORGAN STANLEY) currently has the highest performing score on HPQ with 11/12 (91.67%) price target fulfillment ratio. His price targets carry an average of $0.54 (1.52%) potential upside. HP stock price reaches these price targets on average within 83 days.
Daily stock Analysts Top Price Moves Snapshot
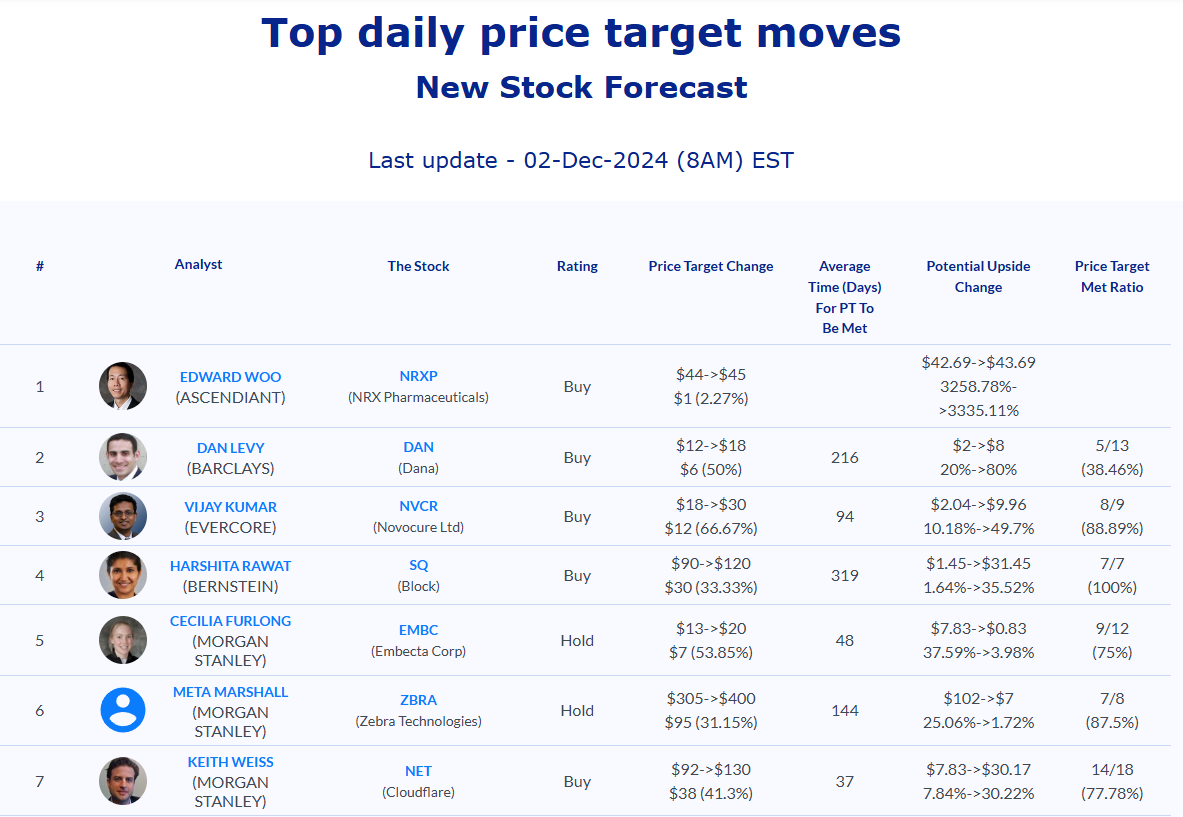
December 3, 2024: Selected stock price target news of the day: December 3rd, 2024
By: Matthew Otto
Zscaler Reports Q1 FY2025 Performance, Highlights Revenue Growth and Profitability Metrics
Zscaler delivered its financial results for the first fiscal quarter of 2025, reporting a non-GAAP earnings per share (EPS) of $0.77, exceeding analyst estimates of $0.63 by $0.14. Quarterly revenue reached $628 million, surpassing the consensus estimate of $605.43 million and representing a 26% year-over-year increase.
Other key metrics included a 13% growth in calculated billings to $516.7 million and a 27% increase in deferred revenue to $1.78 billion. Operating cash flow was $331.3 million, or 53% of revenue, while free cash flow totaled $291.9 million, or 46% of revenue.
Zscaler raised its full-year guidance, now expecting FY2025 EPS of $2.94 to $2.99, compared to the consensus estimate of $2.87. The company projects revenue to range from $2.623 billion to $2.643 billion, slightly above the consensus of $2.613 billion. For Q2 FY2025, Zscaler forecasts EPS of $0.68 to $0.69, in line with the $0.68 consensus. Revenue of $633 million to $635 million, compared to a $633.1 million consensus.
Evercore analyst, Peter Levine, remains optimistic, maintaining an Outperform rating and a $245 price target, reflecting confidence in Zscaler’s ability to capitalize on growing demand for cloud security and AI-driven solutions.
Analysts Adjust Ratings and Price Targets Following Q1 Results
- Morgan Stanley analyst Hamza Fodderwala maintained an Equal-Weight rating and lowered the price target from $215 to $205.
- Deutsche Bank analyst Patrick Colville reiterated a Buy rating and raised the price target from $200 to $225.
- Canaccord Genuity analyst Kingsley Crane upheld a Buy rating and increased the price target from $220 to $230.
- Needham analyst Mike Cikos initiated coverage with a Buy rating and a price target of $240.
Which Analyst has the best track record to show on ZS?
Analyst Keith Bachman (BMO) currently has the highest performing score on ZS with 19/22 (86.36%) price target fulfillment ratio. His price targets carry an average of $39.87 (25.37%) potential upside. Zscaler stock price reaches these price targets on average within 98 days.
Credo Technology Exceeds Q2 Estimates, Projects Up to 73% Revenue Growth for Q3 FY2025
Credo Technology Group Holding reported Q2 FY2025 results, posting a non-GAAP earnings per share (EPS) of $0.07, surpassing the consensus estimate of $0.05 by $0.02. Revenue reached $72.0 million, outpacing the analyst forecast of $67.15 million, marking a 20.6% increase and a 63.6% year-over-year growth.
GAAP gross margin was 63.2%, with the non-GAAP gross margin slightly higher at 63.6%. The company reported operating expenses at $53.9 million on a GAAP basis and $37.6 million on a non-GAAP basis. Credo concluded the quarter with a GAAP net loss of $(4.2) million, or $(0.03) per share. Offset by a non-GAAP net income of $12.3 million, or $0.07 per share. Cash and short-term investments remained at $383.0 million.
Looking forward, Credo’s Q3 FY2025 guidance projected a revenue between $115.0 million and $125.0 million, exceeding the consensus estimate of $86.0 million. Gross margins are expected to remain strong, with GAAP margins forecasted between 60.6% and 62.6%, and non-GAAP margins ranging from 61.0% to 63.0%. The company projects operating expenses at $58.6 million to $60.6 million in GAAP and $42.0 million to $44.0 million in non-GAAP.
Analysts Respond Positively to Strong Q2 and Optimistic Guidance
- Barclays analyst Thomas O'Malley maintained an Overweight rating and boosted the price target from $32 to $80.
- Needham analyst Quinn Bolton reiterated a Buy rating and raised the price target from $43 to $70.
- BofA Securities analyst Vivek Arya upgraded from Underperform to Buy and the price target from $27 to $80.
Which Analyst has the best track record to show on CRDO?
Analyst Richard Shannon (CRAIG HALLUM) currently has the highest performing score on CRDO with 4/4 (100%) price target fulfillment ratio. His price targets carry an average of $11.35 (42.59%) potential upside. Credo Technology Group Holding stock price reaches these price targets on average within 142 days.
Cytokinetics' Aficamten NDA for Obstructive HCM Accepted by FDA, Paving the Way for Potential Approval by 2025
Cytokinetics announced that the FDA has accepted its New Drug Application (NDA) for aficamten. A cardiac myosin inhibitor targeting obstructive hypertrophic cardiomyopathy (HCM). The FDA assigned a standard review process with a PDUFA target action date of September 26. 2025 and does not plan to convene an advisory committee meeting.
The NDA is supported by results from the SEQUOIA-HCM Phase 3 trial. Which showed aficamten improved exercise capacity, symptom burden, and cardiac biomarkers in patients with HCM. Over 24 weeks, patients treated with aficamten experienced a significant increase in peak oxygen uptake (1.8 mL/kg/min). This is compared to no change in the placebo group (LSM difference: 1.74 mL/kg/min, p=0.000002).
Statistically improvements were also seen across 10 secondary endpoints, including reductions in left ventricular outflow tract (LVOT) gradient and improved functional class and quality-of-life scores. Serious adverse events were lower in the aficamten group (5.6%) compared to placebo (9.3%), with minimal instances of low left ventricular ejection fraction (LVEF <50%).
Aficamten has received multiple FDA designations, including Orphan Drug Designation in January 2021 and Breakthrough Therapy Designation in December 2021. Beyond SEQUOIA-HCM, the drug is being evaluated in ongoing trials like MAPLE-HCM, ACACIA-HCM. CEDAR-HCM, targeting both obstructive and non-obstructive forms of HCM across diverse patient populations.
HCM affects an estimated 400,000 to 800,000 individuals in the U.S., with two-thirds diagnosed with the obstructive variant. SEQUOIA-HCM demonstrated aficamten's potential to address myocardial hypercontractility and improve cardiac remodeling without adversely affecting systolic function, reinforcing its potential to reshape HCM treatment.
Analysts Maintain Positive Outlook Following NDA Acceptance
- HC Wainwright & Co. analyst Joseph Pantginis reiterated a Buy rating and a $120 price target.
- Needham analyst Serge Belanger reiterated a Buy rating and the price target at $72.
- Mizuho analyst Salim Syed maintained an Outperform rating and raised his price target from $99 to $103.
Which Analyst has the best track record to show on CYTK?
Analyst Mayank Mamtani (B. RILEY) currently has the highest performing score on CYTK with 1/3 (33.33%) price target fulfillment ratio. His price targets carry an average of $43.59 (90.04%) potential upside. Cytokinetics stock price reaches these price targets on average within 50 days.
Daily stock Analysts Top Price Moves Snapshot
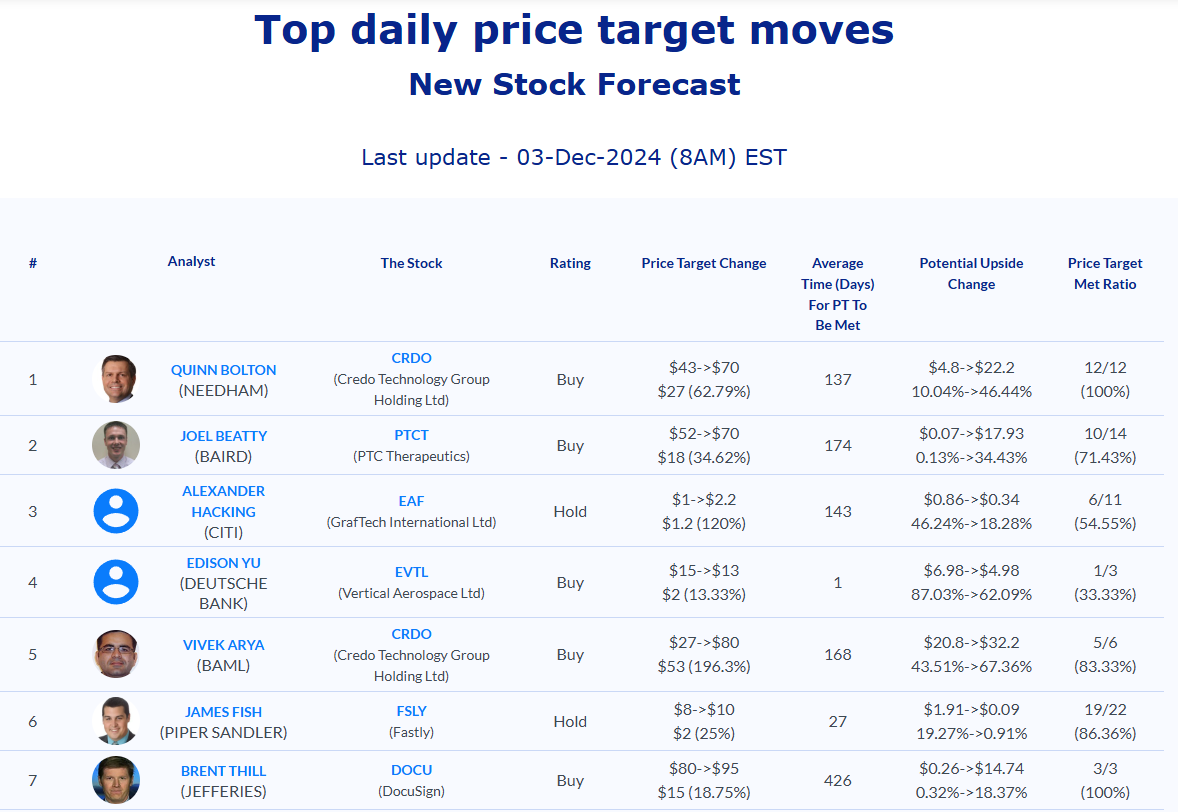
December 4, 2024: Selected stock price target news of the day: December 4th, 2024
By: Matthew Otto
Salesforce Reports Q3 FY2025 Results, Adjusts Full-Year Guidance
Salesforce reported third-quarter fiscal 2025 revenue of $9.44 billion, an 8% year-over-year increase, exceeding analysts' expectations of $9.35 billion. Subscription and support revenue grew 9% year-over-year to $8.88 billion.
Net income reached $1.5 billion, up 25% from $1.2 billion in the same period last year. Diluted earnings per share (EPS) were $2.41 on a non-GAAP basis, narrowly missing the consensus estimate of $2.44.
Operating cash flow surged 29% year-over-year to $1.98 billion, while free cash flow grew 30% to $1.78 billion. Salesforce returned $1.6 billion to shareholders during the quarter, including $1.2 billion in share repurchases and $0.4 billion in dividend payments.
For the fourth quarter, Salesforce anticipates revenue between $9.90 billion and $10.10 billion, representing 7% to 9% growth year-over-year, slightly below the analyst consensus of $10.5 billion. Adjusted EPS is projected at $2.57 to $2.62, below the $2.65 consensus.
For the full fiscal year 2025, Salesforce raised the lower end of its revenue guidance to $37.8 billion to $38.0 billion, ahead of the $37.86 billion consensus. However, adjusted EPS for FY2025 is now expected to range from $9.98 to $10.03, slightly under the $10.11 consensus.
Analysts Boost Price Targets Following Q3 FY2025 Performance
- Northland Capital Markets analyst Nehal Chokshi reiterated an Outperform rating, while raising the price target from $400 to $440.
- Baird analyst Rob Oliver maintained an Outperform rating and increased the price target from $340 to $430.
- Needham analyst Scott Berg kept a Buy rating but raised the price target from $345 to $375.
- Barclays analyst Raimo Lenschow maintained an Overweight rating and adjusted the price target from $415 to $425.
- Piper Sandler analyst Brent Bracelin reiterated the Overweight stance and revised the price target upward from $395 to $405.
- JMP Securities analyst Patrick Walravens reaffirmed a Market Outperform rating and the price target at $450.
- DA Davidson analyst Gil Luria maintained a Neutral rating yet raised the price target from $250 to $300.
Which Analyst has the best track record to show on CRM?
Analyst Gil Luria (D.A. DAVIDSON) currently has the highest performing score on CRM with 6/6 (100%) price target fulfillment ratio. His price targets carry an average of $-7.01 (-2.73%) potential downside. Salesforce stock price reaches these price targets on average within 54 days.
Marvell Beats Q3 Estimates and Projects Strong Q4 Growth
Marvell Technology posted its financial results for Q3 FY2025, with revenue of $1.516 billion, surpassing the consensus estimate of $1.45 billion. This marked a 7% year-over-year increase and exceeded the midpoint of Marvell’s prior guidance by $66 million. Adjusted EPS came in at $0.43, beating the analyst estimate of $0.41 by $0.02.
Marvell's GAAP gross margin was 23.0%, while the non-GAAP gross margin was at 60.5%. The data center segment, driven by demand for AI-specific custom silicon, contributed $1.10 billion in revenue—a 100% year-over-year increase—offsetting declines in other segments, such as enterprise networking, which fell 44%, and carrier infrastructure, down 73%.
Looking ahead, Marvell projected for Q4 FY2025 a revenue of $1.8 billion, above the consensus estimate of $1.646 billion. Marvell expects adjusted EPS of $0.59 exceeding the consensus of $0.52.
Analysts Raise Price Targets After Strong Q3 Results
- Susquehanna analyst Christopher Rolland maintained a Positive rating while lifting the price target from $110 to $125.
- Stifel analyst Tore Svanberg reiterated a Buy rating and raised the price target from $114 to $125.
- Morgan Stanley analyst Joseph Moore kept an Equal-Weight rating but increased the price target from $82 to $102.
- Evercore ISI Group analyst Mark Lipacis maintained an Outperform rating and bumped up the price target from $122 to $127.
- BofA Securities analyst Vivek Arya reaffirmed a Buy rating while boosting the price target from $108 to $125.
- Benchmark analyst Cody Acree reiterated a Buy rating and raised the price target from $115 to $135.
- Needham analyst Quinn Bolton maintained a Buy rating while adjusting the price target upward from $95 to $120.
- Barclays analyst Blayne Curtis kept an Overweight rating and elevated the price target from $85 to $115.
Which Analyst has the best track record to show on MRVL?
Analyst Toshiya Hari (GOLDMAN SACHS) currently has the highest performing score on MRVL with 8/10 (80%) price target fulfillment ratio. His price targets carry an average of $10.76 (14.11%) potential upside. Marvell Technology stock price reaches these price targets on average within 109 days.
Okta Reports Q3 Growth, Beats Estimates, and Raises Q4 and Full-Year Guidance
Okta reported its financial performance for the third quarter with total revenue reaching $665 million, a 14% increase year-over-year. Subscription revenue also grew 14% year-over-year to $651 million. Okta’s Q3 earnings per share (EPS) of $0.67 exceeded analyst expectations by $0.09, with the consensus estimate being $0.58. Revenue for the quarter came in above the consensus estimate of $649.74 million.
Remaining performance obligations (RPO), a key measure of subscription backlog, climbed 19% to $3.659 billion, while current RPO (cRPO), representing the portion expected to be recognized in the next 12 months, rose 13% to $2.062 billion. Cash flow metrics also showed robust results, with operating cash flow of $159 million and free cash flow of $154 million.
Non-GAAP operating income surged 62% year-over-year to $138 million, or 21% of revenue, compared to $85 million, or 15% of revenue, in the same quarter last year. GAAP net income reached $16 million, a reversal from a $81 million GAAP net loss in the prior year. Non-GAAP net income climbed to $121 million, translating to a diluted net income per share of $0.67, up from $0.44 in Q3 fiscal 2024.
Looking ahead, Okta raised its guidance for the fourth quarter of fiscal 2025. Okta expects EPS of $0.73 to $0.74 versus consensus of $0.67 and revenue of $667 million to $669 million versus consensus of $650.7 million. For the full year, Okta now anticipates EPS of $2.75 to $2.76 versus consensus of $2.61 and revenue of $2.595 billion to $2.597 billion versus consensus of $2.563 billion.
Analysts Respond to Strong Q3 with Upgraded Price Targets
- Truist Securities analyst Joel Fishbein reiterated a Hold rating and raised the price target from $80 to $92.
- Susquehanna analyst Shyam Patil maintained a Neutral rating, but increased the price target from $85 to $95.
- Stifel analyst Adam Borg maintained a Buy rating and lifted the price target from $108 to $115.
- Morgan Stanley analyst Simeon Gutman continued with an Overweight rating, raising the price target from $97 to $106.
- Baird analyst Shrenik Kothari maintained an Outperform rating and raised the price target from $95 to $105.
- WestPark Capital analyst Casey Ryan reiterated a Buy rating and a price target of $140.
- Needham analyst Mike Cikos kept a Buy rating and increased the price target from $100 to $115.
- Barclays analyst Saket Kalia maintained an Equal-Weight rating, with an increased price target of $96 from $81.
Which Analyst has the best track record to show on OKTA?
Analyst Simeon Gutman (MORGAN STANLEY) currently has the highest performing score on OKTA with 4/5 (80%) price target fulfillment ratio. His price targets carry an average of $18.74 (25.58%) potential upside. Okta stock price reaches these price targets on average within 17 days.
Daily stock Analysts Top Price Moves Snapshot

December 5, 2024: Selected stock price target news of the day: December 5th, 2024
By: Matthew Otto
Couchbase Beats Q3 Expectations but Faces Challenges with Lower Q4 Guidance and Cash Flow Pressures
Couchbase reported third-quarter fiscal 2025 financial results, posting an EPS of ($0.05), outperforming the consensus estimate of ($0.08) by $0.03. Revenue for the quarter totaled $51.6 million, surpassing the consensus estimate of $50.77 million and reflecting a 13% year-over-year increase.
Subscription revenue contributed $49.3 million, up 12% from the prior year. Annual recurring revenue (ARR) climbed 17% year-over-year to $220.3 million, or 16% on a constant currency basis. Remaining performance obligations (RPO) grew 29% year-over-year to $211.3 million.
Looking forward, Couchbase anticipates Q4 revenue of $52.7 to $53.5 million, below the consensus estimate of $54 million. For the full fiscal year, revenue guidance remains at $207.2 to $208.0 million, with ARR expected to range from $236.5 to $239.5 million. Non-GAAP operating loss is projected at $5.7 to $4.7 million for Q4 and $20.0 to $19.0 million for the fiscal year.
Operationally, Couchbase highlighted milestones, including Capella's growth to 15.1% of ARR and one-third of its customer base, the launch of Capella AI Services, and advancements in mobile and real-time analytics. However, Couchbase faces challenges, with negative free cash flow increasing to $17.5 million in Q3 from $13.8 million a year ago.
Analyst Ratings Reflect Mixed Sentiment Amid Guidance Concerns
- RBC Capital analyst Matthew Hedberg reiterated an Outperform rating and a $25 price target.
- DA Davidson analyst Rudy Kessinger maintained a Buy rating and the price target at $25.
- Guggenheim analyst Howard Ma also reiterated a Buy rating and set price target to $30.
- Stifel analyst Brad Reback maintained a Buy rating, though raised the price target from $20 to $22.
- Morgan Stanley analyst Sanjit Singh held an Equal-Weight rating but adjusted the price target downward from $27 to $25.
- Baird analyst Rob Oliver reiterated an Outperform rating while lowering the price target from $27 to $25.
- Needham analyst Mike Cikos kept with a Buy rating and a $22 price target.
- Piper Sandler analyst Brent Bracelin maintained an Overweight rating and a $21 price target.
Which Analyst has the best track record to show on BASE?
Analyst Sanjit Singh (MORGAN STANLEY) currently has the highest performing score on BASE with 10/12 (83.33%) price target fulfillment ratio. His price targets carry an average of $10.9 (67.70%) potential upside. Couchbase stock price reaches these price targets on average within 72 days.
Pure Storage Exceeds Q3 FY2025 Estimates, Provides Strong Guidance
Pure Storage delivered its third-quarter fiscal year 2025 results reporting earnings per share (EPS) of $0.50, outperforming analyst estimates of $0.41 by $0.09. Revenue for the quarter was $831.1 million, surpassing the consensus estimate of $815 million and marking a 9% year-over-year increase.
Subscription services revenue grew by 22% to $376.4 million, while subscription annual recurring revenue (ARR) also rose 22% to $1.6 billion. Remaining performance obligations (RPO) reached $2.4 billion, a 16% increase year-over-year.
Pure Storage posted a GAAP gross margin of 70.1% and a non-GAAP gross margin of 71.9%. Operating income was $59.7 million on a GAAP basis and $167.3 million non-GAAP, yielding operating margins of 7.2% and 20.1%, respectively. Pure Storage also generated $97.0 million in operating cash flow and $35.2 million in free cash flow, ending the quarter with $1.6 billion in cash, cash equivalents, and marketable securities.
Looking ahead, Pure Storage provided optimistic guidance, projecting Q4 FY2025 revenue of $867 million, above the consensus estimate of $856.9 million, representing a 9.7% year-over-year growth rate. For FY2025, Pure Storage expects revenue to reach $3.15 billion, exceeding the consensus estimate of $3.13 billion and reflecting an 11.5% annual growth rate.
Analyst Ratings Reflect Optimism Following Q3 FY2025 Results
- Citigroup analyst Asiya Merchant maintained a Buy rating and increased the price target from $63 to $75.
- UBS analyst David Vogt retained a Sell rating yet raised the price target from $45 to $47.
- Evercore ISI Group analyst Amit Daryanani continued with an Outperform rating and lifted the price target from $70 to $75.
- Stifel analyst Matthew Sheerin kept a Hold rating while boosting the price target from $60 to $65.
- Northland Capital Markets analyst Nehal Chokshi reiterated a Market Perform rating and elevated the price target from $59 to $63.
- Needham analyst Mike Cikos upheld a Buy rating but raised the price target from $62 to $75.
- Barclays analyst Tim Long maintained an Equal-Weight rating and adjusted the price target upward, from $56 to $61.
- Piper Sandler analyst James Fish upgraded from Neutral to Overweight and the price target from $56 to $76.
Which Analyst has the best track record to show on PSTG?
Analyst David Vogt (UBS) currently has the highest performing score on PSTG with 5/7 (71.43%) price target fulfillment ratio. His price targets carry an average of $-5.32 (-10.57%) potential downside. Pure Storage stock price reaches these price targets on average within 179 days.
Core & Main Reports Q3 2024 Financial Performance with Record Sales and Beats Q4 EPS Estimates
Core & Main reported its third-quarter financial results for fiscal 2024, highlighted by an 11.5% year-over-year increase in net sales to $2,038 million.
Gross profit rose by 9.9% to $543 million, achieving a gross margin of 26.6%, up 20 basis points from the prior quarter. However, net income declined 11.4% to $140 million, primarily due to higher interest and tax expenses. Adjusted EBITDA increased 6.5% to $277 million, with a margin of 13.6%.
For Q4, Core & Main reported an EPS of $0.69, exceeding the analyst estimate of $0.66, and revenue of $2.04 billion, surpassing the consensus estimate of $1.99 billion. Additionally, operating income increased 2.8% to $223 million, while SG&A expenses rose 14.2% to $274 million.
Looking ahead, Core & Main has raised its fiscal year 2025 guidance, forecasting revenue between $7.35 billion and $7.45 billion, in line with the analyst consensus of $7.34 billion.
Analysts Raise Price Targets Following Q3 Performance
- Wells Fargo analyst Sam Reid maintained an Overweight rating and raised the price target from $52 to $62.
- RBC Capital analyst Mike Dahl reiterated an Outperform rating and increased the price target from $53 to $62.
- Truist Securities analyst Keith Hughes kept a Hold rating but raised the price target from $38 to $56.
- Baird analyst David Manthey maintained an Outperform rating and raised the price target from $60 to $66.
- Barclays analyst Matthew Bouley held an Overweight rating and increased the price target from $57 to $65.
Which Analyst has the best track record to show on CNM?
Analyst Joe Ritchie (GOLDMAN SACHS) currently has the highest performing score on CNM with 8/9 (88.89%) price target fulfillment ratio. His price targets carry an average of $11.95 (31.41%) potential upside. Core & Main stock price reaches these price targets on average within 75 days.
Daily stock Analysts Top Price Moves Snapshot

December 6, 2024: Selected stock price target news of the day: December 6th, 2024
By: Matthew Otto
Five Below Surpasses Q3 Earnings and Revenue Expectations, Raises Full-Year Guidance
Five Below delivered its Q3 2024 results, with adjusted EPS of $0.42, surpassing analyst estimates of $0.17 by $0.25. Revenue for the quarter reached $843.7 million, exceeding the consensus estimate of $796 million and marking a 14.6% increase from $736.4 million in Q3 2023.
Comparable sales rose by 0.6%. Five Below’s adjusted operating income totaled $27.6 million, while GAAP net income was $1.7 million. Store expansion remained with 82 new locations opened during the quarter, raising the total store count to 1,749 across 44 states, representing an 18.1% year-over-year increase.
For fiscal year 2024, Five Below increased its guidance, projecting adjusted EPS of $4.78 to $4.96, exceeding the consensus estimate of $4.61. Five Below anticipates revenue of $3.84 to $3.87 billion, compared to the consensus forecast of $3.8 billion.
Year-to-date performance highlighted an 11.9% increase in net sales to $2.49 billion, despite a 2.6% decline in comparable sales. Adjusted net income for the year-to-date period was $85.5 million, with adjusted diluted EPS of $1.55.
Analysts Raise Targets as Q3 Beats Estimates and Updates Guidance
- Mizuho analyst David Bellinger kept a Neutral rating but increased the price target from $90 to $105.
- Loop Capital analyst Anthony Chukumba reiterated a Hold rating while raising the price target from $90 to $120.
- JP Morgan analyst Matthew Boss maintained an Underweight rating yet boosted the price target from $83 to $110.
- Craig-Hallum analyst Jeremy Hamblin upheld a Buy rating and elevated the price target from $125 to $150.
- Truist Securities analyst Scot Ciccarelli continued with a Hold rating and raised the price target from $88 to $118.
- Barclays analyst Karen Short kept with an Equal-Weight rating but lifted the price target from $90 to $100.
- Wells Fargo analyst Edward Kelly reaffirmed an Overweight rating and enhanced the price target from $115 to $135.
- Guggenheim analyst John Heinbockel maintained a Buy rating and raised the price target from $125 to $140.
- Morgan Stanley analyst Simeon Gutman held an Equal-Weight rating while increasing the price target from $100 to $120.
- Telsey Advisory Group analyst Joseph Feldman reiterated a Market Perform rating and adjusted the price target from $95 to $115.
Which Analyst has the best track record to show on FIVE?
Analyst Judah Frommer (CREDIT SUISSE) currently has the highest performing score on FIVE with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $23.5 (30.72%) potential upside. Five Below stock price reaches these price targets on average within 73 days.
Campbell’s Q1 FY 2025 Results Show Mixed Performance and Leadership Change Amid Market Challenges
Campbell Soup Company reported first-quarter fiscal 2025 results, with adjusted earnings per share (EPS) of $0.89, exceeding analyst estimates by $0.01. Revenue reached $2.8 billion, aligning with consensus expectations, reflecting a 10% year-over-year increase driven by the Sovos Brands acquisition.
However, organic net sales decreased 1%, impacted by flat volume/mix and a 1% decline in net price realization. Adjusted EBIT grew 6% to $432 million, supported by Sovos’ contributions, while adjusted gross profit margins fell 70 basis points to 31.4% due to inflation and acquisition-related costs. Cash flow from operations rose to $225 million, up from $174 million, benefiting from favorable working capital changes.
Looking ahead, Campbell reaffirmed its fiscal 2025 guidance, projecting EPS of $3.12 to $3.22, in line with the consensus of $3.17, and net sales growth of 9% to 11%. Campbell faces headwinds, including weak consumer spending and declining snack segment sales, which fell 2% organically year-over-year.
Analysts offered mixed perspectives: D.A. Davidson analyst Brian Holland maintained a Neutral rating with a $51 price target, highlighting Sovos’ strong performance. On the other hand, Bank of America analyst Bryan Spillane reiterated an Underperform rating and a $46 target, citing tougher growth prospects compared to industry peers.
Analysts Adjust Targets Amid Mixed Earnings
- Stifel analyst Matthew Smith maintained a Hold rating and lowered the price target from $50 to $47.
- Citigroup analyst Thomas Palmer reiterated a Sell rating and cut the price target from $44 to $41.
- RBC Capital analyst Nik Modi maintained a Sector Perform rating and the price target at $51.
- Wells Fargo analyst Chris Carey upheld an Equal-Weight rating but reduced the price target from $51 to $45.
- DA Davidson analyst Brian Holland reiterated a Neutral rating with a $51 price target.
- Stephens & Co. analyst Jim Salera reaffirmed an Overweight rating.
Which Analyst has the best track record to show on CPB?
Analyst Robert Moskow (TD COWEN) currently has the highest performing score on CPB with 23/24 (95.83%) price target fulfillment ratio. His price targets carry an average of $1.22 (2.45%) potential upside. Campbell Soup Company stock price reaches these price targets on average within 354 days.
nCino Misses Q4 Revenue Guidance Expectations, Despite Strong Q3 Results and EPS Performance
nCino reported its financial results for the third quarter of fiscal 2025, with total revenues reaching $138.8 million, a 14% increase from $121.9 million in the same period of the previous year. Revenue surpassed analyst expectations, with the consensus estimate at $137.34 million.
Subscription revenues also grew by 14%, totaling $119.9 million, up from $104.8 million in Q3 FY24. GAAP operating margin improved to -1%, up approximately 1,000 basis points year-over-year, while non-GAAP operating margin stood at 20%, reflecting a 350 basis point increase.
nCino reported Q3 EPS of $0.21, beating analyst expectations by $0.05, with the consensus estimate at $0.16. GAAP net loss for the quarter was $5.3 million, narrowing from a loss of $16.4 million a year ago, while non-GAAP net income attributable to nCino grew by 51% to $24.4 million, compared to $16.2 million in Q3 FY24.
Remaining performance obligation (RPO) reached $1.095 billion, an increase of 19% compared to $917.1 million at the same time last year, with $730 million expected to be recognized over the next 24 months. nCino’s cash position stood at $258.3 million.
Looking ahead, nCino is providing guidance for fiscal year 2025, projecting EPS of $0.75 to $0.76, above the consensus estimate of $0.62. Total revenues are expected to be between $539 million and $541 million, compared to the consensus of $541.6 million.
For Q4 FY2025, nCino expects EPS of $0.18 to $0.19, surpassing the consensus estimate of $0.17, with revenues between $139.5 million and $141.5 million, below the consensus of $143.8 million.
Analyst Ratings Mixed Following Q3 FY2025 Results
- Morgan Stanley analyst James Faucette maintained an Equal-Weight rating but lowered the price target from $41 to $39.
- Keefe, Bruyette & Woods analyst Ryan Tomasello kept an Outperform rating, yet lowered the price target from $49 to $44.
- Baird analyst Joe Vruwink maintained a Neutral rating while reducing the price target from $43 to $42.
- Stephens & Co. analyst Charles Nabhan held an Equal-Weight rating, but raised the price target from $35 to $38.
- Needham analyst Mayank Tandon kept a Buy rating and increased the price target from $40 to $45.
- Piper Sandler analyst Brent Bracelin downgraded from Overweight to Neutral, maintaining the price target at $38.
Which Analyst has the best track record to show on NCNO?
Analyst Charles Nabhan (STEPHENS) currently has the highest performing score on NCNO with 9/9 (100%) price target fulfillment ratio. His price targets carry an average of $5.26 (17.69%) potential upside. nCino stock price reaches these price targets on average within 69 days.
Daily stock Analysts Top Price Moves Snapshot
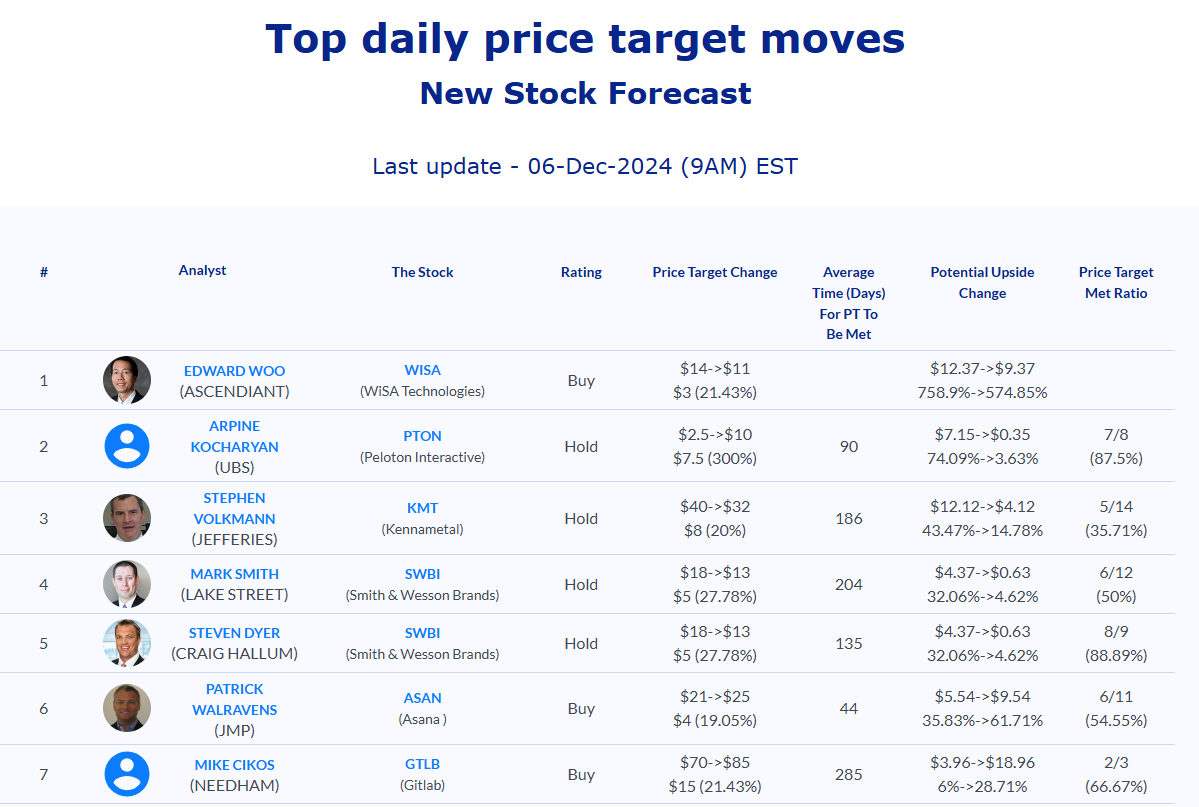
December 9, 2024: Selected stock price target news of the day: December 9th, 2024
By: Matthew Otto
Lululemon Surpasses Q3 Expectations, Raises FY2024 Outlook Amid Strong International Growth
Lululemon Athletica delivered its third-quarter fiscal 2024 results, with diluted earnings per share (EPS) of $2.87, surpassing analyst estimates of $2.71 by $0.16. Revenue for the quarter reached $2.4 billion, exceeding the consensus forecast of $2.36 billion and reflecting a 9% year-over-year increase.
Comparable sales grew 4% – 3% on a constant dollar basis, supported by international revenue growth of 33% – 30% on a constant dollar basis, while Americas' revenue rose 2%. Gross margin expanded 150 basis points to 58.5%, and income from operations climbed 45% to $490.7 million. Lululemon added 28 new stores, bringing its global total to 749.
For fiscal year 2024, Lululemon raised its guidance, projecting revenue between $10.452 billion and $10.487 billion, above the consensus of $10.42 billion and EPS of $14.08 to $14.16, compared to the prior range of $13.95 to $14.15. Fourth-quarter 2024 revenue is expected to range from $3.475 billion to $3.510 billion, narrowly beating the consensus of $3.5 billion, with EPS guidance of $5.56 to $5.64, slightly below the $5.70 consensus.
Analyst Price Target Increases Reflect Confidence in Q3 Results
- Citigroup analyst Paul Lejuez maintained a Neutral rating, yet raised the price target from $270 to $380.
- Barclays analyst Adrienne Yih maintained an Equal-Weight stance while increasing the price target from $261 to $378.
- BMO Capital analyst Simeon Siegel kept a Market Perform rating and boosted the price target from $265 to $302.
- Morgan Stanley analyst Alexandra Steiger reiterated an Overweight rating and lifted the price target from $345 to $414.
- Guggenheim analyst Robert Drbul supported a Buy rating and raised the price target from $350 to $415.
- UBS analyst Jay Sole held a Neutral rating but increased the price target from $315 to $360.
- JP Morgan analyst Matthew Boss maintained an Overweight rating while hiking the price target from $338 to $425.
- Stifel analyst Jim Duffy reiterated a Buy rating and raised the price target from $370 to $438.
- Wells Fargo analyst Ike Boruchow retained an Equal-Weight rating, yet boosted the price target from $285 to $350.
- Piper Sandler analyst Anna Andreeva maintained a Neutral rating while raising the price target from $260 to $340.
- Truist Securities analyst Joseph Civello reiterated a Buy rating and increased the price target from $360 to $420.
- Baird analyst Mark Altschwager kept an Outperform rating and lifted the price target from $380 to $440.
Which Analyst has the best track record to show on LULU?
Analyst Alexandra Walvis (GOLDMAN) currently has the highest performing score on LULU with 7/7 (100%) price target fulfillment ratio. Her price targets carry an average of $50 (21.19%) potential upside. Lululemon Athletica stock price reaches these price targets on average within 124 days.
GitLab Exceeds Q3 FY 2025 Estimates and Raises Guidance
GitLab delivered its financial results for its third quarter of fiscal year 2025, reporting a revenue of $196 million, exceeding the consensus estimate of $187.87 million and marking a 31% year-over-year increase. Earnings per share (EPS) for the quarter reached $0.23, surpassing analyst expectations of $0.15 by $0.08.
Operationally, GitLab achieved a GAAP operating margin of -15%, an improvement from -27% in the prior year, and a non-GAAP operating margin of 13%, up from 3% in Q3 FY 2024. GAAP net income was $29.6 million, a rebound from a loss of $285.2 million in the same period last year, while non-GAAP net income rose to $39.1 million from $14.4 million. GitLab also reported an improved adjusted free cash flow of $9.7 million, compared to a negative $6.7 million in Q3 FY 2024.
Looking forward, GitLab expects Q4 EPS of $0.22-$0.23, above the consensus estimate of $0.15, and revenue between $205-$206 million, exceeding the consensus of $204.8 million. For FY 2025, GitLab anticipates EPS of $0.63 to $0.64, higher than the consensus of $0.47, and revenue of $753 to $754 million, surpassing the consensus estimate of $745 million.
Analyst Price Target Increases Highlight Momentum Following Q3 Results
- DA Davidson analyst Gil Luria maintained a Neutral rating while raising the price target from $50 to $70.
- Morgan Stanley analyst Sanjit Singh kept an Overweight rating and lifted the price target from $70 to $77.
- Goldman Sachs analyst Kash Rangan held a Buy rating yet increased the price target from $80 to $88.
- Cantor Fitzgerald analyst Jonathan Ruykhaver continued with an Overweight rating and raised the price target from $75 to $80.
- JP Morgan analyst Pinjalim Bora retained a Neutral rating but boosted the price target from $60 to $65.
- RBC Capital analyst Matthew Hedberg maintained an Outperform rating while raising the price target from $73 to $80.
- Wells Fargo analyst Michael Turrin maintained an Overweight rating and lifted the price target from $75 to $80.
- Truist Securities analyst Joel Fishbein reiterated a Buy rating and raised the price target from $80 to $90.
- Baird analyst Shrenik Kothari upheld an Outperform rating while increasing the price target from $62 to $75.
- Canaccord Genuity analyst Kingsley Crane maintained a Buy rating yet elevated the price target from $65 to $78.
Which Analyst has the best track record to show on GTLB?
Analyst Matthew Hedberg (RBC) currently has the highest performing score on GTLB with 17/21 (80.95%) price target fulfillment ratio. His price targets carry an average of $13.66 (20.59%) potential upside. GitLab stock price reaches these price targets on average within 155 days.
Ulta Beauty Beats Q3 Estimates, Raises Full-Year Guidance Amid Economic Uncertainty
Ulta Beauty reported its performance for the fiscal third quarter ended November 2, 2024, with earnings per share (EPS) of $5.14, surpassing analyst expectations of $4.52 by $0.62. Net sales for the quarter reached $2.53 billion, exceeding the consensus estimate of $2.49 billion.
Comparable sales grew by 0.6%, driven by a 0.5% increase in transactions and a slight 0.1% rise in average ticket size. Despite the sales growth, net income decreased to $242.2 million from $249.5 million in the prior-year period. Gross profit as a percentage of net sales declined slightly to 39.7% from 39.9%. Selling, general, and administrative expenses increased to $682.3 million, or 27.0% of net sales.
For the first nine months of fiscal 2024, Ulta Beauty's net sales totaled $7.8 billion, a 2.0% increase compared to the same period last year. Comparable sales grew by 0.3%, while operating income decreased to $1.0 billion, or 13.4% of net sales. Ulta Beauty raised its full-year 2024 guidance, now expecting EPS between $23.20 and $23.75, up from the previous range of $22.60 to $23.50, and slightly increasing its revenue forecast to $11.1 billion to $11.2 billion, compared to the previous range of $11.0 billion to $11.2 billion.
Analyst Price Targets Raised Following Strong Q3 Results
- UBS analyst Michael Lasser maintained a Buy rating and raised the price target from $470 to $490.
- Citigroup analyst Kelly Crago held a Neutral rating and increased the price target from $390 to $450.
- Barclays analyst Adrienne Yih kept an Equal-Weight rating and upgraded the price target from $335 to $410.
- DA Davidson analyst Michael Baker maintained a Buy rating and raised the price target from $435 to $510.
- B. Riley Securities analyst Anna Glaessgen maintained a Sell rating and increased the price target from $300 to $330.
- BMO Capital analyst Simeon Siegel reiterated a Market Perform rating and increased the price target from $385 to $420.
- Oppenheimer analyst Rupesh Parikh maintained an Outperform rating and raised the price target from $435 to $505.
- JP Morgan analyst Christopher Horvers kept an Overweight rating and lifted the price target from $472 to $480.
- Stifel analyst Mark Astrachan kept a Hold rating and lifted the price target from $395 to $455.
- Wells Fargo analyst Ike Boruchow maintained an Underweight rating and raised the price target from $300 to $350.
- Piper Sandler analyst Korinne Wolfmeyer reiterated a Neutral rating and increased the price target from $360 to $390.
Which Analyst has the best track record to show on ULTA?
Analyst Ike Boruchow (WELLS FARGO) currently has the highest performing score on ULTA with 29/31 (93.55%) price target fulfillment ratio. His price targets carry an average of $-77.91 (-18.21%) potential downside. Ulta Beauty stock price reaches these price targets on average within 109 days.
Daily stock Analysts Top Price Moves Snapshot

December 10, 2024: Selected stock price target news of the day: December 10th, 2024
By: Matthew Otto
Veeva Systems Reports Q3 FY2025 Performance with Revenue Growth
Veeva Systems posted results for its fiscal third quarter ended October 31, 2024, reporting earnings per share (EPS) of $1.75, exceeding the analyst consensus estimate of $1.58 by $0.17. Revenue for the quarter reached $699.2 million, surpassing the consensus forecast of $684.34 million and marking a 13% increase compared to $616.5 million in Q3 FY2024. Subscription services revenues rose 17% year over year to $580.9 million.
Operating income grew to $181.4 million, a 41% increase from $128.5 million a year ago, while non-GAAP operating income climbed 30% to $304.0 million. Net income for the quarter was $185.8 million, a 37% year-over-year increase, with non-GAAP net income of $288.3 million.
For the upcoming fiscal Q4 2025, Veeva provided guidance of EPS at $1.57, above the consensus estimate of $1.53, and revenues between $696 million and $699 million, in line with the $697.7 million consensus. Full-year FY2025 guidance includes EPS of $6.44, exceeding the consensus of $6.24, and revenues of $2.722 to $2.725 billion, ahead of the $2.708 billion consensus.
Analyst Ratings Reflect Confidence Following Q3 Results
- Citigroup analyst Tyler Radke maintained a Buy rating while raising the price target from $281 to $307.
- Mizuho analyst Steven Valiquette kept an Outperform rating and lifted the price target from $275 to $280.
- Scotiabank analyst Allan Verkhovski maintained a Sector Perform rating yet increased the price target from $235 to $240.
- Barclays analyst Saket Kalia reiterated an Overweight rating and raised the price target from $260 to $275.
- Evercore ISI Group analyst Kirk Materne held an In-Line rating but boosted the price target from $220 to $245.
- BofA Securities analyst Brad Sills retained a Neutral rating while increasing the price target from $280 to $290.
- RBC Capital analyst Rishi Jaluria upheld an Outperform rating and elevated the price target from $275 to $285.
Which Analyst has the best track record to show on VEEV?
Analyst Saket Kalia (BARCLAYS) currently has the highest performing score on VEEV with 21/24 (87.5%) price target fulfillment ratio. His price targets carry an average of $20.67 (8.13%) potential upside. Veeva Systems stock price reaches these price targets on average within 149 days.
Asana Reports Q3 FY2025 Results and Raises Fiscal Guidance
Asana delivered its third-quarter fiscal 2025 results, with revenue of $183.9 million exceeding the consensus estimate of $180.61 million. Additionally reported adjusted net loss per share of $0.02, $0.05 better than analysts’ forecast of $0.07.
GAAP operating loss improved to $60.2 million, representing 33% of revenue, down from 38% in the prior year. On a non-GAAP basis, operating loss narrowed to $7.6 million, or 4% of revenue, compared to $9.8 million, or 6% of revenue, in Q3 FY2024.
Looking ahead, Asana raised its fiscal 2025 outlook, projecting Q4 EPS of $0.02 to $0.01, beating the consensus of $0.02. Revenue guidance for Q4 is $187.5 to $188.5 million, aligning closely with the $187.8 million consensus estimate. For FY2025, Asana now expects EPS of $0.15 to $0.14, outperforming the prior consensus of $0.19, and revenue of $723 to $724 million, above the $720.2 million consensus.
Core customer growth continued, with an 11% increase to 23,609, while high-value customers spending $100,000 or more annually rose 18% to 683. Dollar-based net retention rates for these groups were 98% and 99%, respectively.
Analyst Reactions Highlight Mixed Sentiment Amid Upbeat Q3 Results
- Scotiabank analyst Allan Verkhovski maintained a Sector Perform rating yet increased the price target from $15 to $18.
- DA Davidson analyst Lucky Schreiner retained a Neutral stance but raised the price target from $13 to $20.
- Morgan Stanley analyst Josh Baer kept an Equal-Weight rating while lifting the price target from $14 to $18.
- Oppenheimer analyst Ittai Kidron reaffirmed an Outperform rating and adjusted the price target from $20 to $22.
- JP Morgan analyst Pinjalim Bora held an Underweight rating and raised the price target from $13 to $15.
- RBC Capital analyst Rishi Jaluria reiterated an Underperform rating and the price target at $10.
- Jefferies analyst Brent Thill maintained a Hold rating and boosted the price target from $13 to $16.
- KeyBanc analyst Jackson Ader upgraded from Underweight to Sector Weight but maintained the $10 price target.
Which Analyst has the best track record to show on ASAN?
Analyst Brent Thill (JEFFERIES) currently has the highest performing score on ASAN with 13/14 (92.86%) price target fulfillment ratio. His price targets carry an average of $-5.94 (-27.07%) potential downside. Asana stock price reaches these price targets on average within 30 days.
Docusign Exceeds Q3 Expectations, Raises Revenue Guidance for FY2025
Docusign reported third-quarter fiscal 2024 earnings per share (EPS) of $0.90, surpassing analyst estimates of $0.87 by $0.03. Total revenue for the quarter reached $754.8 million, exceeding the consensus estimate of $745.26 million.
Key growth drivers included an 8% year-over-year increase in subscription revenue to $734.7 million and an 11% rise in professional services revenue to $20.1 million. Billings at $752.3 million, reflecting a 9% year-over-year increase. Profitability improved, with GAAP net income per diluted share rising to $0.30, compared to $0.19 in the same period last year. Docusign ended the quarter with $1.1 billion in cash and equivalents and executed $172.7 million in stock repurchases, more than doubling the $75 million repurchased in Q3 FY2023.
Looking ahead, Docusign forecast Q4 FY2025 revenue of $758 to $762 million, ahead of the $756.2 million consensus. For the full fiscal year 2025, Docusign projects revenue of $2.959 to $2.963 billion, above the consensus estimate of $2.947 billion.
Analysts React to Q3 Results with Raised Price Targets
- Citigroup analyst Tyler Radke maintained a Buy rating while raising the price target from $87 to $113.
- Morgan Stanley analyst Josh Baer kept an Equal-Weight rating yet lifted the price target from $62 to $97.
- UBS analyst Karl Keirstead maintained a Neutral rating but increased the price target from $60 to $100.
- RBC Capital analyst Rishi Jaluria reiterated a Sector Perform rating and raised the price target from $57 to $90.
- Wells Fargo analyst Michael Turrin upheld an Underweight rating although raising the price target from $50 to $70.
- Piper Sandler analyst Rob Owens maintained a Neutral rating and elevated the price target from $60 to $90.
- Jefferies analyst Brent Thill reaffirmed a Buy rating while lifting the price target from $95 to $115.
Which Analyst has the best track record to show on DOCU?
Analyst Brent Thill (JEFFERIES) currently has the highest performing score on DOCU with 4/5 (80%) price target fulfillment ratio. His price targets carry an average of $11.47 (11.08%) potential upside. DocuSign stock price reaches these price targets on average within 320 days.
Daily stock Analysts Top Price Moves Snapshot

December 11, 2024: Selected stock price target news of the day: December 11th, 2024
By: Matthew Otto
Oracle Reports Q2 Fiscal 2025 Results with Cloud Growth Driving Revenue Increase
Oracle announced its fiscal Q2 2025 results, reporting total revenue of $14.1 billion, below the consensus estimate of $14.12 billion. GAAP earnings per share (EPS) increased 24% year-over-year to $1.10, while non-GAAP EPS rose 10% to $1.47, falling $0.01 short of the analyst estimate of $1.48.
Cloud services and license support revenue grew 12% to $10.8 billion, accounting for 77% of total revenue. Oracle’s cloud infrastructure revenue surged 52% year-over-year to $2.4 billion, fueled by rising demand for AI-driven computing power. Total remaining performance obligations (RPO) rose by 50% to $97 billion.
Oracle reported non-GAAP net income of $4.2 billion, up 12%, with a non-GAAP operating margin of 43%. Specific segments saw growth, with Fusion Cloud ERP and NetSuite Cloud ERP revenues both reaching $0.9 billion, marking increases of 18% and 20%, respectively.
Looking ahead, Oracle anticipates revenue growth of 7% to 9%, implying approximately $14.3 billion at the midpoint—below the $14.65 billion analysts expected. Adjusted EPS is projected to range between $1.50 and $1.54, short of the $1.57 consensus.
Analysts Adjust Price Targets Amid Q2 Results and Cloud Growth
- Citigroup analyst Tyler Radke kept a Neutral rating but raised the price target from $157 to $194.
- UBS analyst Karl Keirstead maintained a Buy rating and lifted the price target from $200 to $210.
- Stifel analyst Brad Reback held a Hold rating and increased the price target from $155 to $175.
- JMP Securities analyst Patrick Walravens reiterated a Market Outperform rating and the price target at $205.
- DA Davidson analyst Gil Luria sustained a Neutral rating while boosting the price target from $140 to $150.
- RBC Capital analyst Rishi Jaluria reiterated a Sector Perform rating and the price target at $165.
- Mizuho analyst Siti Panigrahi stayed with an Outperform rating and raised the price target from $185 to $210.
Which Analyst has the best track record to show on ORCL?
Analyst Tyler Radke (CITI) currently has the highest performing score on ORCL with 10/11 (90.91%) price target fulfillment ratio. His price targets carry an average of $-0.18 (-0.11%) potential downside. Oracle stock price reaches these price targets on average within 104 days.
MongoDB Exceeds Q3 Expectations and Raises FY2025 Guidance
MongoDB reported third-quarter fiscal 2025 earnings per share (EPS) of $1.16, surpassing the analyst consensus estimate of $0.67 by $0.49. Revenue for the quarter reached $529.4 million, exceeding the consensus projection of $497.65 million and reflecting a 22% increase year-over-year.
Atlas, MongoDB’s flagship cloud database platform, contributed 68% of total revenue with a 26% year-over-year growth rate. Subscription revenue rose 22% to $512.2 million, while services revenue grew 18% to $17.2 million. Gross profit for the quarter was $394.0 million with a 74% gross margin, and on a non-GAAP basis, gross profit totaled $405.7 million with a 77% margin.
Operational improvements were evident, with free cash flow of $34.6 million and operating cash flow of $37.4 million. MongoDB's net loss narrowed to $9.8 million, or $0.13 per share, compared to a $29.3 million loss a year ago, while adjusted net income surged to $98.1 million.
Looking forward, MongoDB raised its fiscal 2025 guidance, projecting full-year revenue between $1.973 billion and $1.977 billion, higher than the consensus estimate of $1.93 billion. MongoDB also expects adjusted EPS for fiscal 2025 in the range of $3.01 to $3.03, above the consensus estimate of $2.47. For Q4 fiscal 2025, MongoDB anticipates revenue of $515 to $519 million, outpacing the $506.1 million consensus, and EPS of $0.62 to $0.65, exceeding the consensus of $0.56.
Analyst Upgrades Reflect Confidence in Q3 Performance and Raised Guidance
- Wells Fargo analyst Andrew Nowinski maintained an Overweight rating while increasing the price target from $350 to $425.
- Truist Securities analyst Miller Jump reiterated a Buy rating and raised the price target from $320 to $400.
- Keybanc analyst Eric Heath kept an Overweight rating but boosted the price target from $375 to $395.
- Stifel analyst Brad Reback maintained a Buy rating as well as raising the price target from $360 to $425.
- Oppenheimer analyst Ittai Kidron continued with an Outperform rating and increased the price target from $350 to $400.
- DA Davidson analyst Rudy Kessinger held a Buy rating and lifted the price target from $340 to $405.
- RBC Capital analyst Rishi Jaluria retained an Outperform rating while raising the price target from $350 to $400.
- Goldman Sachs analyst Kash Rangan maintained a Buy rating yet raised the price target from $340 to $390.
- Scotiabank analyst Patrick Colville kept a Sector Perform rating and elevated the price target from $295 to $350.
Which Analyst has the best track record to show on MDB?
Analyst Brent Bracelin (PIPER SANDLER) currently has the highest performing score on MDB with 25/28 (89.29%) price target fulfillment ratio. His price targets carry an average of $89.6 (26.71%) potential upside. MongoDB stock price reaches these price targets on average within 114 days.
C3.ai Reports Strong Revenue Growth and Expanded Microsoft Partnership
C3.ai posted its fiscal second-quarter results, reporting earnings per share (EPS) of $(0.06), surpassing the analyst consensus of $(0.14) by $0.08. Quarterly revenue reached $94.6 million, exceeding expectations of $91.06 million and marking a 29% year-over-year increase from $73.2 million.
Subscription revenue, which accounted for 86% of the total, grew 22% year-over-year to $81.2 million. Combined subscription and prioritized engineering services revenue constituted 96% of total revenue, rising 27% to $90.8 million. Non-GAAP gross profit was $66.3 million, reflecting a 70% margin, while the company maintained a robust cash balance of $730.4 million.
C3.ai updated its financial outlook, projecting third-quarter fiscal 2025 revenue of $95.5 million to $100.5 million, in line with the consensus estimate of $97.6 million. Full-year fiscal 2025 guidance estimates revenue between $378 million and $398 million, slightly above the consensus of $382.6 million.
Additionally, C3 AI announced a partnership with Microsoft, extending its strategic alliance to accelerate enterprise AI adoption. The agreement, valid through March 2030, establishes C3 AI as a preferred provider on Microsoft Azure and expands its sales force from under 100 to over 10,000 globally.
Analysts Price Target Adjustments Following Q2 Results
- JMP Securities analyst Aaron Kimson maintained a Market Outperform rating and raised the price target from $40 to $55.
- DA Davidson analyst Gil Luria kept a Neutral rating while increasing the price target from $35 to $40.
- Northland Capital Markets analyst Michael Latimore maintained an Outperform rating and raised the price target from $35 to $45.
- Morgan Stanley analyst Sanjit Singh upheld an Underweight rating and raised the price target from $21 to $32.
Which Analyst has the best track record to show on AI?
Analyst Kingsley Crane (CANACCORD) currently has the highest performing score on AI with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $-0.01 (-0.04%) potential downside. C3.ai stock price reaches these price targets on average within 5 days.
Daily stock Analysts Top Price Moves Snapshot

December 12, 2024: Selected stock price target news of the day: December 12th, 2024
By: Matthew Otto
Ollie’s Bargain Outlet Exceeds Q3 EPS Estimates, Reaffirms Fiscal 2024 Guidance
Ollie's Bargain Outlet Holdings reported third-quarter performance for the period ending November 2, 2024. Earnings per share (EPS) of $0.58 exceeded analyst estimates by $0.01, reflecting a 13.7% increase from the prior year. Total net sales rose 7.8% year-over-year to $517.4 million, though they fell slightly short of the $519.55 million consensus estimate.
Ollie attributed the sales growth to an expanded store footprint, with 24 new store openings offset by three closures, resulting in a year-over-year store count increase of 8.1% to 546 locations across 31 states. Comparable store sales dipped 0.5%, following a 7.0% increase in the prior year. Gross profit grew 10.5% to $214.5 million, and the gross margin improved 100 basis points to 41.4%, driven by favorable supply chain costs. Operating income reached $44.5 million, a 14.0% improvement, increasing the operating margin by 50 basis points to 8.6%.
Net income increased 12.8% to $35.9 million, or $0.58 per diluted share, and adjusted EBITDA rose 17.0% to $59.8 million, with the adjusted EBITDA margin advancing 100 basis points to 11.6%. Ollie reported liquidity with $303.9 million in cash and short-term investments and no outstanding borrowings under its $100 million credit facility.
Looking ahead, Ollie's reaffirmed its fiscal 2024 guidance, projecting annual EPS of $3.22 to $3.30, in line with the consensus of $3.27, and revenue of $2.27 to $2.28 billion, slightly below the $2.28 billion consensus.
Analysts Raise Targets Following Q3 Results
- Wells Fargo analyst Edward Kelly maintained an Equal-Weight rating and raised the price target from $95 to $105.
- Loop Capital analyst Anthony Chukumba kept a Buy rating and lifted the price target from $110 to $120.
- JP Morgan analyst Matthew Boss reiterated an Overweight rating and increased the price target from $105 to $135.
- Craig-Hallum analyst Jeremy Hamblin continued with a Buy rating while raising the price target from $107 to $130.
- BofA Securities analyst Jason Haas maintained a Buy rating and boosted the price target from $115 to $130.
- RBC Capital analyst Steven Shemesh reaffirmed an Outperform rating yesterday and raised the price target yesterday from $120 to $130.
- Truist Securities analyst Scot Ciccarelli kept a Buy rating yesterday yet increased the price target yesterday from $109 to $121.
- Piper Sandler analyst Peter Keith sustained an Overweight rating yesterday while raising the price target yesterday from $107 to $126.
Which Analyst has the best track record to show on OLLI?
Analyst Mark Carden (UBS) currently has the highest performing score on OLLI with 7/7 (100%) price target fulfillment ratio. His price targets carry an average of $9.44 (10.54%) potential upside. Ollie's Bargain Outlet Holdings stock price reaches these price targets on average within 101 days.
AutoZone Reports Q1 FY2025 Growth Despite Earnings Miss and Market Challenges
AutoZone reported net sales of $4.3 billion for the first quarter of fiscal 2025, in line with consensus estimates, but its earnings per share (EPS) of $32.52 fell short of the $33.60 expected by analysts.
Comparable sales increased by 0.4%, missing the prior year’s growth of 3.4% and just short of the 0.45% estimate. Domestic same-store sales grew by 0.3%, down from last year’s 1.2% growth and under the forecast of 0.74%, while international same-store sales rose by 1%, slower than the 25.1% growth recorded a year ago and below the expected 1.02%.
Gross profit margin improved to 53.0%, up from 52.8% last year, reflecting higher merchandise margins and in line with analysts' expectations. However, operating profit declined by 0.9% year-over-year to $841.1 million, falling short of the $848.3 million forecast.
Net income for the quarter was $564.9 million, or $32.52 per share, compared to $593.5 million, or $32.55 per share, a year ago. Autozone repurchased 160,000 shares under its buyback program, at an average price of $3,156 per share, for a total of $505.2 million. Inventory levels rose by 8.7% year-over-year, and net inventory per store stood at negative $166,000, improving from the previous year.
Analysts Raising Price Targets Following Q1 Results
- Wells Fargo analyst Zachary Fadem maintained an Overweight rating and raised the price target from $3,450 to $3,750.
- Citigroup analyst Steven Zaccone kept a Buy rating and increased the price target from $3,500 to $3,900.
- Evercore ISI Group analyst Greg Melich continued to rate as Outperform and raised the price target from $3,400 to $3,450.
- Guggenheim analyst Steven Forbes maintained a Buy rating and lifted the price target from $3,350 to $3,750.
- Truist Securities analyst Scot Ciccarelli yesterday maintained a Buy rating and yesterday raised the price target from $3,501 to $3,753.
- Mizuho analyst David Bellinger yesterday kept an Outperform rating and yesterday increased the price target from $3,350 to $3,600.
Which Analyst has the best track record to show on AZO?
Analyst Kate Mcshane (GOLDMAN SACHS) currently has the highest performing score on AZO with 16/17 (94.12%) price target fulfillment ratio. His price targets carry an average of $-236.04 (-7.49%) potential downside. AutoZone stock price reaches these price targets on average within 124 days.
Adobe Posts Strong FY2024 Results but Disappoints with Weaker FY2025 Outlook
Adobe reported financial results for fiscal year 2024, with revenue reaching $21.51 billion, marking an 11% increase year-over-year. Digital Media revenue grew to $15.86 billion, a 12% increase, while its Digital Experience segment posted $5.37 billion in revenue, up 10% year-over-year.
Adobe’s fourth-quarter results of $5.61 billion in revenue and $4.81 in non-GAAP earnings per share (EPS) came in slightly above analyst estimates of $5.54 billion and $4.67, respectively. While it expects first-quarter EPS between $4.95 and $5.00, slightly above consensus, Adobe projected revenue range of $5.63 billion to $5.68 billion that falls short of the expected $5.72 billion. For FY2025, Adobe forecasts EPS of $20.20 to $20.50, below the consensus of $20.53, and revenue between $23.3 billion and $23.55 billion, underperforming the $23.8 billion estimate.
Analysts Lower Price Targets Following Disappointing Guidance
- Jefferies analyst Brent Thill maintained a Buy rating while reducing the price target from $700 to $650.
- Deutsche Bank analyst Brad Zelnick kept a Buy rating, though lowered the price target from $650 to $600.
- BMO Capital analyst Keith Bachman maintained an Outperform rating and decreased the price target from $600 to $570.
- Mizuho analyst Gregg Moskowitz continued with an Outperform rating, but lowered the price target from $640 to $620.
- BofA Securities analyst Brad Sills maintained a Buy rating and trimmed the price target from $640 to $605.
- Stifel analyst Parker Lane reiterated a Buy rating and lowered the price target from $650 to $600.
- Oppenheimer analyst Brian Schwartz held an Outperform rating and lowered the price target from $625 to $600.
- Piper Sandler analyst Brent Bracelin maintained an Overweight rating and reduced the price target from $635 to $600.
Which Analyst has the best track record to show on ADBE?
Analyst Karl Keirstead (UBS) currently has the highest performing score on ADBE with 10/12 (83.33%) price target fulfillment ratio. His price targets carry an average of $13.13 (2.45%) potential upside. Adobe stock price reaches these price targets on average within 112 days.
Daily stock Analysts Top Price Moves Snapshot

December 13, 2024: Selected stock price target news of the day: December 13th, 2024
By: Matthew Otto
Ciena Reports Revenue Growth and Provides Optimistic Guidance
Ciena Corporation reported its fiscal fourth-quarter with adjusted earnings of $0.54 per share which fell short of analysts’ expectations of $0.65, based on FactSet data. However, revenue for the quarter ended November 2 reached $1.12 billion, exceeding the consensus estimate of $1.1 billion. Gross margin, meanwhile, declined to 40.9% from 43.1% in the same period last year.
Looking ahead, Ciena anticipates fiscal Q1 revenue between $1.01 billion and $1.09 billion, surpassing the analyst forecast of $1 billion. Ciena also projects average annual revenue growth of 8% to 11% over the next three years.
Analyst Upgrades and Price Target Adjustments Reflect Confidence in Outlook
- Northland Capital Markets analyst Tim Savageaux maintained a Market Perform rating while raising the price target from $46 to $60.
- Needham analyst Ryan Koontz maintained a Buy rating and increased the price target from $80 to $95.
- BofA Securities analyst Tal Liani upgraded from Neutral to Buy and the price target from $70 to $95.
Which Analyst has the best track record to show on CIEN?
Analyst Mark Carden (UBS) currently has the highest performing score on CIEN with 7/7 (100%) price target fulfillment ratio. His price targets carry an average of $9.44 (10.54%) potential upside. Ciena Corporation stock price reaches these price targets on average within 101 days.
Broadcom Reports Strong Q4 Results and Provides Positive Fiscal Year 2025 Guidance
Broadcom reported fourth-quarter fiscal year 2024 revenue of $14.05 billion, a 51% increase from the same period last year but slightly below the consensus estimate of $14.07 billion.
GAAP net income rose to $4.32 billion, or $0.90 per diluted share, compared to $3.52 billion, or $0.83 per share, a year earlier. Non-GAAP net income was $6.97 billion, with earnings per share of $1.42, exceeding analyst expectations of $1.39 by $0.03.
Adjusted EBITDA for the quarter was $9.09 billion, representing 65% of revenue. Broadcom generated $5.60 billion in cash from operations, achieving $5.48 billion in free cash flow, or 39% of revenue, after $122 million in capital expenditures.
In its Semiconductor Solutions segment, revenue grew 12% year-over-year to $8.23 billion, driven by a 220% surge in AI-related revenue, which totaled $12.2 billion for fiscal 2024. The Infrastructure Software segment nearly tripled revenue to $5.82 billion, aided by the integration of VMware.
Broadcom's full-year revenue reached $51.57 billion, a 44% increase, with adjusted EBITDA hitting $31.90 billion and free cash flow at $19.41 billion. For Q1 2025, Broadcom provided revenue guidance of $14.6 billion, surpassing the consensus of $14.55 billion, along with Adjusted EBITDA guidance of approximately 66% of projected revenue.
Analysts Raise Price Targets Following Q4 Results and Outlook
- Evercore ISI Group analyst Mark Lipacis maintained an Outperform rating while increasing the price target from $201 to $250.
- Baird analyst Tristan Gerra also maintained an Outperform rating and raised the price target from $195 to $210.
- Piper Sandler analyst Harsh Kumar kept an Overweight rating yet elevated the price target from $200 to $250.
- Deutsche Bank analyst Ross Seymore maintained a Buy rating and boosted the price target from $190 to $240.
Which Analyst has the best track record to show on AVGO?
Analyst Joseph Moore (MORGAN STANLEY) currently has the highest performing score on AVGO with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $43 (31.39%) potential upside. Broadcom stock price reaches these price targets on average within 223 days.
Costco Reports Q1 Fiscal 2025 Results, Beating Earnings Estimates and Driving Revenue Growth
Costco Wholesale reported financial results for the first quarter of fiscal 2025, with net sales rose 7.5% to $60.99 billion, up from $56.72 billion in the same period last year. Adjusted comparable sales, excluding gasoline price fluctuations and foreign exchange impacts, grew 7.1% company-wide, with U.S. sales at 7.2%, Canada at 6.7%, and Other International markets at 7.1%.
E-commerce sales increased by 13.2%. Net income for the quarter was $1.798 billion, or $4.04 per diluted share, surpassing last year's $1.589 billion, or $3.58 per diluted share. This quarter's results included a $100 million tax benefit from stock-based compensation, compared to a $44 million benefit in the prior year. Reported EPS of $4.04 was $0.26 higher than the analyst estimate of $3.78.
For the first quarter, Costco’s revenue of $62.15 billion exceeded analysts’ expectations of $62.08 billion but fell slightly short of the consensus estimate of $62.33 billion. Membership fee income also rose by 7.7% to $1.17 billion, boosted by an increase in annual membership fees to $65 for Gold Star members and $130 for Executive members.
Analyst Ratings and Price Target Adjustments Following Q1 Performance
- Roth MKM analyst Bill Kirk maintained a Neutral rating and raised the price target from $755 to $907.
- Evercore ISI Group analyst Greg Melich held an Outperform rating, while increasing the price target from $1020 to $1030.
- Telsey Advisory Group analyst Joseph Feldman maintained an Outperform rating and the price target at $1050.
Which Analyst has the best track record to show on COST?
Analyst Krisztina Katai (DEUTSCHE BANK) currently has the highest performing score on COST with 18/19 (94.74%) price target fulfillment ratio. Her price targets carry an average of $87.57 (10.43%) potential upside. Costco Wholesale stock price reaches these price targets on average within 144 days.
Daily stock Analysts Top Price Moves Snapshot

December 16, 2024: Selected stock price target news of the day: December 16th, 2024
By: Matthew Otto
RH Stock Rallies on Strong Outlook Despite Q3 Earnings Miss
RH posted third-quarter adjusted earnings per share (EPS) of $2.48, missing the analyst estimate of $2.66 by $0.18. Revenue for the quarter came in at $812.73 million, slightly above the consensus estimate of $812.5 million.
Looking forward, RH forecasts Q4 revenue growth of 18% to 20% year-over-year, alongside adjusted operating margins of 12.2% to 13.2% and adjusted EBITDA margins of 18.0% to 19.0%.
For the full fiscal year, RH anticipates total demand growth of 9.9% to 10.4%, revenue growth of 6.8% to 7.2%, adjusted operating margins of 11.5% to 11.7%, and adjusted EBITDA margins of 17.2% to 17.4%.
Guggenheim analyst Steven Forbes, maintaining a Buy rating since 2022, raised his price target from $425 to $550, citing increased confidence in RH’s ability to achieve peak demand trends over the next 12 to 24 months.
Analyst Upgrades Following Strong Q4 Outlook
- Stifel analyst W. Andrew Carter maintained a Buy rating and raised his price target from $420 to $500.
- Loop Capital analyst Anthony Chukumba maintained a Hold rating and lifted the price target from $320 to $450.
Which Analyst has the best track record to show on RH?
Analyst Zachary Fadem (WELLS FARGO) currently has the highest performing score on RH with 25/29 (86.21%) price target fulfillment ratio. His price targets carry an average of $67.8 (15.69%) potential upside. RH stock price reaches these price targets on average within 104 days.
Editas Shifts to In Vivo CRISPR Pipeline, Ends Reni-Cel Development Amid Workforce Reductions
Editas Medicine has announced a strategic shift to prioritize its in vivo CRISPR-edited medicines pipeline, supported by recent scientific milestones. Achieved preclinical proof of concept for hematopoietic stem cell (HSC) editing in a humanized mouse model, demonstrating ~40% efficiency in HBG1/2 promoter editing and a significant functional outcome. This shows an average of 20% fetal hemoglobin (HbF) induction in red blood cells within one month post-treatment.
This breakthrough utilized a proprietary, targeted lipid nanoparticle (tLNP) delivery system with a single dose of Cas12a editing machinery, showcasing potential for addressing sickle cell disease and beta thalassemia. Additionally, Editas demonstrated high-efficiency liver editing in non-human primates, with further data from these programs expected in Q1 2025. These achievements highlight the potential of a versatile in vivo extrahepatic LNP platform to target multiple tissues and expand the therapeutic applications of CRISPR-based gene editing.
As part of its transition, Editas is ending development of reni-cel after an extensive but unsuccessful search for a commercial partner. This shift involves a 65% reduction in workforce, aligning resources to support the in vivo pipeline and extending cash runway into Q2 2027. Clinical trials related to reni-cel, including RUBY and EdiTHAL, will be carefully concluded in collaboration with patients, regulators, and trial sites.
Analysts Adjust Ratings Amid Restructuring and Pipeline Concerns
- Evercore ISI Group analyst Liisa Bayko maintained an Outperform rating but lowered the price target from $7 to $5.
- JP Morgan analyst Brian Cheng downgraded from Neutral to Underweight.
Which Analyst has the best track record to show on EDIT?
Analyst Dae Gon Ha (STIFEL) currently has the highest performing score on EDIT with 3/7 (42.86%) price target fulfillment ratio. His price targets carry an average of $1.51 (101.34%) potential upside. Editas Medicine stock price reaches these price targets on average within 28 days.
NIKE and NFL Announce 10-Year Partnership Extension to Drive Global Growth, Innovation, and Player Safety
NIKE and the National Football League (NFL) have announced a 10-year partnership extension, building on 12 years of successful collaboration. Since 2012, Nike has served as the exclusive provider of uniforms and sideline, practice, and baselayer apparel for all 32 NFL teams.
The new agreement aims to deliver cutting-edge, high-performance products that cater to the evolving needs of elite NFL athletes. Nike will continue to drive growth and innovation across the sport, with a focus on expanding the NFL’s global reach to over 180 countries, increasing participation, and growing the fan base. This collaboration also promises to enhance safety and performance, improving player health through advancements in footwear and apparel technology.
Key initiatives of the partnership include a continued commitment to player health and safety, leveraging Nike’s Sport Research Lab and product design expertise to address lower extremity injuries. Nike will also support grassroots, high school, and collegiate football development, investing in youth programs and fostering a new generation of athletes.
Additionally, Nike will focus on global expansion, aiming to further engage the 200 million-plus football fans worldwide. With the renewal, the partnership will also drive innovative fan experiences through storytelling and marketing, creating deeper connections with audiences.
Analysts Adjust Price Targets Amid Continued Partnership Growth
- Wells Fargo analyst Ike Boruchow maintained an Overweight rating and lowered the price target from $95 to $92.
- Evercore ISI Group analyst Michael Binetti kept an Outperform rating and reduced the price target from $105 to $97.
- Deutsche Bank analyst Krisztina Katai maintained a Buy rating and lowered the price target from $92 to $82.
- Telsey Advisory Group analyst Cristina Fernandez held an Outperform rating and adjusted the price target from $96 to $93.
Which Analyst has the best track record to show on NKE?
Analyst Randal Konik (JEFFERIES) currently has the highest performing score on NKE with 12/21 (57.14%) price target fulfillment ratio. His price targets carry an average of $-3.4 (-3.85%) potential downside. Nike stock price reaches these price targets on average within 144 days.
Daily stock Analysts Top Price Moves Snapshot

December 17, 2024: Selected stock price target news of the day: December 17th, 2024
By: Matthew Otto
Tesla Advances in Autonomous Driving and Prepares for New Product Launches
Tesla continues to make advancements in autonomous driving technology, bolstered by ongoing improvements to its Full Self-Driving (FSD) software. The AI-driven system, designed to allow vehicles to perform most driving tasks with human supervision, is evolving steadily.
Wedbush analyst Dan Ives highlighted the transformational potential of Tesla’s autonomous initiatives, calling them a “game changer” under policies expected in a potential second Trump administration. Progress in this field is evident not only from Tesla but also from competitors like Alphabet’s Waymo, which completes over 150,000 driverless rides weekly. Ives projects that Tesla’s focus on AI and autonomy could help position the company as a leader in the rapidly growing market for self-driving services. This includes the planned rollout of its robotaxi platform in late 2025.
In addition to its autonomy efforts, Tesla is set to launch a new, lower-cost electric vehicle (EV) in 2024. Mizuho analyst Vijay Rakesh cited self-driving cars as a core reason for his bullish outlook, emphasizing Tesla’s ability to remain ahead of competitors in integrating AI with transportation. ChartSmarter founder Douglas Busch noted that belief in Tesla’s long-term growth story is fueling enthusiasm for its future plans.
Analyst Upgrades Amid Autonomous Driving Advances
- Mizuho analyst Vijay Rakesh upgraded from Neutral to Outperform and raised the price target from $230 to $515.
- Wedbush analyst Daniel Ives yesterday maintained an Outperform rating and raised the price target from $400 to $515,
Which Analyst has the best track record to show on TSLA?
Analyst Andres Sheppard (CANTOR FITZGERALD) currently has the highest performing score on TSLA with 24/25 (96%) price target fulfillment ratio. His price targets carry an average of $-35.99 (-8.98%) potential downside. Tesla stock price reaches these price targets on average within 18 days.
Viridian's Veligrotug Shows Breakthrough Results in TED Phase 3 Trial, Benefiting Thousands Globally
Viridian Therapeutics has unveiled promising topline results from the THRIVE-2 global phase 3 trial evaluating veligrotug (VRDN-001) in chronic thyroid eye disease (TED). A condition affecting an estimated 100,000 patients annually in the U.S. alone.
The trial enrolled 188 participants, with 125 receiving veligrotug and 63 on placebo. At the 15-week primary analysis. Veligrotug achieved a proptosis responder rate (PRR) of 56%, translating to 70 patients benefiting from significant reductions in eye protrusion. This represented a placebo-adjusted rate of 48% (p < 0.0001) and a mean reduction of 2.34 mm.
In addition, 56% of veligrotug-treated patients (70 individuals) experienced a meaningful diplopia response. Compared to 25% (16 individuals) in the placebo group, with a placebo-adjusted rate of 31% (p = 0.0006). Furthermore, 32% of veligrotug patients (40 individuals) achieved complete resolution of diplopia. Compared to 14% (9 individuals) in the placebo group (18% placebo-adjusted, p = 0.0152). Importantly, veligrotug was well-tolerated, with 94% (118 participants) completing the treatment regimen. Adverse events were minimal, with a 9.6% placebo-adjusted rate of hearing impairment.
Preparations for a Biologics License Application (BLA) submission are underway, targeting the second half of 2025. Meanwhile, Viridian continues to advance VRDN-003, a subcutaneous anti-IGF-1R antibody, in its phase 3 REVEAL-1 and REVEAL-2 trials. With topline data anticipated in the first half of 2026 and a BLA submission planned by year-end. VRDN-003 could provide additional options for TED patients through an at-home, low-volume, infrequent dosing regimen.
Analysts Reaffirm Positive Outlook Following Trial Results
- HC Wainwright & Co. analyst Douglas Tsao reiterated a Buy rating and a $34 price target.
- Oppenheimer analyst Leland Gershell reiterated an Outperform rating and a $28.00 price target.
Which Analyst has the best track record to show on VRDN?
Analyst Douglas Tsao (HC WAINWRIGHT) currently has the highest performing score on VRDN with 1/13 (7.69%) price target fulfillment ratio. His price targets carry an average of $11.25 (49.45%) potential upside. Viridian Therapeutics stock price reaches these price targets on average within 40 days.
Larimar Reports Positive Nomlabofusp Data, Expands FA Trials
Larimar Therapeutics has reported early data from its ongoing open-label extension (OLE) study of nomlabofusp. A treatment for Friedreich's ataxia (FA). In this study, 14 participants were administered daily subcutaneous injections of 25 mg of nomlabofusp for up to 260 days. The mean duration of treatment being 99 days.
The treatment was generally well tolerated, with the most common adverse events being mild, brief, and self-limited injection site reactions. Tissue frataxin (FXN) levels increased significantly across different cell types. Buccal cells showing a mean change from baseline of 1.32 pg/μg at Day 90 and skin cells showing a mean change of 9.28 pg/μg. FXN levels in buccal cells increased from 15% to 30% of healthy volunteer levels, and in skin cells, the increase was from 16% to 72%.
Pharmacokinetic data suggest that nomlabofusp reaches a steady state in plasma by Day 30. No further accumulation after prolonged daily dosing. Larimar is now escalating the dose to 50 mg daily for six study participants. Plans to increase the dose for all current participants and initiate new participants on the 50 mg dose.
Looking ahead, Larimar is planning to expand its clinical evaluation into adolescents aged 12 to 17 years. Several hundred participants expected to be involved in the pediatric pharmacokinetic (PK) run-in study. Which is set to begin in early 2025. Furthermore, the company aims to initiate a global confirmatory study in mid-2025, which could involve a much larger patient population. If successful, the overall treatment program, including the OLE study and upcoming studies. Could potentially benefit thousands of patients globally, as Friedreich's ataxia affects an estimated 5,000 to 10,000 individuals worldwide.
Analyst Ratings Reflect Mixed Sentiment Amid Promising Data
- HC Wainwright & Co. analyst Edward White reiterated a Buy rating and a $15 price target.
- Baird analyst Joel Beatty lowered the price target to $13.
Which Analyst has the best track record to show on LRMR?
Analyst Jonathan Wolleben (JMP) currently has the highest performing score on LRMR with 1/10 (10%) price target fulfillment ratio. His price targets carry an average of $17 (212.50%) potential upside. Larimar Therapeutics stock price reaches these price targets on average within 728 days.
Daily stock Analysts Top Price Moves Snapshot

December 18, 2024: Selected stock price target news of the day: December 18th, 2024
By: Matthew Otto
Salesforce Secures Over 1,000 Deals for AI-Powered Agentforce
Salesforce has closed more than 1,000 paid deals for its AI platform. Agentforce, which powers virtual representatives for businesses, CEO Marc Benioff announced on Tuesday. The platform currently supports over 50,000 active users globally. Who leverage its capabilities to build AI bots for tasks such as recruiting, customer service, and operations.
Salesforce unveiled enhancements that integrate these AI capabilities into its messaging app Slack. Internally, Salesforce has used Agentforce to streamline operations, reducing by 50% the number of employees needed to handle simple customer queries. A move that has saved millions in operational costs. Despite this, Benioff confirmed plans to expand Salesforce's sales team by at least 10%, adding an estimated 2,500 new roles globally.
Looking ahead, Salesforce plans to launch a robot force partner program, aiming to connect virtual AI assistants with physical robots. This program targets industries such as hospitality. Where digital assistants could manage back- and front-office tasks while robots perform manual tasks like cleaning.
Analyst Ratings Highlight Optimism Amid AI and Expansion Focus
- Needham analyst Scott Berg reiterated a Buy rating and a price target of $375.
- Goldman Sachs analyst Kash Rangan reaffirmed a Buy rating and a $400 price target.
- Piper Sandler analyst Brent Bracelin maintained an Overweight rating and a $405 price target.
- Mizuho analyst Gregg Moskowitz kept an Outperform rating and a $425 price target.
Which Analyst has the best track record to show on CRM?
Analyst Gil Luria (D.A. DAVIDSON) currently has the highest performing score on CRM with 6/8 (75%) price target fulfillment ratio. His price targets carry an average of $-61.42 (-16.99%) potential downside. Salesforce stock price reaches these price targets on average within 54 days.
Square Partners with Sysco and Introduces Features for 500,000+ Restaurant Operators
Square has partnered with Sysco, a foodservice distributor serving over 700. 000 customers across 90 countries, to promote its technology suite through Sysco’s Restaurant Solutions program. Square’s tools will now be co-marketed and sold to Sysco’s customers, which include restaurants, bars, and other foodservice operators. This partnership is expected to increase the reach of Square’s technology. Which currently supports over 500,000 food and beverage businesses globally.
Square introduced new features to enhance restaurant operations. Bar Tabs allow pre-authorization of credit cards or digital wallets, helping bars manage up to 20 to 30 forgotten tabs per night. Instant Payouts reduce cash flow delays by giving restaurants immediate access to funds from third-party delivery orders, bypassing typical delays of up to 11 days. This feature is available to select Square users integrated with DoorDash and Uber Eats, with additional providers expected in 2025.
House Accounts now allow sellers to invoice repeat customers on flexible schedules, such as monthly or quarterly. These updates will be fully available by early 2025.
Analysts Weigh In Amid New Partnerships and Product Features
- Bernstein SocGen Group analyst Harshita Rawat reiterated an Outperform rating and a $120 price target.
- Morgan Stanley analyst James Faucette maintained an Underweight rating and raised the price target from $60 to $65.
Which Analyst has the best track record to show on SQ?
Analyst Jed Kelly (OPPENHEIMER) currently has the highest performing score on SQ with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $32.69 (21.46%) potential downside. Square stock price reaches these price targets on average within 13 days.
Tenaya Reports Positive Early Data from TN-201 MyPEAK-1 Trial
Tenaya Therapeutics has reported early data from the first cohort of patients in the MyPEAK-1 Phase 1b/2 clinical trial of TN-201. A gene therapy for MYBPC3-associated hypertrophic cardiomyopathy (HCM).
The trial’s first cohort of three patients dosed with 3E13 vg/kg demonstrated that TN-201 was well tolerated. Measurable transgene RNA expression and increased MyBP-C protein levels. Patient 1 showed a 50% increase in TN-201 mRNA expression at Week 52. A 3% increase in MyBP-C protein levels was noted. Additionally, clinical markers of disease such as NYHA classification improved for Patients 1 and 2. Cardiac troponin I normalized in Patient 2.
These results are promising for the 120,000 people in the U.S. affected by MYBPC3-associated HCM, a severe genetic form of heart disease that can lead to heart failure. Stroke, and sudden cardiac arrest.
The safety profile of TN-201 was manageable. Mild elevations in liver enzymes observed in all patients, which resolved with corticosteroid treatment. Importantly, no cardiac toxicities or serious adverse events were linked to TN-201. HCM affects approximately 20% of the broader hypertrophic cardiomyopathy population, equating to an estimated 24,000 patients in the U.S. alone. Tenaya's ongoing trial will expand to include up to 24 patients, with a higher dose cohort anticipated in 2025.
Analyst Ratings Following Positive Trial Data
- Chardan Capital analyst Geulah Livshits maintained a Buy rating and set a $18 price target.
- HC Wainwright & Co. analyst Joseph Pantginis reiterated a Buy rating and a $18 price target.
Daily stock Analysts Top Price Moves Snapshot

December 19, 2024: Selected stock price target news of the day: December 19th, 2024
By: Matthew Otto
Micron Technology Reports Mixed Q1 Results, Issues Weaker than Expected Q2 Guidance
Micron Technology reported first-quarter earnings posting adjusted earnings per share (EPS) of $1.79, beating the analyst estimate of $1.73 by $0.06. Revenue for the quarter totaled $8.71 billion, exceeding the consensus estimate of $8.68 billion.
These results reflect strength in Micron’s high-bandwidth memory (HBM) chips, used in artificial intelligence applications, with HBM revenue more than doubling sequentially. However, consumer markets such as PCs and smartphones remain weak, with global PC shipments declining 1.3% year-over-year in Q3 2024, according to Gartner.
For Q2 2025, Micron expects EPS in the range of $1.33 to $1.53, well below the consensus estimate of $1.97. Micron also forecasted revenue between $7.7 billion and $8.1 billion, compared to the consensus of $8.97 billion, representing a $1 billion shortfall.
Analysts Adjust Ratings Amid Weak Guidance and Consumer Market Struggles
- Baird analyst Tristan Gerra maintained an Outperform rating but lowered the price target to $130 from $150.
- Needham analyst Quinn Bolton kept a Buy rating while reducing the price target to $120 from $140.
- Stifel analyst Brian Chin adjusted the price target to $130 from $135.
- BofA Securities analyst Vivek Arya downgraded to Neutral rating.
- UBS analyst Timothy Arcuri continued with a Buy rating but cut the price target to $125 from $135.
Which Analyst has the best track record to show on MU?
Analyst C J Muse (CANTOR FITZGERALD) currently has the highest performing score on MU with 9/11 (81.82%) price target fulfillment ratio. His price targets carry an average of $49.69 (49.54%) potential upside. Micron Technology stock price reaches these price targets on average within 450 days.
Microsoft and OpenAI Escalate the AI Battle Against Google’s Search Dominance
Microsoft-backed OpenAI has intensified competition in the online search market by expanding access to its ChatGPT Search feature. Previously limited to subscribers, the tool is now available to all users, granting more than 300 million weekly users the opportunity to shift search habits away from Google.
OpenAI’s announcement highlights efforts to integrate up-to-date web information, positioning ChatGPT as a credible alternative to traditional search engines. According to a September survey by Evercore, 8% of over 1,300 U.S. respondents identified ChatGPT as their primary search engine, underscoring its potential to chip away at Google’s market share.
Microsoft’s investment in OpenAI has been instrumental in fueling this competitive push. Analysts note that Alphabet’s response, such as its recent launch of Gemini 2.0 and advanced video-generation tools, is indicative of the high-stakes battle for dominance in the AI and search markets. However, with mobile AI adoption on the rise, Microsoft’s backing of OpenAI and its advancements could further disrupt the search landscape, pressuring Alphabet to innovate rapidly to maintain its position.
Analyst Increases Price Target Amid AI Competition
- UBS analyst Karl Kierstead maintained a Buy rating and raised the price target from $500 to $525.
Which Analyst has the best track record to show on MSFT?
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on MSFT with 25/27 (92.59%) price target fulfillment ratio. His price targets carry an average of $58.65 (14.43%) potential upside. Microsoft stock price reaches these price targets on average within 117 days.
Jabil Reports Q1 2025 Results, Beats Revenue and EPS Estimates, Raises Full-Year Guidance
Jabil exceeded analyst expectations with its first-quarter fiscal year 2025 results, reporting net revenue of $7.0 billion, surpassing the consensus estimate of $6.61 billion. Q1 EPS came in at $2.00, beating the analyst estimate of $1.88 by $0.12. U.S. GAAP operating income was $197 million, with U.S. GAAP diluted EPS of $0.88.
Jabil has revised its full fiscal year 2025 guidance, now forecasting net revenue of $27.3 billion, core operating margins of 5.4%, and core diluted EPS of $8.75, slightly above the consensus estimate of $8.69.
Looking ahead, Jabil provided its second-quarter 2025 guidance, projecting EPS between $1.60 and $2.00, compared to the consensus of $1.80. For Q2, Jabil expects revenue in the range of $6.1 billion to $6.7 billion, exceeding the consensus estimate of $6.28 billion.
Analysts Update Ratings and Price Targets Following Q1 2025 Results
- UBS analyst David Vogt maintained a Neutral rating and raised the price target from $128 to $152.
- Goldman Sachs analyst Mark Delaney kept a Buy rating while increasing the price target from $145 to $160.
Which Analyst has the best track record to show on JBL?
Analyst Matthew Sheerin (STIFEL) currently has the highest performing score on JBL with 14/16 (87.5%) price target fulfillment ratio. His price targets carry an average of $13.53 (9.91%) potential upside. Jabil stock price reaches these price targets on average within 118 days.
Daily stock Analysts Top Price Moves Snapshot
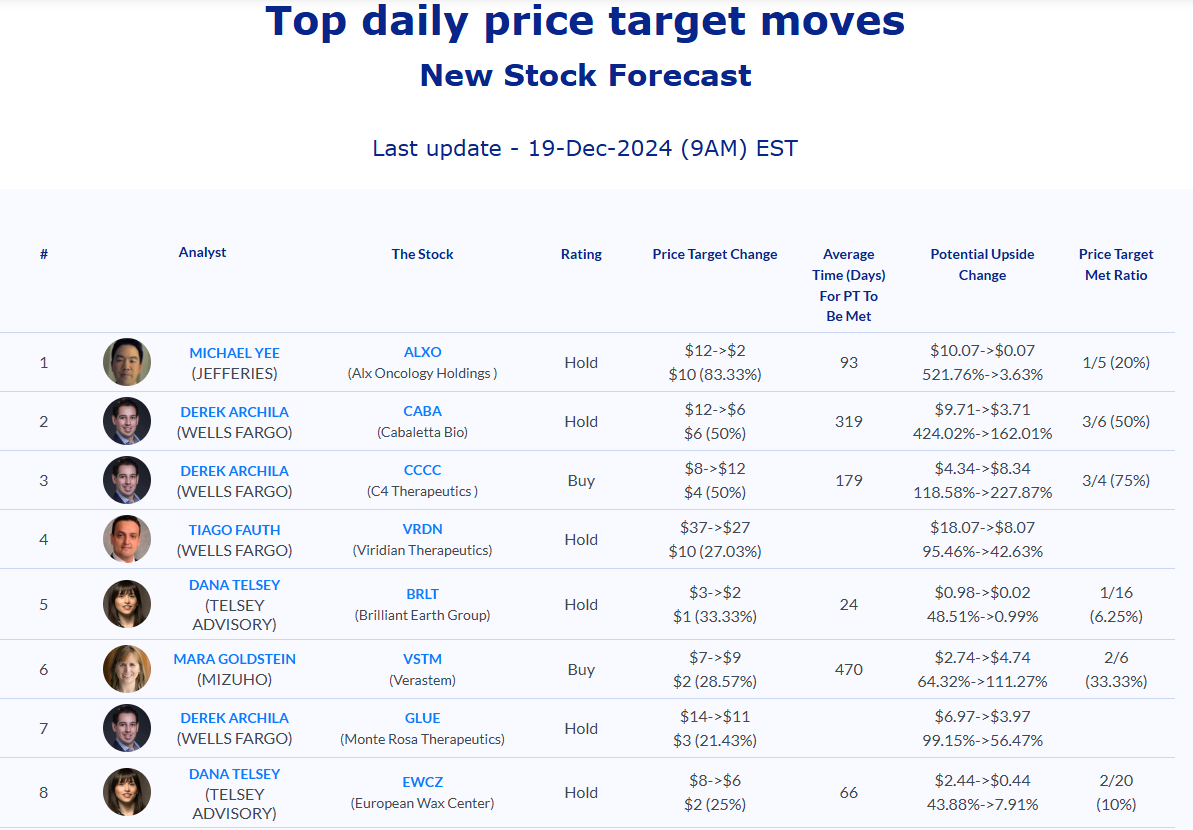
December 20, 2024: Selected stock price target news of the day: December 20th, 2024
By: Matthew Otto
NIKE Reports Second-Quarter Fiscal 2025 Results with Revenue Decline and Strategic Refocus
NIKE announced its fiscal 2025 second-quarter financial results, reporting earnings per share (EPS) of $0.78, surpassing the analyst estimate of $0.65 by $0.13. Revenue for the quarter was $12.4 billion, slightly ahead of the consensus estimate of $12.18 billion but down 8% on a reported basis and 9% on a currency-neutral basis compared to the prior year.
NIKE Direct revenues dropped 13% to $5.0 billion, driven by a 21% decline in NIKE Brand Digital and a 2% decrease in NIKE-owned stores. Wholesale revenues showed more resilience, declining 3% to $6.9 billion. Gross margin narrowed by 100 basis points to 43.6%, impacted by higher discounts and channel mix changes, offset partly by lower product input and logistics costs. Net income fell 26% to $1.2 billion, while diluted EPS decreased 24% year-over-year.
Analyst Ratings Reflect Mixed Sentiment Amid Q2 Results
- Morgan Stanley analyst Alex Straton maintained an Equal-Weight rating but reduced the price target from $80 to $74.
- Deutsche Bank analyst Krisztina Katai reiterated a Buy rating and raised the price target from $82 to $84.
- BofA Securities analyst Lorraine Hutchinson reiterated a Buy rating while lowering the price target from $95 to $90.
- Needham analyst Tom Nikic reaffirmed a Buy rating and the price target at $84.
- Telsey Advisory Group analyst Cristina Fernandez downgraded from Outperform to Market Perform and the price target from $93 to $80.
Which Analyst has the best track record to show on NKE?
Analyst Rick Patel (RAYMOND JAMES) currently has the highest performing score on NKE with 12/16 (75%) price target fulfillment ratio. His price targets carry an average of $7.8 (6.38%) potential upside. NIKE stock price reaches these price targets on average within 126 days.
Phase IIb PADOVA Study Results for Prasinezumab in Parkinson’s Disease
Prothena shared results from the Phase IIb PADOVA study, conducted with Roche, which investigated prasinezumab in 586 participants with early-stage Parkinson’s disease. Of these, 439 (75%) were on levodopa treatment.
In this subgroup, prasinezumab demonstrated a 21% reduction in the risk of confirmed motor progression (HR=0.79 [0.63-0.99], nominal p=0.0431). Across the broader study population, the risk reduction was 16% (HR=0.84 [0.69-1.01], p=0.0657). Covariate-adjusted analyses further improved these outcomes, with the levodopa subgroup showing a 24% risk reduction (HR=0.76 [0.61-0.95], nominal p=0.0175).
Safety data from the study, which involved over 900 Parkinson’s patients across multiple trials, including 500 treated for up to five years, confirmed prasinezumab's tolerability with no new safety signals observed.
Parkinson’s disease affects approximately 10 million people globally, including nearly 1 million in the United States alone, with 60,000 new cases diagnosed annually in the U.S. The PADOVA results suggest that prasinezumab could offer a much-needed disease-modifying option for these individuals. The open-label extension phases of PADOVA and PASADENA studies will provide further insights, with the PASADENA trial already showing a 51% to 65% slower motor progression over four years compared to external controls.
Analysts Adjust Ratings and Targets Following Study
- HC Wainwright & Co. analyst Andrew Fein reiterated a Buy rating but reduced the price target from $84 to $48.
- Chardan Capital analyst Rudy Li initiated coverage with a Buy rating and set a price target of $40.
Which Analyst has the best track record to show on PRTA?
Analyst Jay Olson (OPPENHEIMER) currently has the highest performing score on PRTA with 5/13 (38.46%) price target fulfillment ratio. His price targets carry an average of $42.23 (213.61%) potential downside. Prothena stock price reaches these price targets on average within 96 days.
Darden Restaurants Reports Q2 Results, Driven by Sales Growth and Strategic Expansion
Darden Restaurants announced financial results for the second quarter reporting a 6% increase in total sales to $2.89 billion, exceeding the consensus estimate of $2.86 billion. This growth was driven by a 2.4% rise in same-restaurant sales, outperforming analysts’ expectations of 1.5%, and the addition of 103 Chuy’s restaurants and 39 net new locations.
Olive Garden, which accounts for over 40% of quarterly revenue, saw same-restaurant sales increase by 2.0%, surpassing the forecast of 1.4%. LongHorn Steakhouse continued its performance with a 7.5% increase in same-store sales, exceeding the expected 4.1% rise. The fine dining segment, including The Capital Grille and Ruth’s Chris Steak House, saw a 5.8% decline in same-restaurant sales.
Darden reported adjusted diluted earnings per share of $2.03, matching the analyst estimate, while reported diluted EPS was $1.82, reflecting $0.21 in costs related to the Chuy’s acquisition. Net income for the quarter increased slightly to $215.1 million from $212.1 million a year earlier. Segment profits improved for Olive Garden and LongHorn Steakhouse, with Q2 profits of $277.1 million and $134.2 million, respectively.
Looking ahead, Darden updated its full-year 2025 guidance, projecting EPS of $9.40 to $9.60, slightly below the consensus of $9.42, and revenue of $12.1 billion, surpassing the consensus of $11.94 billion. The company also plans to open 50 to 55 new restaurants and anticipates capital spending of $650 million for the fiscal year.
Analysts Adjust Price Targets Following Q2 Results
- Baird analyst David Tarantino maintained a Neutral rating and raised the price target from $180 to $194.
- Wedbush analyst Nick Setyan reiterated an Outperform rating and increased the price target from $200 to $220.
- Stephens & Co. analyst Jim Salera kept an Equal-Weight rating and lifted the price target from $164 to $175.
Which Analyst has the best track record to show on DRI?
Analyst John Ivankoe (JPMORGAN) currently has the highest performing score on DRI with 17/17 (100%) price target fulfillment ratio. His price targets carry an average of $5.83 (3.43%) potential upside. Darden Restaurants stock price reaches these price targets on average within 252 days.
Daily stock Analysts Top Price Moves Snapshot
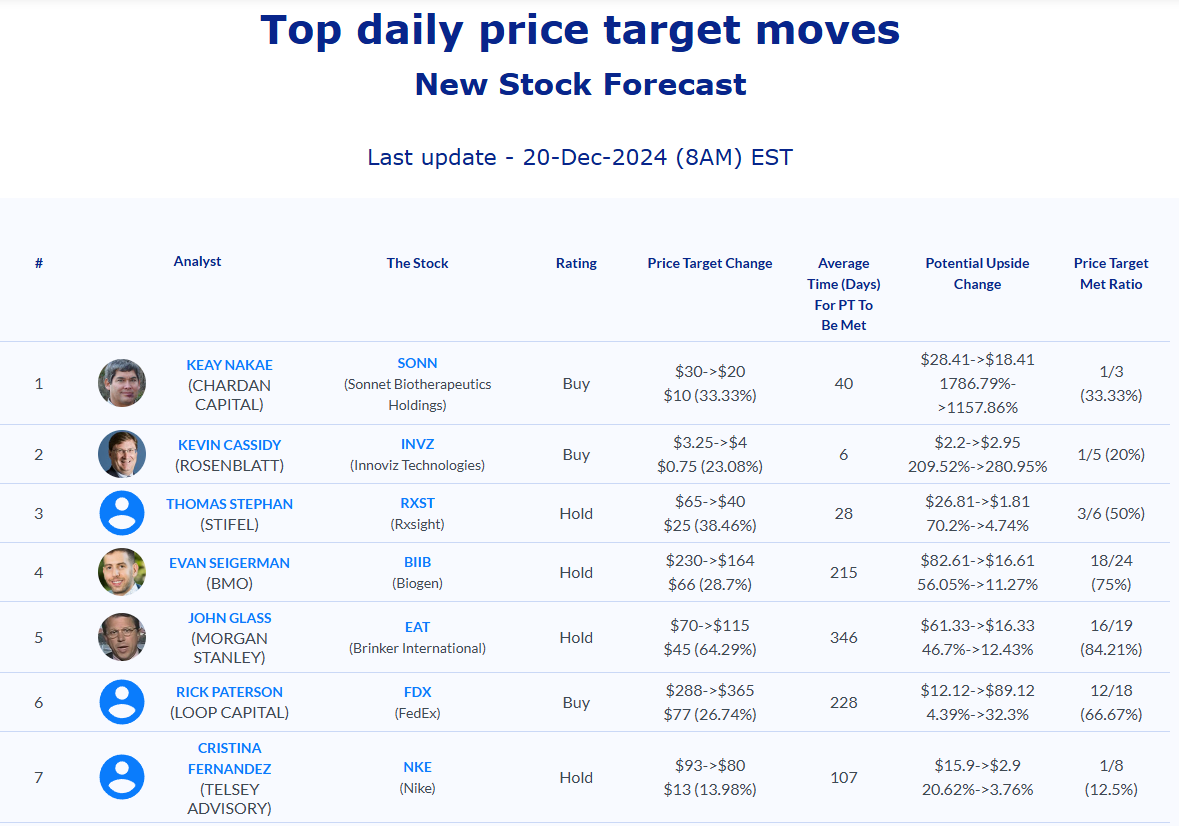
December 23, 2024: Selected stock price target news of the day: December 23rd, 2024
By: Matthew Otto
FedEx Reports Q2 Results, Announces $20 Billion Freight Spin-Off, and Lowers FY2025 Guidance
FedEx released its second-quarter fiscal 2025 results, reporting earnings per share (EPS) of $4.05, aligning with analysts’ estimates. Quarterly revenue came in at $22.0 billion, slightly below the consensus estimate of $22.17 billion. Operating income was $1.05 billion, $1.38 billion on an adjusted basis, while operating margin stood at 4.8% and 6.3% adjusted. Net income for the quarter reached $0.74 billion, $0.99 billion adjusted.
FedEx announced the planned spin-off of its FedEx Freight division, targeting completion within 18 months. This strategic move aims to unlock up to $20 billion in shareholder value by allowing the freight business, which reported an 11% year-over-year revenue decline to $2.17 billion.
Despite this market reaction, FedEx lowered its full-year fiscal 2025 guidance. Adjusted EPS is now projected at $19.00 to $20.00, down from the prior forecast of $20.00 to $21.00. Diluted EPS before MTM retirement plan adjustments is forecasted at $16.45 to $17.45, compared to a previous range of $17.90 to $18.90.
Analyst Ratings Boost Outlook Amid Q2 Results and Spin-Off
- Raymond James analyst Patrick Tyler Brown yesterday maintained an Outperform rating and increased the price target from $305 to $320.
- BofA Securities analyst Ken Hoexter yesterday retained a Buy rating and boosted the price target from $325 to $348.
- Stephens & Co. analyst Daniel Imbro yesterday upheld an Overweight rating though lowered the price target from $350 to $345.
- BMO Capital analyst Fadi Chamoun yesterday held a Market Perform rating yet raised the price target from $300 to $330.
- JP Morgan analyst Brian Ossenbeck yesterday sustained an Overweight rating while raising the price target from $366 to $370.
- Stifel analyst J. Bruce Chan yesterday continued with a Buy rating and lifted the price target from $321 to $368.
- UBS analyst Thomas Wadewitz yesterday kept a Buy rating and raised the price target from $311 to $350.
- Wells Fargo analyst Christian Wetherbee yesterday maintained an Equal-Weight rating but increased the price target from $305 to $320.
Which Analyst has the best track record to show on FDX?
Analyst Ken Hoexter (BAML) currently has the highest performing score on FDX with 26/35 (74.29%) price target fulfillment ratio. His price targets carry an average of $72.12 (26.14%) potential upside. FedEx stock price reaches these price targets on average within 367 days.
Cintas Beats EPS Estimates in Q2 FY2025, Raises Full-Year Guidance
Cintas announced its financial results for the fiscal 2025 second quarter, reporting revenue of $2.56 billion, meeting the consensus estimate. Diluted earnings per share (EPS) of $1.09, exceeding analyst expectations of $1.01 by $0.08, representing a 21.1% year-over-year increase in EPS.
Gross margin improved by 11.8% to $1.28 billion, accounting for 49.8% of revenue compared to 48.0% in the prior year. Operating income rose by 18.4% to $591.4 million, or 23.1% of revenue, up from 21.0% in the second quarter of fiscal 2024.
Net income for the quarter grew 19.7% to $448.5 million, and Cintas raised its full-year guidance, projecting fiscal 2025 EPS of $4.28 to $4.34, exceeding the consensus estimate of $4.24. Revenue guidance was updated to a range of $10.255 billion to $10.320 billion, representing growth of up to 7.5% year-over-year despite fiscal 2025 having two fewer workdays.
Analyst Ratings Reflect Mixed Sentiment After Q2 Results
- Goldman Sachs analyst George Tong yesterday reiterated a Buy rating but revised the price target downward from $236 to $211.
- Truist Securities analyst Jasper Bibb yesterday maintained a Buy rating while lowering the price target from $225 to $215.
- UBS analyst Joshua Chan yesterday kept a Buy rating and adjusted the price target from $240 to $218.
- RBC Capital analyst Ashish Sabadra yesterday reiterated a Sector Perform rating and the $215 price target.
- Wells Fargo analyst Jason Haas yesterday maintained an Underweight rating and reduced the price target further from $191 to $184.
Which Analyst has the best track record to show on CTAS?
Analyst Shlomo Rosenbaum (STIFEL) currently has the highest performing score on CTAS with 11/12 (91.67%) price target fulfillment ratio. His price targets carry an average of $10.25 (5.42%) potential upside. Cintas stock price reaches these price targets on average within 76 days.
Accenture Beats Q1 Estimates, Boosted by AI Demand, Raises 2025 Revenue Outlook
Accenture reported first-quarter results, surpassing Wall Street's expectations with revenue of $17.7 billion and earnings per share of $3.59. These figures beat analysts' consensus estimates of $17.1 billion and $3.42, respectively.
Accenture’s growth was driven by increased demand for its services, particularly in AI adoption, with generative AI contributing significantly to the performance. Accenture's GenAI business saw new bookings of $1.2 billion, and its overall new bookings totaled $18.7 billion, up 1% from the previous year.
Accenture also announced an increase in its AI and data workforce to 69,000, with plans to reach 80,000 by 2026. This demand for AI services is reflected in Accenture’s raised revenue growth forecast for fiscal 2025, now expected to be between 4% and 7%, up from an earlier estimate of 3% to 6%.
Despite these results, Accenture’s outlook for the second quarter shows a slight dip, with projected revenue between $16.2 billion and $16.8 billion, lower than analysts' consensus estimate of $16.63 billion. Also lowered its full-year earnings per share guidance to a range of $12.43 to $12.79, below the anticipated $12.73.
Analysts Lower Price Targets Following Disappointing Guidance
- BMO Capital analyst Keith Bachman yesterday maintained a Market Perform rating while raising the price target from $390 to $425.
- Jefferies analyst Surinder Thind yesterday kept a Hold rating and increased the price target from $355 to $385.
- UBS analyst Kevin McVeigh yesterday maintained a Buy rating and lifted the price target from $450 to $455.
Which Analyst has the best track record to show on ACN?
Analyst Dan Dolev (MIZUHO) currently has the highest performing score on ACN with 2/3 (66.67%) price target fulfillment ratio. His price targets carry an average of $28.82 (8.57%) potential upside. Accenture stock price reaches these price targets on average within 53 days.
Daily stock Analysts Top Price Moves Snapshot

December 24, 2024: Selected stock price target news of the day: December 24th, 2024
By: Matthew Otto
Carnival Reports Record Results for 2024 and Optimistic Outlook for 2025
Carnival reported its financial performance for 2024 with full-year revenue reaching $25 billion, representing over 15% growth compared to the prior year. Net income totaled $1.9 billion, surpassing the guidance by $130 million, while adjusted EBITDA reached a record $6.1 billion—up more than 40% year-over-year.
Fourth-quarter revenue of $5.9 billion marked a 10% increase from 2023, with adjusted EBITDA of $1.2 billion, exceeding prior expectations by $80 million. Carnival also reported cumulative advanced bookings for 2025 at all-time highs in both occupancy and price.
Looking ahead, Carnival projects adjusted net income of approximately $2.3 billion for 2025, reflecting over 20% growth from 2024, with adjusted EBITDA expected to reach $6.6 billion. Despite higher operating costs, including increased advertising and dry-dock expenses, net yields are forecast to rise by 4.2% on a constant currency basis, exceeding record 2024 levels.
Carnival reduced its debt by over $8 billion since January 2023, achieving a net debt to adjusted EBITDA ratio of 4.3x, with interest expenses expected to decline by $200 million year-over-year in 2025. Sustainability milestones included a reduction of greenhouse gas emissions from ship fuel by 11% compared to the 2011 peak and a 44% reduction in food waste per person relative to 2019.
Analysts Raise Price Targets Amid Financial Performance and 2025 Outlook
- Barclays analyst Brandt Montour yesterday reaffirmed an Overweight rating while increasing the price target from $31 to $32.
- Stifel analyst Steven Wieczynski yesterday upheld a Buy rating and lifted the price target from $32 to $34.
Which Analyst has the best track record to show on CCL?
Analyst Matthew Boss (JPMORGAN) currently has the highest performing score on CCL with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $6.81 (37.44%) potential upside. Carnival stock price reaches these price targets on average within 75 days.
FDA Approves ALYFTREK™: Vertex's Next-Generation CF Therapy Targets 31 Additional Mutations
Vertex Pharmaceuticals announced the U.S. FDA approval of ALYFTREK™ (vanzacaftor/tezacaftor/deutivacaftor), a once-daily, next-generation triple combination CFTR modulator for treating cystic fibrosis (CF) in individuals aged six and older with at least one F508del mutation or another responsive mutation.
This approval includes efficacy against 31 mutations previously unresponsive to other CFTR modulators, potentially benefiting 150 additional CF patients in the U.S. ALYFTREK's Phase 3 clinical trials, involving over 1,000 participants across more than 20 countries and 200 sites, demonstrated non-inferiority to TRIKAFTA® in absolute change in ppFEV1 and significant reductions in sweat chloride levels, key markers of CF severity.
With over 92,000 individuals affected by CF globally, ALYFTREK aims to address unmet needs, particularly with its once-daily dosing. Approximately 75% of surveyed physicians identified convenient dosing as a critical need, highlighting ALYFTREK's potential impact. The treatment also introduces a new standard for CFTR function improvement, contributing to Vertex’s portfolio of five approved CFTR modulators, now reaching two-thirds of the 68,000 eligible CF patients in over 60 countries..
Analysts Adjust Price Targets Following ALYFTREK Approval
- Truist Securities analyst Joon Lee yesterday maintained a Buy rating but lowered the price target from $550 to $460.
- Scotiabank analyst Greg Harrison yesterday maintained a Sector Perform rating while raising the price target from $426 to $430.
- JP Morgan analyst Jessica Fye yesterday kept an Overweight rating and adjusted the price target from $503 to $500.
Which Analyst has the best track record to show on VRTX?
Analyst Andrew Fein (HC WAINWRIGHT) currently has the highest performing score on VRTX with 19/22 (86.36%) price target fulfillment ratio. His price targets carry an average of $142.5 (36.31%) potential upside. Vertex Pharmaceuticals stock price reaches these price targets on average within 177 days.
Neurocrine Biosciences Launches CRENESSITY for Classic Congenital Adrenal Hyperplasia (CAH)
Neurocrine Biosciences has announced the U.S. availability of CRENESSITY™ (crinecerfont), a first-in-class treatment for classic congenital adrenal hyperplasia (CAH). This rare genetic condition affects approximately 30,000 individuals in the U.S., with about 95% of cases resulting from 21-hydroxylase (21-OH) enzyme deficiency.
CRENESSITY was recently approved by the U.S. Food and Drug Administration (FDA) and is designed to help patients aged four years and older reduce glucocorticoid doses while maintaining or improving androgen levels. Available as capsules (50 mg and 100 mg) and an oral solution (50 mg/mL), CRENESSITY is expected to provide relief to thousands of patients and improve quality of life by addressing the limitations of traditional high-dose steroid treatments.
The FDA approval was supported by data from the CAHtalyst™ Phase 3 studies, which included 285 participants—103 pediatric patients aged 4 to 17 and 182 adults aged 18 to 58. These trials demonstrated benefits, such as improved androgen control within four weeks and glucocorticoid dose reductions over 20 to 24 weeks.
Analysts Maintain Positive Outlook After CRENESSITY Launch
- Piper Sandler analyst David Amsellem yesterday reiterated his Overweight rating and a $160 price target.
- Barclays analyst Carter Gould yesterday maintained his Overweight rating, but raised the price target from $160 to $165.
Which Analyst has the best track record to show on NBIX?
Analyst Brian Abrahams (RBC) currently has the highest performing score on NBIX with 18/18 (100%) price target fulfillment ratio. His price targets carry an average of $21.34 (19.11%) potential upside. Neurocrine Biosciences stock price reaches these price targets on average within 127 days.
Daily stock Analysts Top Price Moves Snapshot
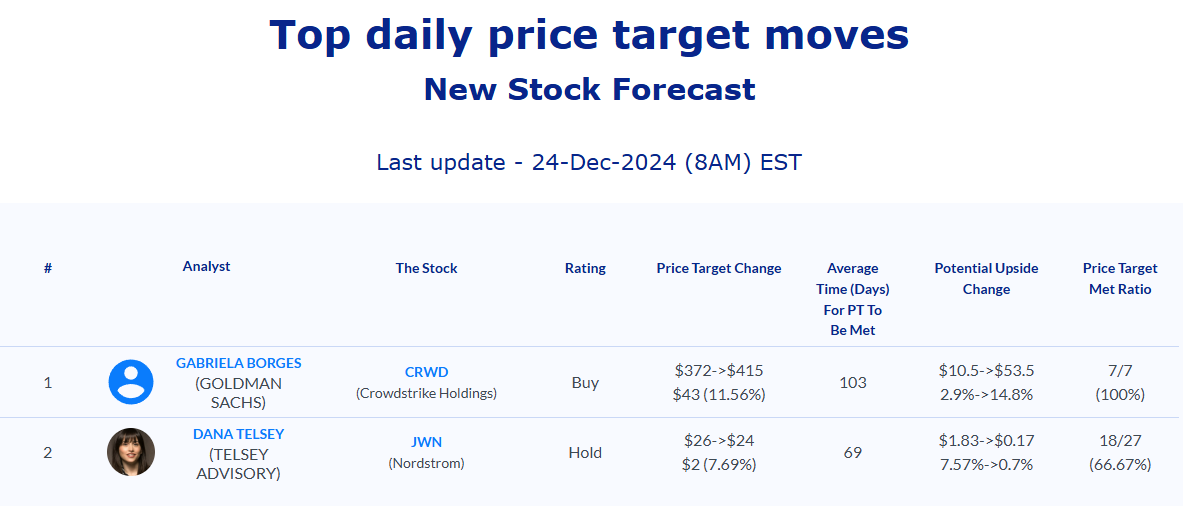
December 26, 2024: Selected stock price target news of the day: December 26th, 2024
By: Matthew Otto
Anavex Advances Alzheimer's Treatment with EMA Application Amid Financial Highlights
Anavex Life Sciences reported its financial and operational results for the fourth quarter and fiscal year ending September 30, 2024. Advancements in its Alzheimer's disease program was highlighted, particularly the European Medicines Agency's acceptance of the Marketing Authorization Application (MAA) for blarcamesine (ANAVEX®2-73).
Alzheimer's disease affects an estimated 7 million people in Europe. This number projected to double to 14 million by 2030, according to the European Brain Council. Anavex plans to present additional long-term Phase IIb/III trial data at the J.P. Morgan 2025 Healthcare Conference in January.
Financially, Anavex ended the fiscal year with $132.2 million in cash and equivalents, down from $151.0 million the prior year. For the fourth quarter, Anavex reported a net loss of $11.6 million, or $0.14 per share, compared to $10.1 million, or $0.12 per share, in the same period of 2023.
Operating expenses for the quarter increased to $14.3 million, primarily due to research and development costs rising to $11.6 million. Annually, Anavex reported $52.9 million in operating expenses, a reduction from $55.8 million in fiscal 2023.
Beyond Alzheimer's, preliminary data from the ongoing ANAVEX®3-71 schizophrenia study showed dose-dependent effects on EEG biomarkers, targeting a condition that affects more than 24 million people worldwide.
Analyst Raises Price Target Amid Alzheimer’s Treatment Progress
- HC Wainwright & Co. analyst Raghuram Selvaraju maintained a Buy rating and raised the price target from $40 to $42.
Which Analyst has the best track record to show on AVXL?
Analyst Raghuram Selvaraju (HC WAINWRIGHT) currently has the highest performing score on AVXL with 4/14 (28.57%) price target fulfillment ratio. His price targets carry an average of $30.87 (338.12%) potential upside. Anavex Life Sciences stock price reaches these price targets on average within 155 days.
Investigation Into Celsius Holdings, Inc. Securities Litigation
Faruqi & Faruqi, LLP and The Gross Law Firm have launched investigations into Celsius Holdings for alleged securities violations during the class period from February 29, 2024, to September 4, 2024.
The lawsuits allege Celsius issued misleading statements that artificially inflated its stock price, ultimately causing financial losses to shareholders. Over 21.6 million shares were sold by insiders during the class period, generating more than $1.4 billion in proceeds, while the market price of Celsius common stock fell sharply as the alleged facts were revealed. Investors with losses exceeding $75,000 are encouraged to contact legal counsel, with the deadline for seeking lead plaintiff status set for January 21, 2025.
Background details indicate that Celsius Holdings grew in recent years, attracting substantial investor interest in its energy drink products and business model. During the class period, it is estimated that thousands of individual and institutional investors purchased shares at inflated prices. Analysts project total shareholder losses could exceed hundreds of millions of dollars as the stock price adjustment reflects the alleged misrepresentations.
Legal proceedings are expected to incur millions in litigation costs, including expert testimony, discovery, and legal representation fees. Shareholders who join the class action will gain access to monitoring services to track the case’s developments without initial financial obligations.
Analyst Maintains Rating and Target Amid Ongoing Securities Litigation
- Morgan Stanley analyst Eric Serotta maintained an Equal-Weight rating and a $42 price target.
Which Analyst has the best track record to show on CELH?
Analyst Gerald Pascarelli (NEEDHAM) currently has the highest performing score on CELH with 5/16 (31.25%) price target fulfillment ratio. His price targets carry an average of $9.23 (32.08%) potential upside. Celsius Holdings stock price reaches these price targets on average within 113 days.
PolyPid Advances SHIELD II Trial for D-PLEX100, Targeting Millions at Risk of Surgical Infections
PolyPid has reported progress in its SHIELD II Phase 3 trial evaluating D-PLEX100 for the prevention of surgical site infections (SSIs) in patients undergoing abdominal colorectal surgeries with large incisions. SSIs are a serious healthcare concern, affecting approximately 300,000 patients annually in the United States, with abdominal surgeries accounting for a significant proportion.
To date, the SHIELD II trial has enrolled 630 of the planned 800 patients. Remaining 170 patients expected to enroll by Q1 2025. Upon anticipated top-line results in Q2 2025, D-PLEX100 could proceed to NDA submission under its Fast Track and Breakthrough Therapy designations, aiming for regulatory approval to benefit this substantial patient population.
Globally, over 1.3 million abdominal colorectal surgeries are performed annually. Beyond the trial, PolyPid secured $14.5 million in private placement financing, extending its operational runway into Q3 2025. If the $27.0 million in associated warrants are exercised, PolyPid's cash reserves could support activities well beyond potential NDA approval.
Analyst Maintains Rating and Lowers Price Target Amid SHIELD II Trial Progress
- HC Wainwright & Co. analyst Raghuram Selvaraju maintained a Buy rating and lowered the price target from $14 to $11.
Daily stock Analysts Top Price Moves Snapshot

December 27, 2024: Selected stock price target news of the day: December 27th, 2024
By: Matthew Otto
Wedbush Projects Apple’s AI-Fueled Growth Amidst Market Cap Milestone
Apple is poised to enter a transformative phase driven by artificial intelligence, according to Wedbush analyst, Dan Ives.
Analyst Dan Ives emphasized Apple’s potential multiyear growth fueled by AI advancements, particularly with the recent release of iOS 18.2, featuring AI-driven capabilities like emoji generation and ChatGPT integration with Siri. These developments are expected to usher in a lucrative iPhone upgrade cycle, with an estimated 300 million iPhones worldwide eligible for upgrades.
For fiscal 2025, Ives forecasts Apple could sell more than 240 million units. Apple’s services segment alone is valued at $2 trillion, and Ives predicts this will play a crucial role in Apple’s trajectory toward a $4 trillion market cap.
Despite these optimistic projections, not all analysts share the same enthusiasm. FactSet’s average price target for Apple stands at $248.14, significantly below Wedbush’s estimate. BTIG strategist Johnathan Krinsky raised concerns about the stock’s recent momentum, noting Apple’s 35% year-to-date increase and a streak of five consecutive weeks with gains exceeding 2%. Historically, such patterns have led to negative one-month forward returns. Krinsky advises caution as Apple approaches the new year, citing potential challenges for January.
Analyst Raises Price Target, Predicts AI-Driven Growth Surge
- Wedbush analyst Daniel Ives yesterday kept an Outperform rating and raised the price target from $300 to $325.
Which Analyst has the best track record to show on AAPL?
Analyst Krish Sankar (TD COWEN) currently has the highest performing score on AAPL with 31/31 (100%) price target fulfillment ratio. His price targets carry an average of $31.76 (14.55%) potential upside. Apple stock price reaches these price targets on average within 181 days.
Assembly Bio Reports Promising Interim Results for ABI-4334 in Chronic HBV
Assembly Biosciences has announced interim results from its Phase 1b study of ABI-4334, a next-generation capsid assembly modulator (CAM) targeting chronic hepatitis B virus (HBV) infection.
Globally, an estimated 296 million people live with chronic HBV, with over 820,000 annual deaths attributed to HBV-related complications, such as cirrhosis and liver cancer. This Phase 1b study enrolled two cohorts of 10 participants each, randomized 8:2 to receive either ABI-4334 or placebo for 28 days.
In the first cohort, a 150 mg dose of ABI-4334 led to a mean reduction of 2.9 log10 IU/mL in HBV DNA. Among participants with detectable HBV RNA at baseline, a mean decline of 2.5 log10 U/mL in HBV RNA was observed. ABI-4334 was well-tolerated, with no serious adverse events or discontinuations. Two grade 3 laboratory abnormalities, an ALT and bilirubin elevation, resolved without impacting treatment.
With the ongoing 400 mg cohort, Assembly Bio anticipates results in the first half of 2025, potentially paving the way for broader clinical trials. If successful, ABI-4334 could benefit millions of HBV patients, particularly the 30 million newly infected each year. Current antiviral therapies often suppress HBV replication but rarely eliminate the virus, leaving a significant unmet need for innovative treatments like ABI-4334.
Analyst Maintains Neutral Rating Amid Promising ABI-4334 Results
- HC Wainwright & Co. analyst Ed Arce reiterated a Neutral rating.
Which Analyst has the best track record to show on ASMB?
Analyst Ed Arce (HC WAINWRIGHT) currently has the highest performing score on ASMB with 3/4 (75%) price target fulfillment ratio. His price targets carry an average of $5.52 (44.23%) potential upside. Assembly Biosciences stock price reaches these price targets on average within 188 days.
Viracta Therapeutics Explores Strategic Alternatives Amid NAVAL-1 Trial Closure
Viracta Therapeutics has decided to close its pivotal Phase 2 NAVAL-1 clinical trial, which evaluated Nana-val for the treatment of relapsed/refractory Epstein-Barr virus-positive (EBV+) lymphomas.
Despite the closure, Viracta emphasized that no new safety concerns prompted the action. EBV+ lymphomas impact an estimated 200,000 new patients annually worldwide, many of whom have limited treatment options.
Viracta is currently evaluating strategic pathways, including potential mergers, licensing agreements, or sales, with no assurance of a definitive outcome. The NAVAL-1 trial was designed to assess Nana-val’s efficacy in treating relapsed/refractory EBV+ lymphomas, an area of significant unmet medical need.
President and CEO Mark Rothera expressed gratitude to trial participants and collaborators, underscoring Nana-val’s promise in transforming EBV+ lymphoma treatment. Approximately 1.5% of global cancers are virus-associated, impacting millions of individuals annually.
Analyst Slashes Price Target Amid Strategic Review
- Rodman & Renshaw analyst Tony Butler downgraded from Buy to Neutral and the price target from $3.5 to $0.25.
Which Analyst has the best track record to show on VIRX?
Analyst Hartaj Singh (OPPENHEIMER) currently has the highest performing score on VIRX with 1/2 (50%) price target fulfillment ratio. His price targets carry an average of $20.3 (129.30%) potential upside. Viracta Therapeutics stock price reaches these price targets on average within 544 days.
Daily stock Analysts Top Price Moves Snapshot

December 30, 2024: Selected stock price target news of the day: December 30th, 2024
By: Matthew Otto
Axsome Announces Completion of Phase 3 Trials for AXS-05 in Alzheimer's Disease Agitation
Axsome Therapeutics has announced the completion of its Phase 3 clinical program for AXS-05, an investigational treatment for Alzheimer's disease agitation, a condition affecting up to 70% of the 7 million Americans diagnosed with Alzheimer's disease.
The ACCORD-2 Phase 3 trial achieved its primary endpoint. Showing AXS-05 delaying agitation relapse by a significant 3.6-fold compared to placebo (hazard ratio: 0.276, p=0.001). The trial also met secondary endpoints. Reporting only 8.4% of patients on AXS-05 relapsing compared to 28.6% on placebo (p=0.001). Additionally, the drug reduced the worsening of overall Alzheimer's disease severity. Reporting 13.3% of patients showing deterioration versus 39.3% on placebo (p<0.001).
AXS-05 demonstrated a favorable safety profile across all trials. Among 456 participants in the long-term safety study, adverse events occurred in 39.9% of patients, with no deaths reported. Notably, the rate of serious adverse events was only 2.6%, none attributed to the study drug.
Analyst Reiterates Rating and Target, Highlighting Positive Results for AXS-05
- Needham analyst Ami Fadia kept with a Buy rating and a $130 price target.
Which Analyst has the best track record to show on AXSM?
Analyst Charles Duncan (CANTOR FITZGERALD) currently has the highest performing score on AXSM with 7/21 (33.33%) price target fulfillment ratio. His price targets carry an average of $26.34 (27.83%) potential upside. Axsome Therapeutics stock price reaches these price targets on average within 49 days.
Citius Reports Transformative Year with FDA Approval and Significant Clinical Advances
Citius Pharmaceuticals announced its financial and operational results for fiscal year 2024, ending September 30. Reported the FDA approval of LYMPHIR™ (denileukin diftitox-cxdl) for adults with relapsed or refractory cutaneous T-cell lymphoma (CTCL), a condition affecting approximately 16,000 individuals in the United States annually.
Citius also progressed with the Phase 3 trial for Mino-Lok®, targeting catheter-related bloodstream infections that affect over 500,000 patients annually in the U.S. LYMPHIR's approval. It is expected to open opportunities for broader application, with investigator-led trials exploring its potential as a combination therapy in immuno-oncology. In total, over 1,000 patients are expected to benefit from ongoing clinical studies across these programs.
Financially, Citius reported a net loss of $39.4 million, or $5.97 per share, for 2024, compared to $32.5 million, or $5.57 per share, in 2023. R&D expenses decreased to $11.9 million from $14.8 million in the prior year, attributed to the completion of the Halo-Lido trial and regulatory activities for LYMPHIR. However, general and administrative expenses rose to $18.2 million due to pre-launch activities. Citius closed the year with $3.3 million in cash and cash equivalents and raised $13.8 million through equity issuance.
Analyst Upgrades Rating, Reflecting Confidence in LYMPHIR’s Market Potential
- D. Boral Capital analyst Jason Kolbert upgraded Citius Pharma from Hold to Buy and announced a $9 price target.
Which Analyst has the best track record to show on CTXR?
Analyst Vernon Bernardino (HC WAINWRIGHT) currently has the highest performing score on CTXR with 5/6 (83.33%) price target fulfillment ratio. His price targets carry an average of $3.5 (700.00%) potential upside. Citius Pharmaceuticals stock price reaches these price targets on average within 339 days.
Halozyme's HYQVIA® Approved in Japan for Agammaglobulinemia and Hypogammaglobulinemia
Halozyme Therapeutics announced that Takeda has received regulatory approval for HYQVIA® from Japan’s Ministry of Health, Labour and Welfare (MHLW). The approval is for treating agammaglobulinemia and hypogammaglobulinemia, which are rare disorders caused by primary or secondary immunodeficiency (PID/SID). It is estimated that agammaglobulinemia affects around 1 in 200,000 individuals. Additionally, hypogammaglobulinemia is more common, affecting about 1 in 10,000 people worldwide.
HYQVIA® combines Immunoglobulin 10% with Halozyme’s ENHANZE® technology, which uses Recombinant Human Hyaluronidase PH20 (rHuPH20) to improve the dispersion and absorption of immunoglobulin, allowing larger volumes to be infused subcutaneously. This enables a reduced dosing frequency of every 3 to 4 weeks, compared to the typical weekly or bi-weekly schedules for other subcutaneous treatments.
The approval is based on two Phase 3 studies in Japan (NCT05150340, NCT05513586) involving 16 patients aged 2 years or older. These studies demonstrated that the Geo Mean of IgG trough levels at the final visits was 9.494g/L, which is comparable to treatments with intravenous or other subcutaneous immunoglobulin products (9.624g/L).
This data supports the potential benefit for a significant portion of the estimated 1,000 to 2,000 people with PID in Japan. Adverse reactions occurred in 31.3% of patients, with the most common being pyrexia and infusion site reactions (12.5%).
Analyst Reiterates Rating, Highlights HYQVIA® Approval
- HC Wainwright & Co. analyst Mitchell Kapoor maintained a Buy rating and a $68 price target.
Which Analyst has the best track record to show on HALO?
Analyst Joseph Catanzaro (PIPER SANDLER) currently has the highest performing score on HALO with 14/14 (100%) price target fulfillment ratio. His price targets carry an average of $-6.47 (-11.07%) potential downside. Halozyme Therapeutics stock price reaches these price targets on average within 140 days.
Daily stock Analysts Top Price Moves Snapshot

December 31, 2024: Selected stock price target news of the day: December 31st, 2024
By: Matthew Otto
Chimerix Submits NDA for Dordaviprone, Requests Priority Review
Chimerix announced the submission of a New Drug Application (NDA) to the U.S. Food and Drug Administration (FDA) for dordaviprone, targeting accelerated approval for treating recurrent H3 K27M-mutant diffuse glioma. This filing requests Priority Review, potentially setting a Prescription Drug User Fee Act (PDUFA) action date in Q3 2025.
Dordaviprone has been granted Rare Pediatric Disease Designation, and Chimerix has applied for a Rare Pediatric Disease Priority Review Voucher (PRV) as part of this submission. If approved, dordaviprone would be the first FDA-approved treatment for this rare glioma subtype. Which affects approximately 400–500 patients annually in the United States. Of these, an estimated 200–300 patients with recurrent disease could benefit directly from the drug.
To support a potential commercial launch in 2025, Chimerix has secured a $30 million credit facility with Silicon Valley Bank (SVB). This agreement includes access to $20 million through February 28, 2026, and an additional $10 million through February 28, 2027, contingent on approval.
Analyst Reaffirms Rating, Aligning with Optimism for Dordaviprone Approval
- HC Wainwright & Co. analyst Edward White yesterday reiterated with a Buy and a $11 price target.
Which Analyst has the best track record to show on CMRX?
Analyst Edward White (HC WAINWRIGHT) currently has the highest performing score on CMRX with 2/10 (20%) price target fulfillment ratio. His price targets carry an average of $8.02 (269.13%) potential upside. Chimerix stock price reaches these price targets on average within 918 days.
Sangamo Regains Rights to Giroctocogene Fitelparvovec, Exploring Commercialization
Sangamo Therapeutics announced it will regain development and commercialization rights to giroctocogene fitelparvovec, an investigational gene therapy for moderately severe to severe hemophilia A, after Pfizer decided to terminate their global collaboration agreement.
Pfizer's decision follows the positive results from the Phase 3 AFFINE trial, which involved 75 adult male participants with hemophilia A. The trial showed a significant reduction in the annualized bleeding rate (ABR) after treatment with giroctocogene fitelparvovec. This dropped from 4.73 (pre-treatment) to 1.24 (post-treatment), a 74% reduction (p-value = 0.0040). Hemophilia A affects about 25 in every 100,000 male births. 55-75% of these individuals experiencing moderate to severe disease.
The collaboration agreement will officially end on April 21, 2025, and Pfizer will transition the giroctocogene fitelparvovec program back to Sangamo. Sangamo also emphasized its ongoing focus on its Fabry gene therapy program, with plans for a Biologics License Application (BLA) submission in the second half of 2025.
Additionally, Sangamo’s clinical pipeline includes a Phase 1/2 trial for ST-503 targeting idiopathic small fiber neuropathy, with enrollment expected to begin in mid-2025. Giroctocogene fitelparvovec has the potential to benefit thousands of patients, as approximately 55,000 individuals are affected by hemophilia A worldwide.
Analyst Lowers Price Target Amid Collaboration Termination
- Wells Fargo analyst Jim Birchenough maintained an Equal-Weight rating and lowered the price target from $3 to $2.
Which Analyst has the best track record to show on SGMO?
Analyst Gena Wang (BARCLAYS) currently has the highest performing score on SGMO with 3/5 (60%) price target fulfillment ratio. Her price targets carry an average of $6.85 (318.60%) potential upside. Sangamo Therapeutics stock price reaches these price targets on average within 282 days.
Ondas Holdings Secures $30M in Funding to Accelerate Growth in Autonomous Drone Platforms
Ondas Holdings has announced the successful closing of a $18.9 million financing through the issuance of 3% senior convertible notes due 2026. This marks the third such investment by a single long-term investor since December 3, 2024. Additionally bringing the total net proceeds to $30 million over the past four weeks.
These proceeds will be allocated primarily to support Ondas Autonomous Systems (OAS) which reported $14.4 million in orders during Q3 2024. The funding achieves the targets set at OAS Investor Day in September 2024. This enabling it to capitalize on the growing demand for its Optimus System and Iron Drone platforms.
The Optimus System, the first FAA-certified small UAS for aerial security and data capture, and the Iron Drone Raider, a counter-drone solution, are central to meeting increasing global demand. Both platforms are highly automated and AI-driven, offering advanced capabilities for defense, industrial, and infrastructure applications.
Analyst Boosts Price Target to $4 Amid Funding and Growth Prospects
- Northland Capital Markets analyst Michael Latimore yesterday kept an Outperform rating and raised the price target from $1.5 to $4.
Which Analyst has the best track record to show on ONDS?
Analyst Michael Latimore (NORTHLAND CAPITAL MARKETS) currently has the highest performing score on ONDS with 2/5 (40%) price target fulfillment ratio. His price targets carry an average of $0.79 (111.27%) potential upside. Ondas Holdings stock price reaches these price targets on average within 310 days.
Daily stock Analysts Top Price Moves Snapshot