The analyst price target moves we wrote up each trading day in June 2023, 21 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
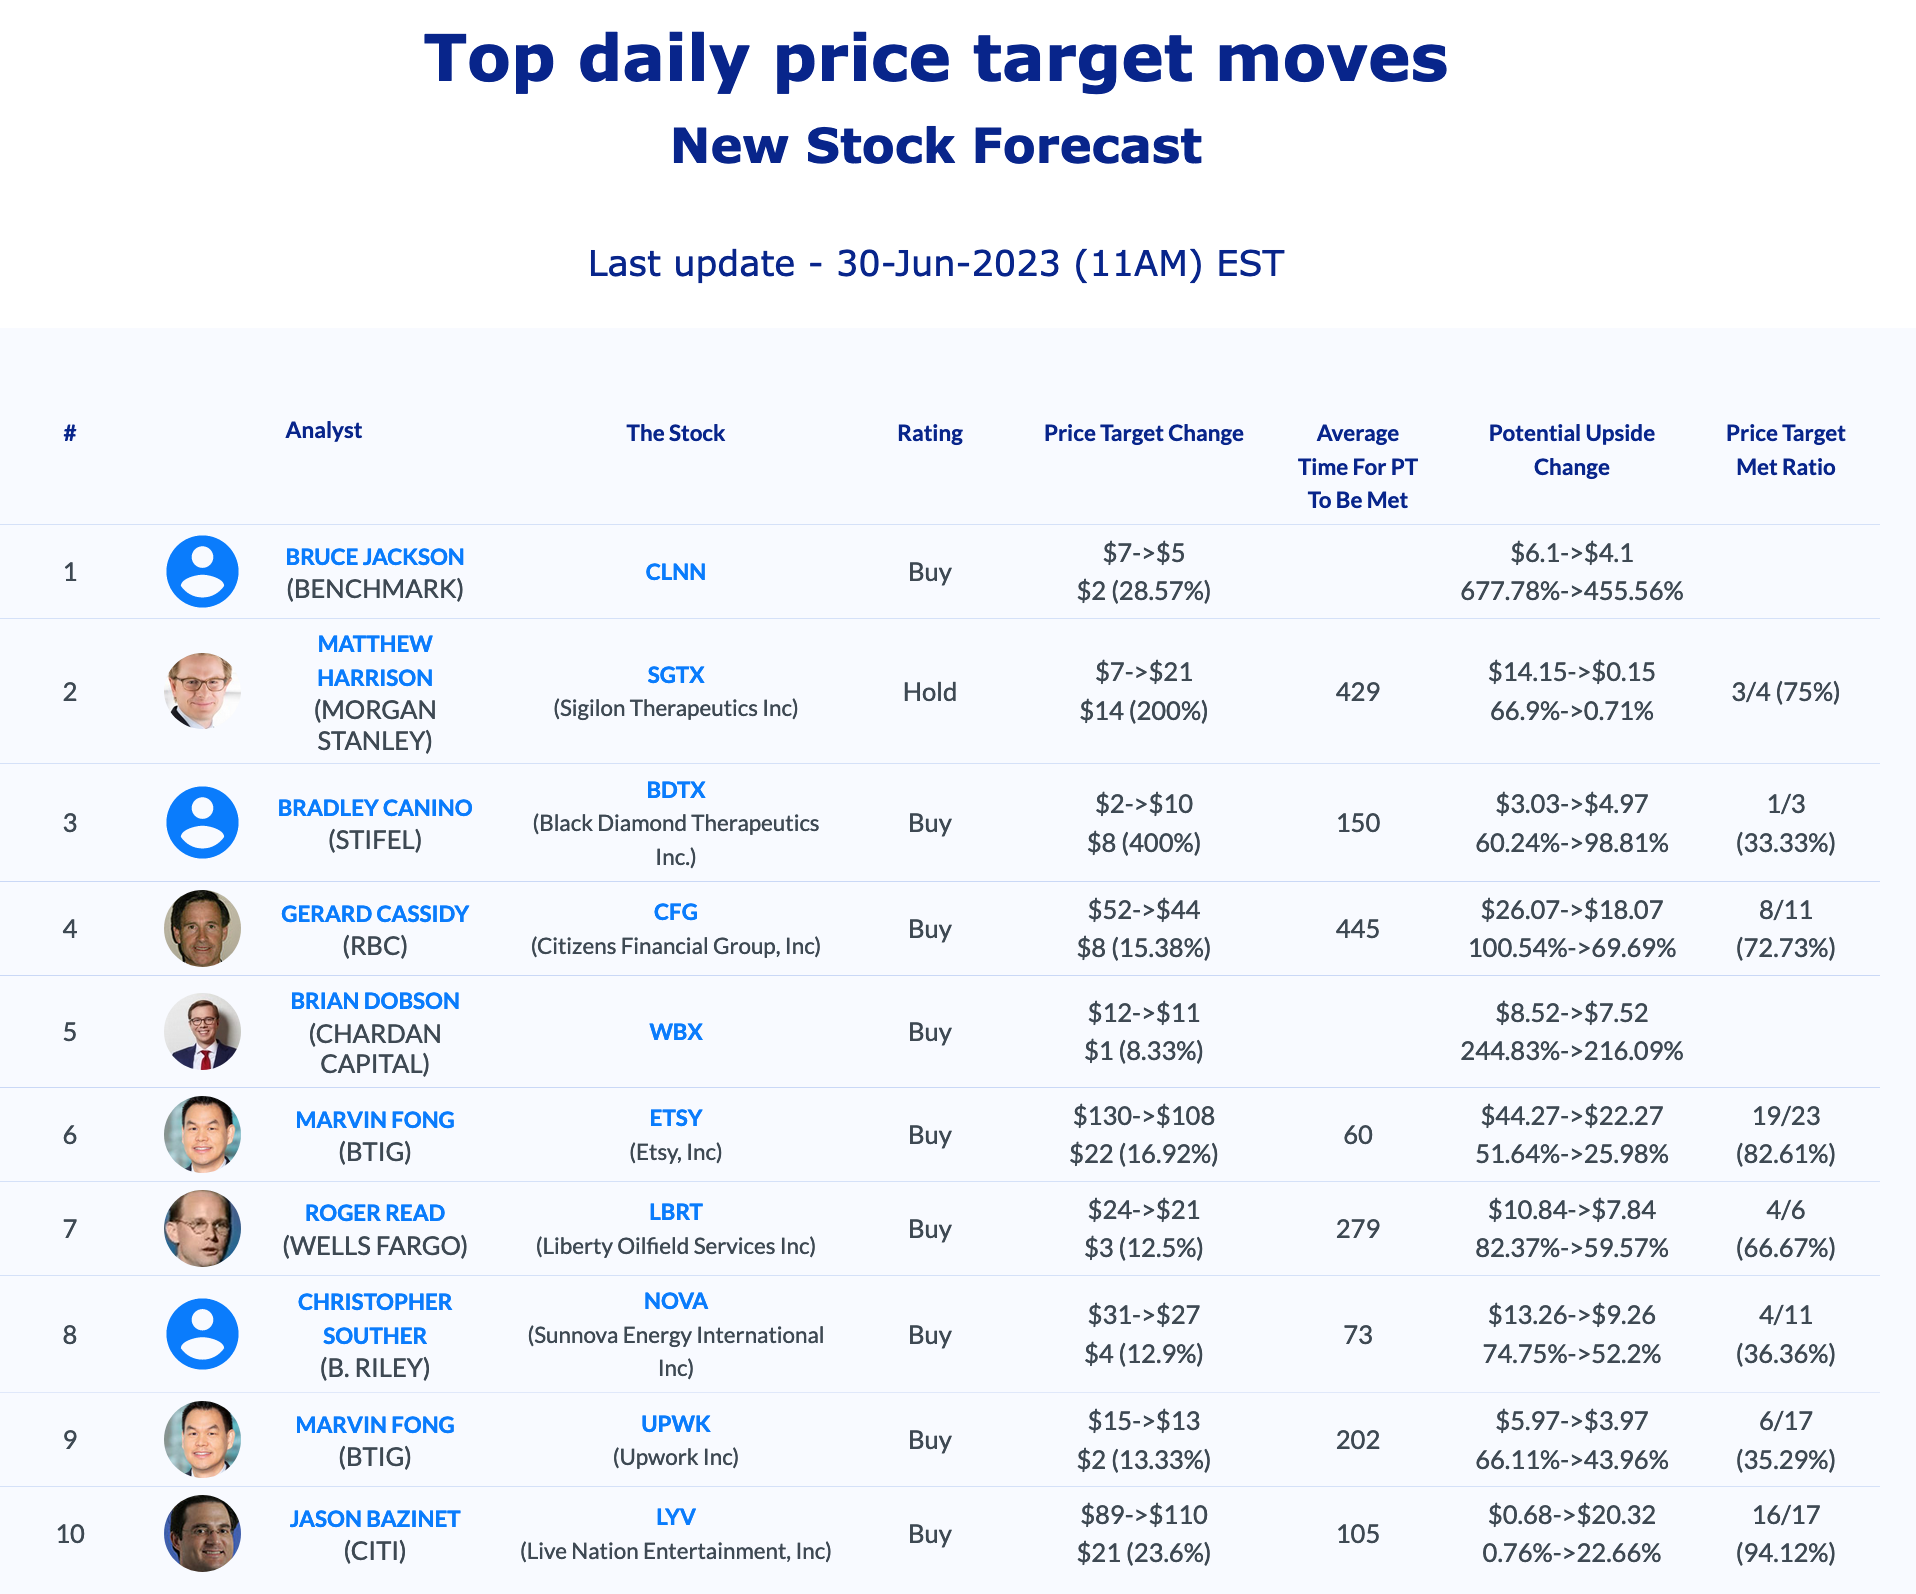
June 1, 2023: Selected stock price target news of the day: June 01, 2023
By Matthew Otto
Salesforce Beats Analysts' Expectations; Faces Increased Challenges
Salesforce has reported an 11% rise in its Q1 FY24 revenue, which marks its slowest pace of growth in 13 years due to an uncertain economy that led companies to reduce spending on cloud-based software. Despite the positive earnings report, Salesforce's shares fell nearly 5% after-hours, following a significant surge in the company's stock this year.
Amy Weaver, Salesforce's CFO, mentioned the company faced ongoing macroeconomic pressures in the U.S., with demand from financial services and technology companies slowing in the quarter.
Salesforce's capital expenditure saw a 36% increase to $243 million due to investments in AI-related tools to power its software products. Despite the challenges, Salesforce's revenue of $8.25 billion for the quarter ended April 30 beat analysts' expectations of $8.18 billion.
Salesforce is facing stiff competition in the crowded cloud-computing market from well-financed traditional vendors such as Oracle (ORCL.N). The company has also been a target of activist investors like ValueAct, Inclusive Capital, and Starboard Value, which have all separately advocated for better cost control initiatives and improved efficiencies.
Salesforce has forecasted a revenue range of $8.51 billion to $8.53 billion for the current quarter, representing approximately a 10% growth from last year. Analysts were expecting revenue of $8.49 billion. On an adjusted basis, Salesforce earned $1.69 per share, surpassing the estimate of $1.61 per share.
Wall Street Raises Price Target on Sales Force
- JMP Securities analyst Patrick Walravens has maintained a Market Outperform rating and raised the price target from $250 to $275, a new street high.
- Citigroup analyst Tyler Radke has kept a Neutral rating and increased the price target from $229 to $230.
- Oppenheimer analyst Brian Schwartz has maintained an Outperform rating and raised the price target from $225 to $235.
- Bernstein analyst Mark Moerdler has maintained an Underperform rating but increased the price target from $145 to $153.
- Baird analyst Rob Oliver has kept a Neutral rating and raised the price target from $200 to $210.
- Mizuho analyst Gregg Moskowitz has maintained a Buy rating and increased the price target from $225 to $240.
- Piper Sandler analyst Brent Bracelin has maintained an Overweight rating and raised the price target from $230 to $248.
- Raymond James analyst Brian Peterson has raised the price target for Salesforce to $260.
The stock had regained half of its losses made in the last two years with not all analysts are full on board, although all have been adjusting up consistently since March this year. For example Derrick Wood from TD Cowen although having a Buy rating set his price target at $200 which is below the Salesforce stock price.
Advance Auto Parts Sees Q1 Shortfall; Misses Expectations, Slashes Full-Year Guidance
Advance Auto Parts' first-quarter earnings for 2023 were significantly below Wall Street expectations, The company reported an EPS of 72 cents, lower than the expected $2.57 per share, according to average analyst estimates compiled by Refinitiv. This difference of $1.85 per share indicates a significant gap between expectations and actual results.
Also, quarterly revenue was $3.42 billion, slightly missing expectations of $3.43 billion.
Furthermore, Advance Auto Parts had to revise their full-year guidance downwards, which also indicates that the company's performance did not meet initial expectations. The revised EPS guidance for the full year 2023 now stands at between $6 and $6.50, down from a previously stated range of $10.20 to $11.20
Net sales increased by a small margin, just 1.3%, primarily driven by new store openings. However, comparable store sales saw a decline of 0.4%. Operating income was also below expectations at $90 million, amounting to an operating income margin of 2.6%, well below expectations.
On the financial front, gross profit decreased by 2.4% to $1.5 billion, primarily due to inflationary product costs that were not fully absorbed by pricing actions. The company's effective tax rate increased, and its diluted EPS was at $0.72, a stark contrast to $2.26 in the first quarter of 2022.
Analysts Adjust Price Targets
- Truist Securities' Scot Ciccarelli maintains Hold, lowers price target to $67
- Barclays' Seth Sigman maintains Equal-Weight, lowers price target to $69
- Citigroup's Steven Zaccone maintains Neutral, lowers price target to $76
- Morgan Stanley's Simeon Gutman maintains Equal-Weight, lowers price target to $80
- Goldman Sachs' Kate McShane downgrades Advance Auto Parts to Neutral, lowers price target to $82
- JP Morgan's Christopher Horvers downgrades to Neutral, lowers price target to $84
- Raymond James' Bobby Griffin downgrades Advance Auto Parts from Strong Buy to Market Perform.
The last two years have not been kind to the retail stock while it lost 60%, however today's adjustment marks that Wall Street doesn’t forecast a rebound in the near time horizon.
Okta Beats Q1 2024 Expectations: Revenue Up 25%; Forecasts Optimistic Despite Macroeconomic Concerns
Okta announced its first quarter fiscal year 2024 financial results:
- Q1 revenue grew 25% year-over-year to $518 million, and subscription revenue increased 26% year-over-year to $503 million.
- Current remaining performance obligations (cRPO) rose 20% year-over-year to $1.70 billion.
- The company reported a record operating cash flow of $129 million and free cash flow of $124 million.
- GAAP operating loss stood at $160 million, a significant reduction from the loss of $240 million in the same period the previous year.
- Non-GAAP operating income was $37 million, compared to a non-GAAP operating loss of $41 million in Q1 2023.
- GAAP net loss was $119 million, a decrease from $243 million in the first quarter of fiscal 2023.
- Non-GAAP net income came in at $38 million, compared to a Non-GAAP net loss of $43 million in Q1 2023.
- Okta repurchased $366 million principal amount of the convertible senior notes due in 2025, resulting in a gain on early extinguishment of debt of $31 million.
For the second quarter of fiscal 2024, Okta expects total revenue of $533 million to $535 million and a non-GAAP operating income of $36 million to $38 million. For the full fiscal year 2024, Okta now anticipates total revenue of $2.175 billion to $2.185 billion and a non-GAAP operating income of $161 million to $170 million.
Wall Street Action
- Trevor Walsh from JMP Securities stands by his Market Outperform rating on Okta, preserving a price target of $110.
- Brian Colley from Stephens & Co. reaffirms an Equal-Weight stance on Okta, keeping a price target of $84.
- Keith Bachman at BMO Capital shifts Okta from Outperform to Market Perform, dropping the price target to $85.
- Ittai Kidron from Oppenheimer maintains his Outperform outlook on Okta, holding a price target of $110.
- Peter Weed of Bernstein keeps a Market Perform position on Okta, adjusting the price target down to $84.
- Alex Henderson from Needham reasserts a Buy recommendation on Okta, keeping the price target at $100.
- Brian Essex at JP Morgan downgrades Okta from Overweight to Neutral, lowering his price target to $85.
Half of the analysts covering the stock are well reserved despite unanimously increasing their price targets three months ago. Joel Fishbein of Truist is the most bearish at $75.
Daily stock Analysts Top Price Moves Snapshot
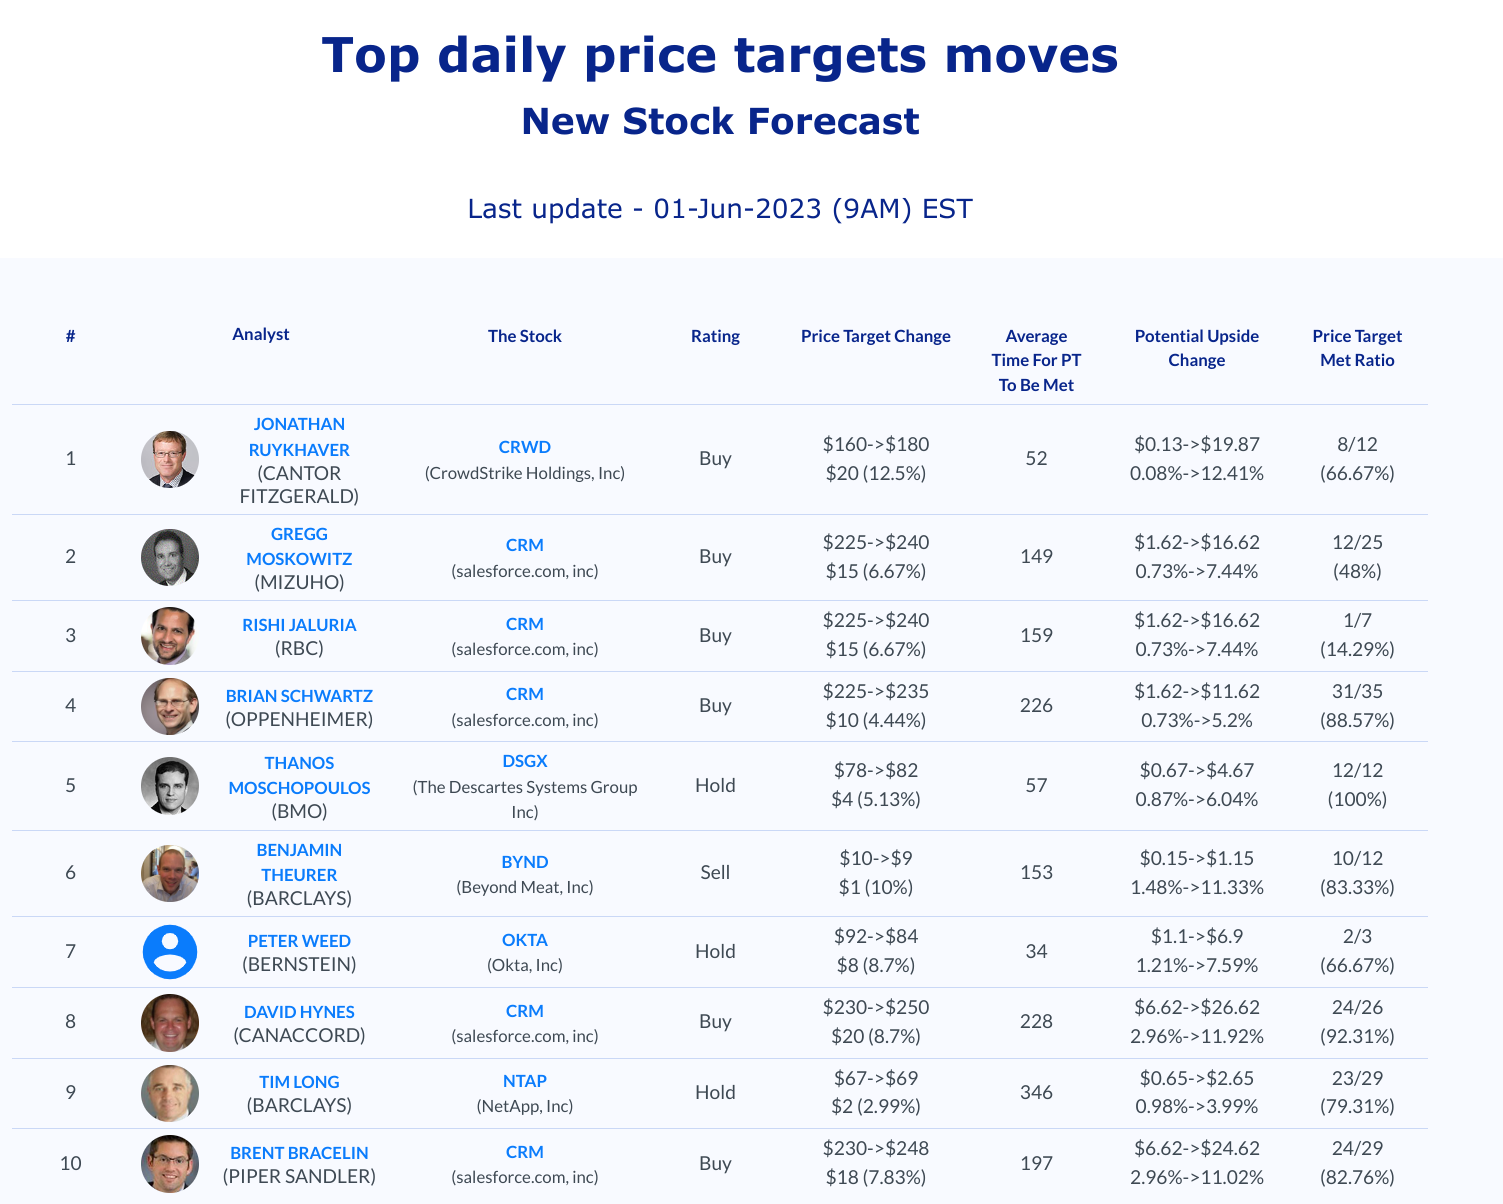
June 2, 2023: Selected stock price target news of the day: June 02, 2023
By Matthew Otto
MongoDB's Q1 2024 Earnings Beat Expectations with 29% Revenue Surge
The financial results of MongoDB for the first quarter of fiscal 2024 revealed strong performance with significant growth. The company reported total revenue of $368.3 million, reflecting a 29% increase year-over-year (versus the predicted $347 million. Atlas revenue in particular witnessed a 40% growth and the company added more customers than anticipated over the past two years.
In terms of financial highlights, the gross profit was $270.8 million, indicating a gross margin of 74%, slightly up from 73% in the previous year. The loss from operations was lesser this quarter ($68.5 million) compared to the same period in the previous year ($75.9 million). MongoDB's net loss stood at $54.2 million, lower than the previous year's net loss of $77.3 million.
The adjusted earnings were 56 cents per share, a significant beat compared to the 19 cents per share that was anticipated by analysts, according to Refinitiv.
Net loss for the quarter was $54 million, or 77 cents per share, which is an improvement over the net loss of $77 million, or $1.14 per share, from the same quarter in the previous year.
MongoDB had $1.9 billion in cash and equivalents, and generated $53.7 million of cash from operations in this quarter, up from $11.6 million in the same quarter of the previous year.
Business highlights included extending a strategic partnership with Alibaba through 2027 and an impressive record of over 150,000 banking transactions per second processed on the Temenos Banking Cloud using MongoDB Atlas.
Price Targets Increased Across the Board
- Analyst Miller Jump at Truist Securities reiterated a Buy rating and escalated the price target from $235 to $365.
- Matthew Broome at Mizuho sustained a Neutral rating while lifting the price target from $180 to $220.
- Ittai Kidron of Oppenheimer preserved an Outperform rating and elevated the price target from $270 to $430.
- Needham's Mike Cikos held onto a Buy rating and boosted the price target from $250 to $430.
- William Power at Baird retained an Outperform rating and hiked the price target from $290 to $390.
- Citigroup's Tyler Radke kept a Buy rating and amplified the price target from $363 to $430.
- Raimo Lenschow at Barclays persisted with an Overweight rating and increased the price target from $280 to $374.
- Patrick Walravens of JMP Securities sustained a Market Outperform rating and heightened the price target from $245 to $370.
- Kash Rangan at Goldman Sachs adhered to a Buy rating and raised the price target from $280 to $420.
- Brent Bracelin from Piper Sandler maintained an Overweight rating and advanced the price target from $270 to $400.
- Karl Keirstead of UBS elevated the price target to $425.
- Rishi Jaluria at RBC Capital raised the price target to $400.
The stock has not moved much in the last year with some analysts having a reserved look such as Howard Ma of Guggenheim.
Analyst Brent Bracelin has currently the highest performing score on MDB with 19/23 (82.61%) price target fulfillment ratio. His price targets carry on average an $47.18 (21.27%) potential upside and typically reach target within an average of 74 days.
Dollar General Adjusts Fiscal Year Guidance
Dollar General has reported its financial results for the first quarter of fiscal 2023, ending May 5, 2023, revealing a mixed performance.
Key highlights include:
- Net sales increased by 6.8%.
- Same-store sales saw a moderate increase of 1.6%.
- Operating profit decreased slightly by 0.7%, amounting to $740.9 million.
- Diluted Earnings Per Share (EPS) declined by 2.9% to $2.34.
- Cash flows from operations stood at $191 million.
However, Dollar General also adjusted its financial guidance for fiscal year 2023 due to a more challenging macroeconomic environment than previously anticipated. The company now expects:
- Net sales growth in the range of approximately 3.5% to 5.0%, compared to its previous expectation of 5.5% to 6%.
- Same-store sales growth in the range of approximately 1.0% to 2.0%, compared to its previous expectation of 3.0% to 3.5%.
- Diluted EPS in the range of an approximate 8% decline to flat, compared to its previous expectation of growth of approximately 4% to 6%.
Dollar General also intends to reduce the number of expected new store openings in the pOpshelf format in 2023, now expecting 3,110 real estate projects in the United States, down from the previous expectation of 3,170 projects.
CEO Jeff Owen cited lower tax refunds and bad weather in March and April as some of the reasons for the weaker-than-expected sales. He also acknowledged the adverse impact of the macroeconomic environment, particularly on the company's core customer base.
Wall Street Action
- Kelly Bania from BMO Capital maintains a Market Perform rating but revises the price target downwards from $230 to $175.
- Scot Ciccarelli from Truist Securities sustains a Hold rating and decreases the price target from $214 to $166.
- Karen Short from Credit Suisse keeps a Neutral rating and lowers the price target from $220 to $170.
- Bobby Griffin from Raymond James persists with a Strong Buy rating but trims the price target from $255 to $200.
- Edward Kelly from Wells Fargo maintains an Overweight rating and cuts the price target from $245 to $178.
- Robert Ohmes from B of A Securities continues with an Underperform rating and reduces the price target from $190 to $155.
- Rupesh Parikh from Oppenheimer retains an Outperform rating and brings down the price target from $240 to $200.
- Krisztina Katai from Deutsche Bank upholds a Buy rating and adjusts the price target downwards from $256 to $201.
- Joseph Feldman from Telsey Advisory Group reiterates an Outperform rating and sustains a $242 price target.
- Peter Keith from Piper Sandler downgrades Dollar General from Overweight to Neutral and drops the price target from $275 to $178.
The decline in the stock price has caught all the analysts by surprise as they all had substantial upside views prior to yesterday.
Analyst Kelly Bania of BMO has currently the highest performing score on DG with 11/15 (73.33%) price target fulfillment ratio. Her price targets carry on average an $17.22 (11.62%) potential upside and typically reach target within an average of 223 days.
Zscaler's Q3 2023 Revenue Jumps 46% YoY to $418.8 Million
Zscaler announced strong Q3 2023 financial results, ended on April 30, 2023, with significant increases in several key metrics:
- Revenue: Grew by 46% year-over-year, reaching $418.8 million.
- Calculated Billings: Rose by 40% year-over-year, amounting to $482.3 million.
- Deferred Revenue: Increased by 44% year-over-year, totaling $1,175.4 million.
- GAAP Net Loss: Improved from a loss of $101.4 million to a loss of $46.0 million year-over-year.
- Non-GAAP Net Income: Increased from $24.7 million to $74.6 million year-over-year.
Looking ahead, for the fourth quarter of fiscal 2023, Zscaler expects:
- Revenue: $429 million to $431 million.
- Non-GAAP income from operations: $69 million to $70 million.
- Non-GAAP net income per share: Approximately $0.49.
For the full fiscal year 2023, Zscaler expects:
- Revenue: Approximately $1.591 billion to $1.593 billion.
- Calculated billings: $1.974 billion to $1.978 billion.
- Non-GAAP income from operations: $224 million to $225 million.
- Non-GAAP net income per share: $1.63 to $1.64.
Zscaler Q3 2023 Results Elicit Upward Price Target Revisions by Analysts
- Stifel's Adam Borg maintains a Buy rating on Zscaler, raising the price target from $135 to $150.
- Scotiabank's Patrick Colville holds a Sector Outperform position, lifting the price target from $138 to $150.
- Evercore ISI Group's Peter Levine maintains an Outperform rating, increasing the price target from $165 to $170.
- Loop Capital's Yun Kim keeps a Hold rating, raising the price target from $125 to $135.
- BMO Capital's Keith Bachman sustains an Outperform position, upping the price target from $120 to $150.
- Wells Fargo's Andrew Nowinski persists with an Overweight stance, raising the price target from $156 to $175.
- RBC Capital's Matthew Hedberg keeps an Outperform rating, with the price target lifted from $155 to $162.
- UBS's Roger Boyd maintains a Buy rating, raising the price target from $170 to $175.
- Canaccord Genuity's Michael Walkley keeps a Buy position, lifting the price target from $155 to $160.
- Barclays' Saket Kalia continues with an Equal-Weight rating, upping the price target from $127 to $145.
Analyst Trevor Walsh of JMP has the current street high.
Analyst Alex Henderson of Needham has currently the highest performing score on ZS stock with 15/23 (65.22%) price target fulfillment ratio. His price targets carry on average an $46.04 (32.22%) potential upside and typically reach target within an average of 69 days.
Daily stock Analysts Top Price Moves Snapshot
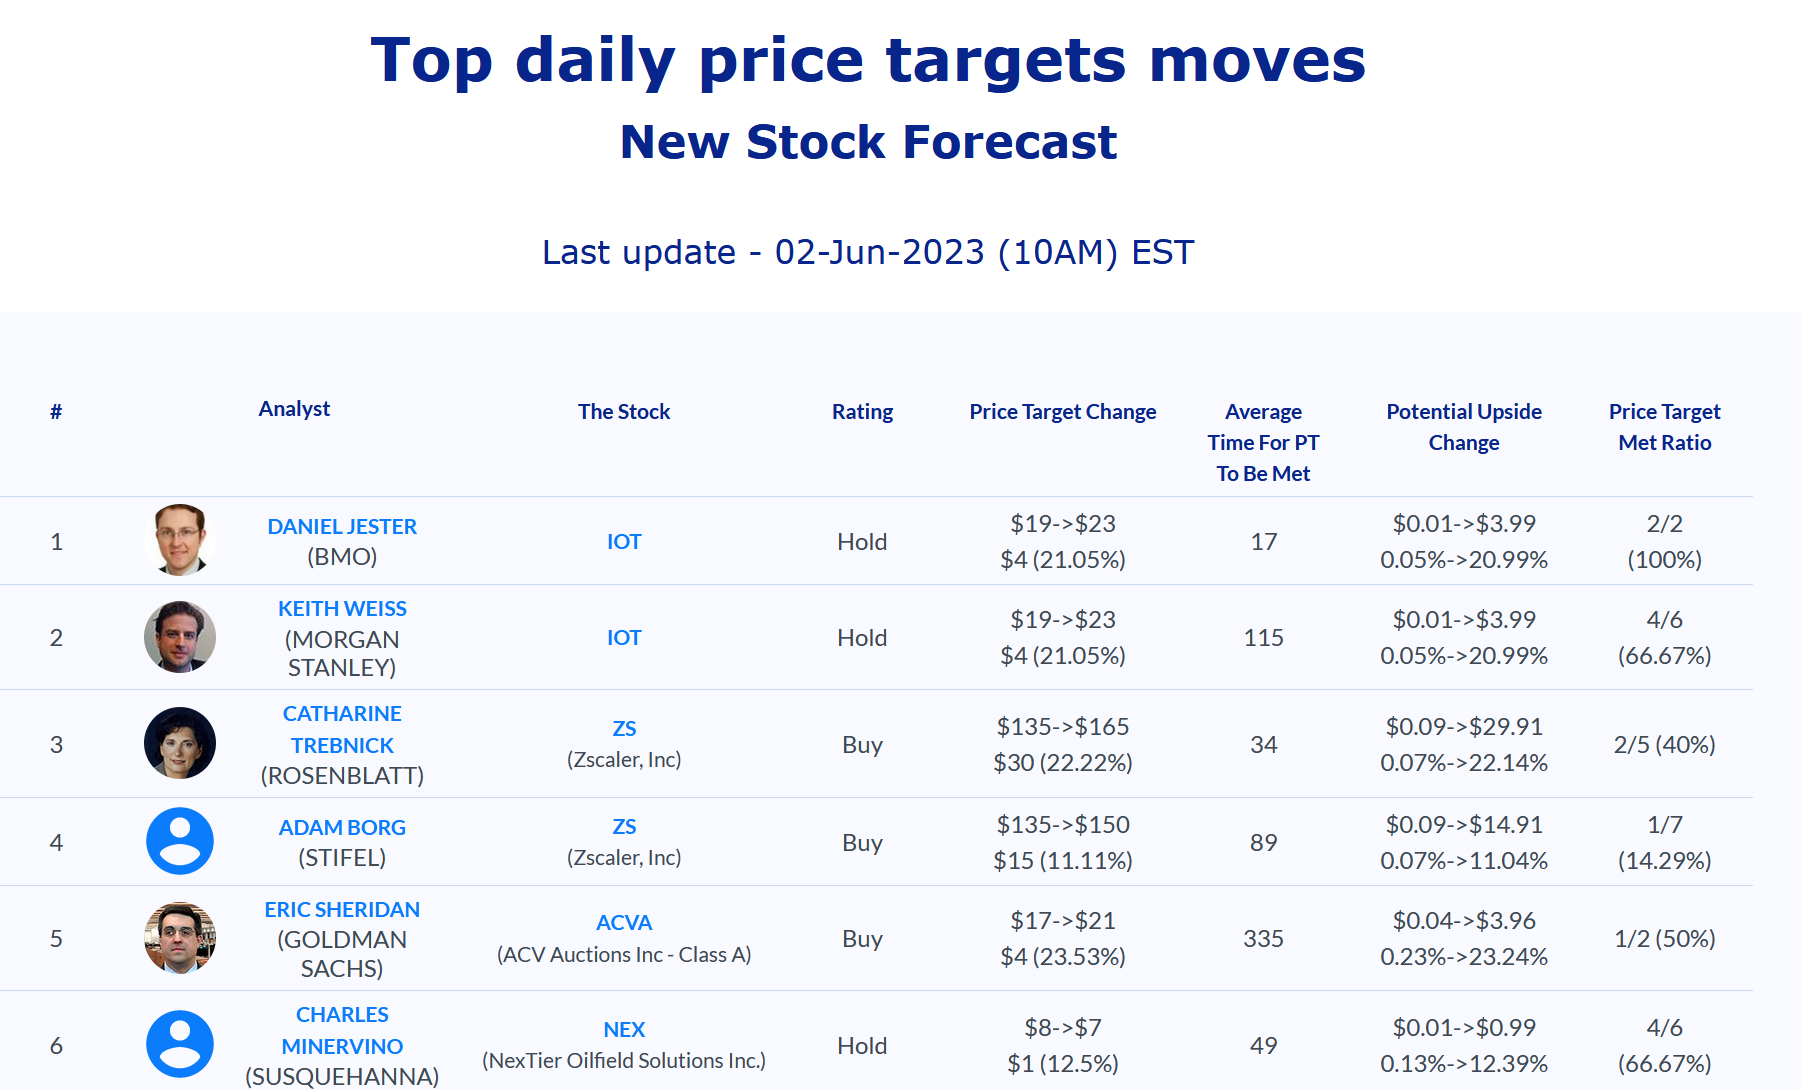
June 5, 2023: Selected stock price target news of the day: June 05, 2023
By Matthew Otto
Five Below Upgraded Revenue and Profit Forecasts
Five Below has announced their first quarter financial results for fiscal 2023 last Friday. The Philadelphia-based company has shown growth across key areas:
- Net Sales: Five Below's net sales have seen an increase of 13.5%, rising from $639.6 million in Q1 2022 to $726.2 million in Q1 2023.
- Comparable Sales: The company also recorded an increase of 2.7% in comparable sales, along with a 3.9% increase in comparable transactions.
- EPS: The earnings per share (EPS) rose by 13.6% to $0.67.
- Store Openings: Five Below opened 27 new stores in Q1 2023, ending the quarter with a total of 1,367 stores in 43 states, an 11.6% increase from Q1 2022.
- Operating Income & Net Income: The company saw a slight increase in operating income to $42.4 million, and net income saw a more substantial rise from $32.7 million in Q1 2022 to $37.5 million in Q1 2023.
- Effective Tax Rate: Five Below reported an effective tax rate of 18.6%, which is lower compared to the 22.3% from Q1 2022.
Joel Anderson, President and CEO, expressed satisfaction with the results, particularly highlighting the 3.9% comp transaction increase. Anderson also shared the company's ambitious plans for the remainder of 2023, which include opening over 200 new stores and completing over 400 conversions to the new Five Beyond prototype.
For the second quarter of fiscal 2023, the company expects net sales to range from $755 million to $765 million, with net income projected to be between $44 million to $48 million. The full year outlook for fiscal 2023 indicates expected net sales in the range of $3.50 billion to $3.57 billion and net income between $297 million to $319 million.
Wall Street Action
- Craig-Hallum analyst Jeremy Hamblin maintains a Buy rating, but has lowered the price target from $235 to $224.
- Deutsche Bank analyst Krisztina Katai also maintains a Buy rating, raising the price target slightly from $238 to $239.
- Roth MKM analyst David Bellinger continues to rate Five Below as a Buy, while adjusting the price target down from $240 to $225.
- Truist Securities analyst Scot Ciccarelli holds a Buy rating but has reduced the price target from $224 to $222.
- JP Morgan analyst Matthew Boss has a lower price target at $200. Guggenheim analyst John Heinbockel reiterated a Buy rating with a $220 price target.
Not all analysts are positive on the Five Below stock. Anthony Chukumba of Loop Capital is more on the reserved side with a $200 price target and a hold rating
Analyst Scot Ciccarelli of Truist has currently the highest performing score on FIVE with 22/23 (95.65%) price target fulfillment ratio. His price targets carry on average an $39.45 (21.61%) potential upside and typically reach target within an average of 116 days.
Anticipation of Apple’s Mixed-Reality Headset Launch and Potential AI Strategy Reveal
Apple prepares for several product launches, including the much-anticipated mixed-reality headset.
The mixed-reality headset, reported to include high-definition screens and high-powered cameras enabling user interaction with the real world. Marks Apple's significant venture into a technology sphere that has seen some disappointment. The hype around VR and metaverse technologies, highlighted by Facebook's rebranding as Meta in 2021, hasn't lived up to expectations in terms of sales and usage. However, given Apple's extensive customer base, range of apps, variety of platforms, and track record for must-have products, their entry into the metaverse could prove pivotal.
Apple is also expected to unveil its VR/AR headset at the Worldwide Developers Conference. Some suggest this move might be a strategic play to compete with Meta Platforms if the metaverse concept proves to be the next big thing.
Interestingly, the market appears to be even more excited about Apple's potential advancements in artificial intelligence (AI), despite the company not making any recent statements on this front.
Analysts Maintain Optimistic Outlook on Apple
- Wedbush analyst Daniel Ives maintains an Outperform rating, keeping the price target at $205.
- Bank of America Securities analyst Wamsi Mohan maintains a Neutral rating, but raises the price target from $176 to $190.
- Evercore ISI Group analyst Amit Daryanani maintains an Outperform rating, increasing the price target from $190 to $210.
- Morgan Stanley analyst Erik Woodring reiterates an Overweight rating, with a price target of $190.
Most analysts are bullish on the mega stock besides few such as Barclays analyst Tim Long who has an Equal Weight rating and a $145 price target.
Analyst David Vogt of UBS has currently the highest performing score on MDB with 17/22 (77.27%) price target fulfillment ratio. His price targets carry on average an $27.87 (19.75%) potential upside and typically reach target within an average of 90 days.
Day One Reports Positive Trial Results for Tovorafenib in Pediatric Brain Cancer
Day One Biopharmaceuticals has released new data from the registrational Phase 2 FIREFLY-1 trial evaluating tovorafenib (DAY101), an investigational drug developed for the treatment of pediatric low-grade glioma (pLGG). This type of brain tumor is the most common in children, and there are currently no approved systemic therapies for the majority of patients with pLGG.
The Phase 2 trial enrolled 77 patients aged 6 months to 25 years with relapsed or progressive pLGG. According to the data presented at the American Society of Clinical Oncology (ASCO) Annual Meeting 2023, the trial demonstrated promising results, with 67% overall response rate (ORR) by Response Assessment for Neuro-Oncology High-Grade Glioma (RANO-HGG) criteria.
Day One has also initiated a rolling New Drug Application (NDA) to the U.S. Food and Drug Administration (FDA). This means that the company can submit parts of the regulatory application for review by the FDA as they become available, rather than waiting to complete the entire application. This process can expedite the review and potential approval of new drugs. The company expects the rolling NDA submission of tovorafenib to be complete by October 2023.
Analysts maintain optimism on Day One prospects
- Wedbush analyst Robert Driscoll reiterated an Outperform rating and maintained a $38 price target.
- Needham analyst Ami Fadia reaffirmed a Buy rating and kept the $40 price target.
- HC Wainwright & Co. analyst Andres Maldonado maintained a Buy rating and raised the price target from $45 to $50.
Despite holding opinions that reflect over a 100% potential upside on average from the current stock price. It should be highlighted that no analyst's price target for Day One Biopharmaceuticals has come to fruition since initiating coverage. Consequently, all analysts have a performance score of zero on AnaChart for the Day One Biopharmaceuticals stock.
Daily stock Analysts Top Price Moves Snapshot

June 6, 2023: Selected stock price target news of the day: June 06, 2023
By Matthew Otto
EPAM Lowers Outlook, Falling Short of Analyst Expectations
EPAM Systems has announced a reduction in its financial outlook for the second quarter and full year 2023, attributing the decision to a deterioration in near-term demand. The company noted a more cautious spending pattern in the build segment of the global IT services market, leading to slower pipeline conversions and an overall reduction in the total pipeline.
For the full year, the company now projects revenues between $4.65 billion to $4.8 billion, indicating a 2% decrease year-over-year at the midpoint of the range. GAAP income from operations is expected to fall within 11% to 12% range, and non-GAAP income from operations within 15% to 16%. GAAP diluted EPS is now projected to range from $7.28 to $7.68 and non-GAAP diluted EPS between $9.80 to $10.20.
For the second quarter, revenues are expected to range from $1.160 billion to $1.170 billion ($2.33 and $2.40 was slightly below the FactSet estimate of $2.43), a 2.5% decrease year-over-year at the midpoint of the range. GAAP income from operations should remain within the 10% to 11% range, while non-GAAP income from operations within the 14% to 15% range. The GAAP effective tax rate should be around 20% and non-GAAP tax rate approximately 23%. GAAP diluted EPS is expected to fall within $1.75 to $1.82 and non-GAAP diluted EPS between $2.33 to $2.40.
Wall Street Switches to Hold
- Stifel analyst David Grossman has maintained a Buy rating but reduced the price target from $320 to $240.
- Barclays analyst Ramsey El-Assal downgraded from Overweight to Equal-Weight and lowered the price target from $310 to $220.
- Piper Sandler analyst Arvind Ramnani also downgraded from Overweight to Neutral and lowered the price target from $289 to $215.
- Keybanc analyst Thomas Blakey dropped EPAM from Overweight to Sector Weight.
This sort of shift from Buy to Hold ratings accompanied by more than one analyst usually is not a common occurrence and is a rare indicator of how Wall Street loses faith in a stock's prospects. The
Analyst Mayank Tandon of Needham has currently the highest performing score on EPAM with 26/33 (78.79%) price target fulfillment ratio. His price targets carry on average an $71.75 (35.30%) potential upside and typically reach target within an average of 93 days
GitLab demonstrates strength along demand for AI
GitLab announced its first quarter fiscal year 2024 financial results and surpassed analyst estimates on key metrics.
Key Financial Highlights:
- GitLab reported a Q1 non-GAAP EPS of ($0.06), which was $0.08 better than the analyst estimate of ($0.14).
- The total revenue for the quarter was $126.9 million, exceeding the consensus estimate of $117.84 million.
GitLab's CEO, Sid Sijbrandij, emphasized the company's positioning as a leading AI-powered DevSecOps platform, offering unique capabilities to their customers.
CFO Brian Robins noted the organic growth of the company, emphasizing the 45% YoY increase in revenue and the significant improvement in non-GAAP operating margin.
The company also provided its financial outlook for the second quarter and fiscal year 2024, outperforming consensus estimates:
- For Q2 FY 2024, GitLab expects EPS of ($0.03)-($0.02), better than the consensus estimate of ($0.08). The company anticipates revenue to be between $129 million and $130 million, higher than the consensus of $127 million.
- For FY 2024, GitLab forecasts EPS of ($0.18)-($0.14), again better than the consensus of ($0.26). The company also expects its revenue to be between $541 million and $543 million, exceeding the consensus of $533 million.
Analysts Bullish with Raised Price Targets
- RBC Capital's Matthew Hedberg kept his Outperform rating, but upped the price target from $45 to $56.
- TD Cowen's J. Derrick Wood also stood by his Outperform rating, boosting the price target from $44 to $56.
- BofA Securities' Koji Ikeda held his Buy rating, increasing the price target from $50 to $55.
- Mizuho's Gregg Moskowitz retained a Neutral rating and lifted the price target from $38 to $45.
- UBS's Karl Keirstead raised the price target from $35.00 to $50.00, while maintaining a Buy rating.
- Scotiabank's Nick Altmann increased the price target to $50.
Since going public the stock lost more than two thirds of its value while all analysts kept an optimistic look.
Analyst Matthew Hedberg of RBS has currently the highest performing score on GTLB with 5/15 (33.33%) price target fulfillment ratio. His price targets carry on average an $18.19 (33.05%) potential upside and typically reach target within an average of 53 days.
Sprinklr Surpasses Q1 EPS Estimates, Forecasts Strong Growth for FY2024
Sprinklr reported Q1 EPS of $0.06, significantly beating the analyst estimate of $0.01 by $0.05. Total revenue for the quarter came in at $173.4 million, exceeding the consensus estimate of $169 million.
The first quarter saw Sprinklr continue its growth trajectory, with total revenue and subscription revenue up 20% and 24% year-over-year, respectively. Ragy Thomas,
For Q2 2024, Sprinklr is forecasting EPS in the range of $0.04-$0.05, surpassing the consensus estimate of $0.03. It also expects revenue to be between $172-174 million, in line with the consensus estimate of $173.2 million.
Looking ahead to FY 2024, Sprinklr forecasts an EPS of $0.19-$0.21, greatly exceeding the consensus estimate of $0.14. Revenue for FY 2024 is projected to be between $711-715 million, slightly below the consensus estimate of $712.3 million.
Analysts Raise Price Targets on Strong Fiscal 2024 Outlook
- JP Morgan analyst Pinjalim Bora maintains an Overweight stance, boosting the price target from $14 to $16.
- BTIG analyst Matt VanVliet retains a Buy rating, hiking the price target from $16 to $17.
- Stifel analyst Parker Lane holds steady, uplifting the price target from $13 to $15.
- JMP Securities analyst Patrick Walravens preserves a Market Outperform rating, amplifying the price target from $20 to $24.
- Cantor Fitzgerald analyst Brett Knoblauch lifts his price target to $17.
- BTIG analyst Matt VanVliet elevates his price target to $17.
- Citi Analyst Tyler Radke ups the price target to $15 while maintaining a Neutral rating.
The stock is currently at two thirds of its market value when it had its IPO last year. Nearly half of analysts carry a Hold rating on the stock.
Analyst Michael Turrin of Wells Fargo has currently the highest performing score on CXM with 5/7 (71.43%) price target fulfillment ratio. His price targets carry on average an $-0.04 (-0.11%) potential downside and typically reach target within an average of 29 days.
Daily stock Analysts Top Price Moves Snapshot
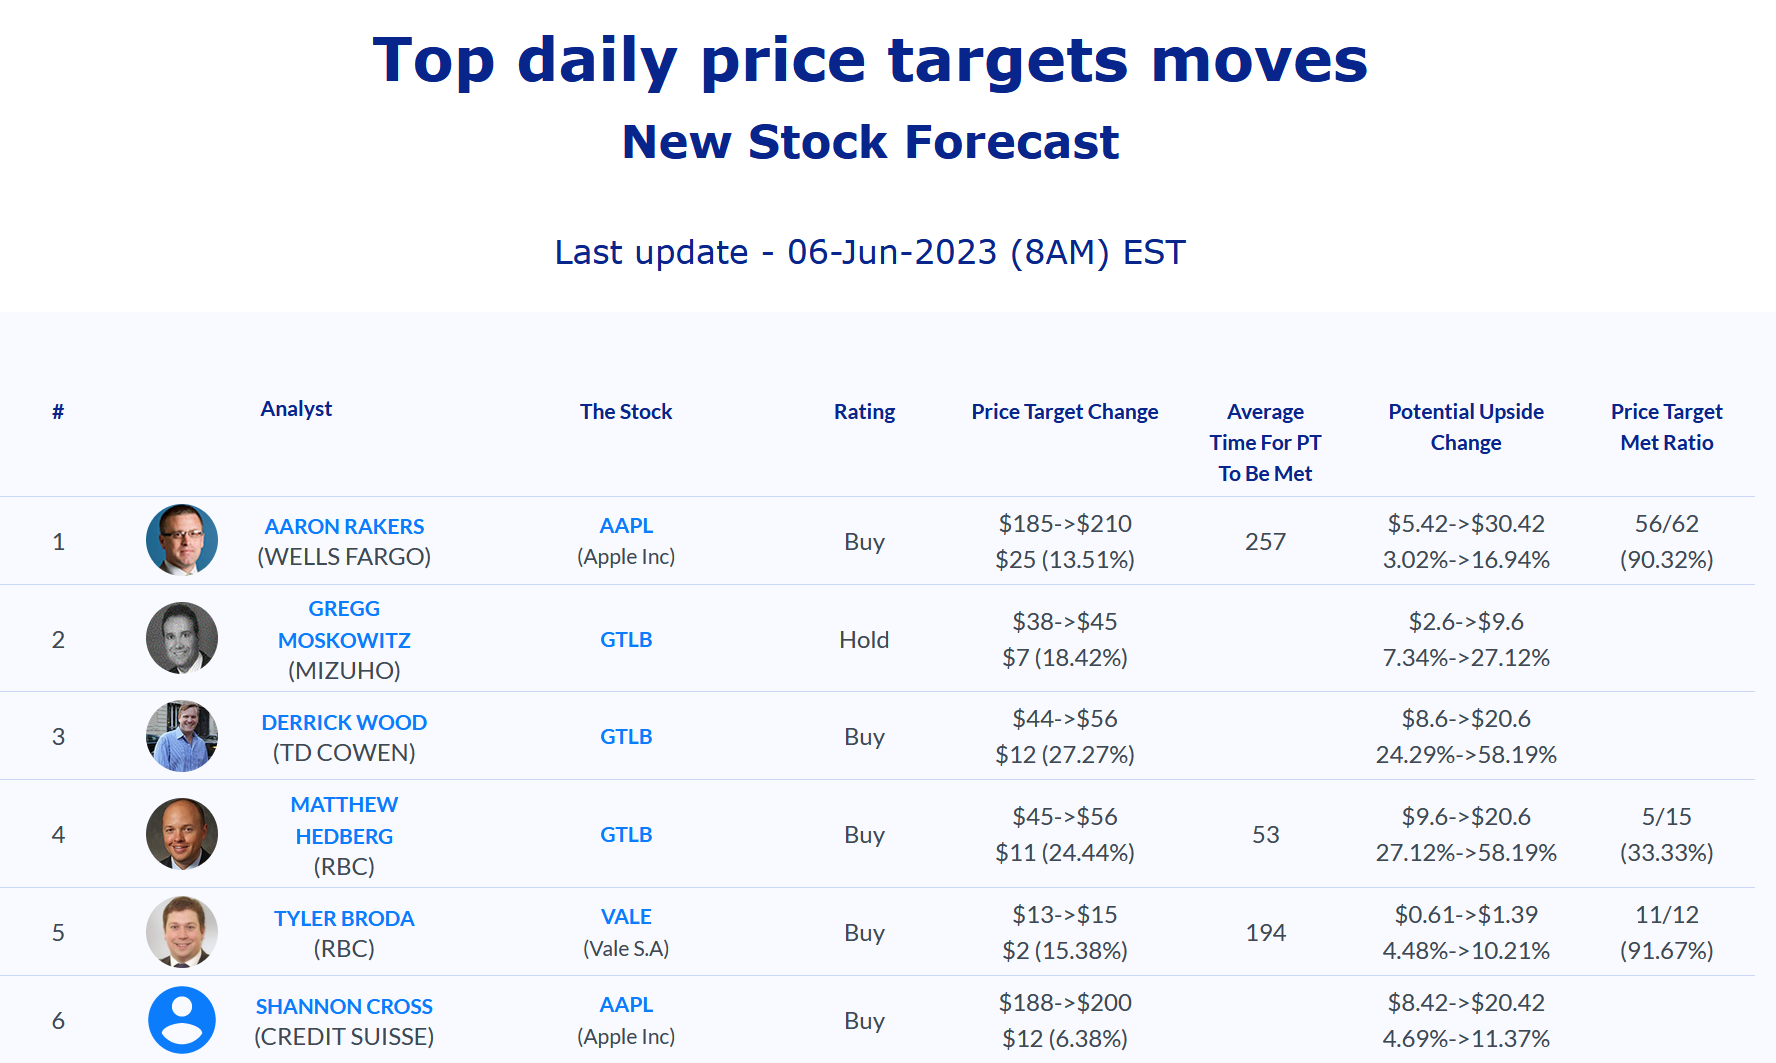
June 7, 2023: Selected stock price target news of the day: June 07, 2023
By Matthew Otto
Hollywood Unrest Continues: WGA Strike Persists Amid New DGA Deal, SAG-AFTRA Braces for Possible Strike
The ongoing strike by the Writers Guild of America (WGA) is causing significant disruptions in the film and television industry. Shows like "Stranger Things," "A Knight of the Seven Kingdoms: The Hedge Night. " "Thunderbolts," and "Blade" either halting or postponing production. This strike, which has been in effect since May 2, 2023. Follows unsuccessful talks between the WGA and the Alliance of Motion Picture and Television Producers (AMPTP) concerning pay and working conditions.
In a separate development, the Directors Guild of America (DGA) has struck a tentative agreement with the AMPTP. Which is set to provide wage and benefit increases, heightened residuals from streaming. Safeguards against artificial intelligence (AI) replacing jobs held by guild members. However, the WGA has stated that the DGA's agreement will not impact their ongoing strike.
The Screen Actors Guild and the American Federation of Television and Radio Artists are also on the brink of authorizing a potential strike as they commence negotiations with producers. Both the WGA and SAG-AFTRA are seeking protections against the use of AI in their negotiations, alongside pay increases for streamed content.
AI has become a significant issue as both guilds believe their jobs are particularly vulnerable to this emergent technology. The WGA is primarily concerned that production companies will leverage AI to reduce writers' salaries. SAG-AFTRA is advocating for the consent and payment of actors whose performances might be replicated by AI technology.
Netflix is directly affected by the strike as she production of the fifth and final season of its popular series "Stranger Things" has been postponed due to the strike
Wells Fargo and JP Morgan raise price targets
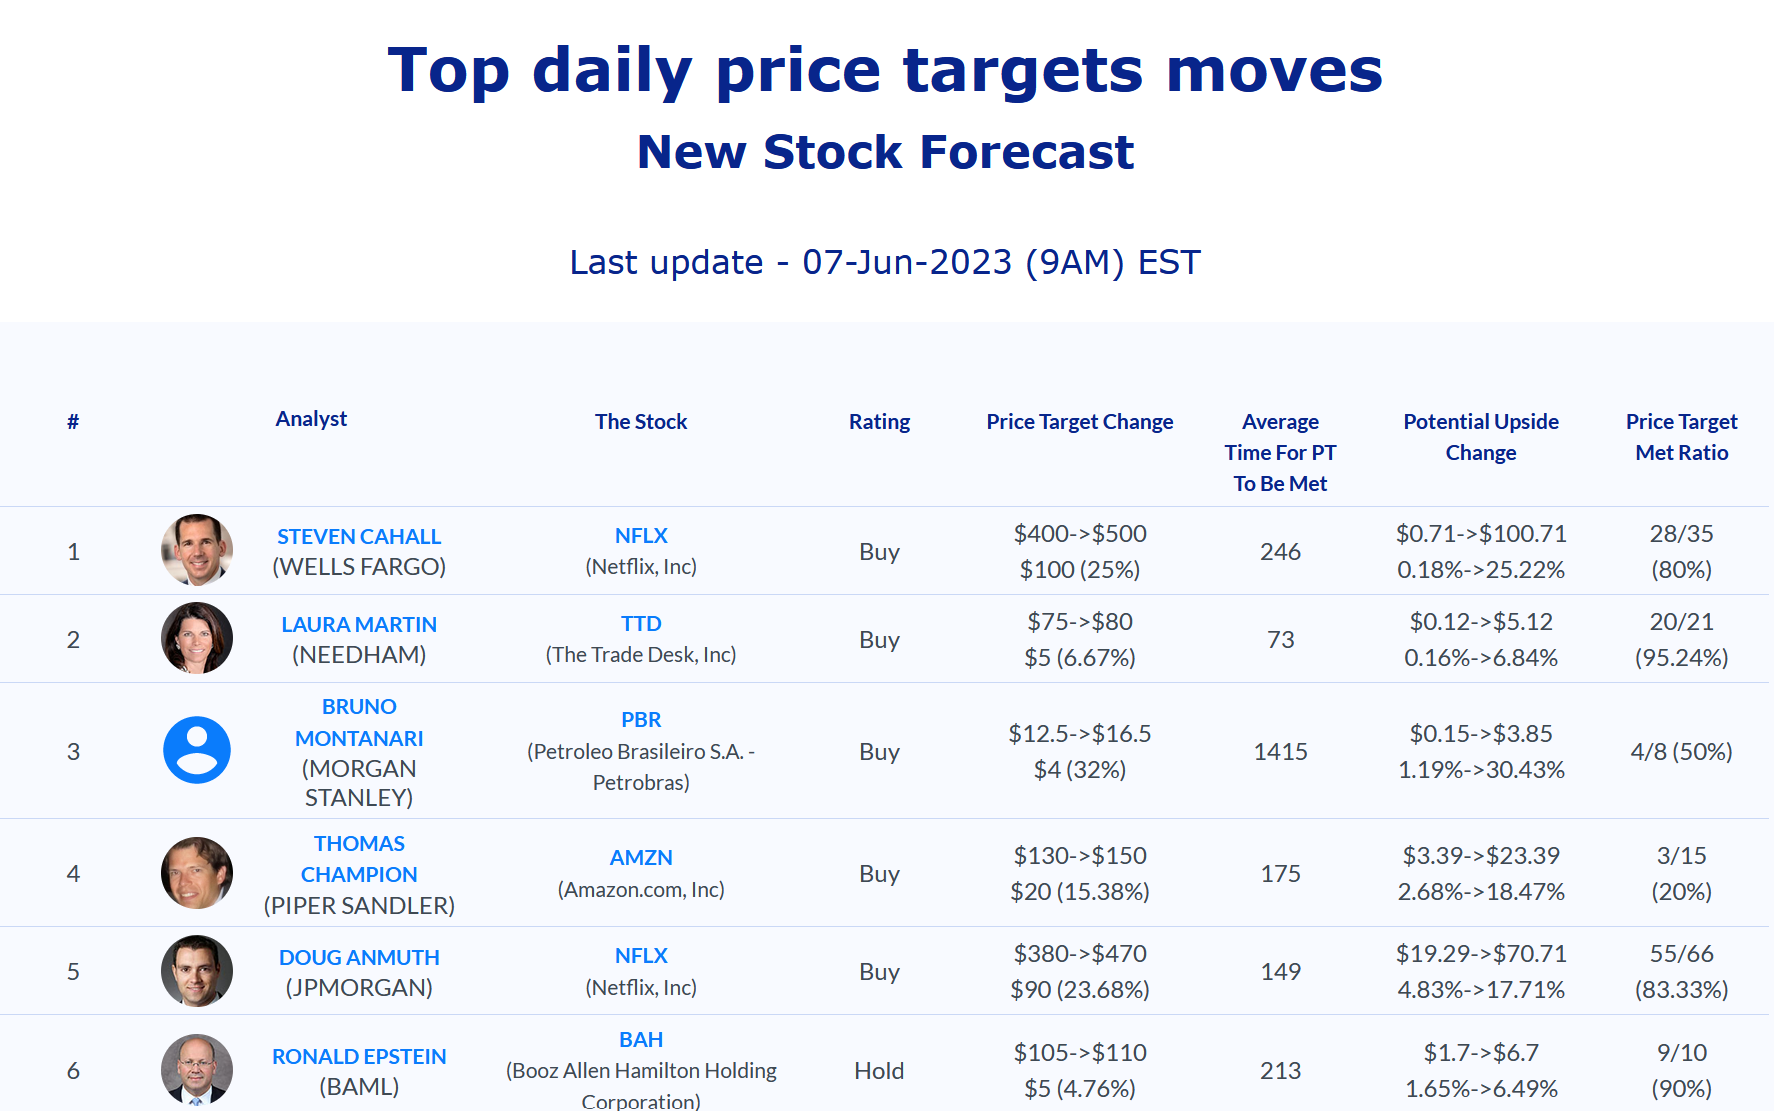
- Wells Fargo analyst Steven Cahall maintains an Overweight rating on Netflix, raising the price target from $400 to $500.
- JP Morgan analyst Doug Anmuth also keeps his Overweight rating on Netflix, increasing the price target from $380 to $470.
Most analysts are bullish on the Netflix stock however some analysts such as Matthew Harrigan of Benchmark have a sell rating and a price target below the stock price.
Analyst John Blackledge of Cowen has currently the highest performing score on NFLX with 44/49 (89.8%) price target fulfillment ratio. His price targets carry on average an $65.61 (22.61%) potential upside and are fulfilled within average of 74 days.
Novocure's TTFields Therapy Shows Promising Results in Phase 3 Lung Cancer Trial; Critics Question Standard of Care
Novocure has reported positive results from its Phase 3 LUNAR clinical trial evaluating the use of Tumor Treating Fields (TTFields) therapy. Also known as Optune, in conjunction with standard therapies for non-small cell lung cancer (NSCLC). However, the market reaction to the test results was mixed, causing a sharp decline in Novocure's stock value.
The TTFields therapy, a wearable skin patch that delivers electrical fields to disrupt the rapid division of cancer cells. Calimes to extend patients' overall survival by a median of 3.3 months when added to standard therapies. Patients treated with TTFields alongside immune checkpoint inhibitors, like Merck's Keytruda or Bristol Myers Squibb's Opdivo. Showed a "profound" benefit, living a median of 7.7 months longer than those treated with checkpoint inhibitors alone.
However, critics argue that Novocure tested Optune in patients who had worsened following chemotherapy. Which is no longer the standard of care in lung cancer. Specifically, the scrutiny of progression-free survival, a measure of how long patients live on treatment before their cancer worsens. The use of Optune with standard drugs extended progression-free survival to 4.8 months compared to 4.1 months for standard drugs alone.
Currently, Optune is approved for treating a form of brain cancer. However, approval in NSCLC would significantly expand Novocure's market. The company plans to submit the LUNAR clinical trial results for publication in a leading. Peer-reviewed medical journal and use the data as the basis for a Premarket Approval (PMA) submission to the U.S. Food and Drug Administration in the second half of 2023.
Wall Street Action
- Wedbush analyst David Nierengarten upgraded NovoCure from Underperform to Neutral however lowered the price target from $53 to $46.
- Truist Securities analyst Gregory Fraser reiterated a Buy rating on NovoCure, maintaining a $95 price target.
- HC Wainwright analyst Emily Bodnar also reiterated a Buy rating and a price target at $115
The stock is traded at 25% from its peak value of $221 in 2021.
Analyst Vijay Kumar from Evercore had shown a very prudent stance throughout the last few years with his bearish stance.
Analyst Jessica Fye of JP Morgan has currently the highest performing score on NVCR with 3/3 (100%) price target fulfillment ratio. Her price targets carry on average an $-6.7 (-8.42%)potential downside and are fulfilled within average of 42 days.
Paratek to be Acquired in $462 Million Deal
Paratek Pharmaceuticals is set to be acquired by Gurnet Point Capital and Novo Holdings in a transaction estimated to be approximately $462 million. The pruchase includes the assumption of debt and full payment of a Contingent Value Right (CVR). Oaktree Capital Management will provide $175 million debt financing for the deal.
Gurnet Point and Novo Holdings will buy all outstanding shares of Paratek for $2.15 each in cash. Along with a CVR of $0.85 per share, which will be payable when Paratek reaches $320 million in U.S. NUZYRA net sales in any calendar year ending on or before December 31, 2026. The upfront payment offers a premium of 41% over the closing price of Paratek's as of May 31, 2023.
The transaction, unanimously approved by the Paratek Board of Directors, is expected to close in the third quarter of 2023. After completion, Paratek will become a private company and will no longer be listed on the Nasdaq Global Market.
Wall Street Action
- HC Wainwright & Co.'s analyst Ed Arce has downgraded Paratek Pharmaceuticals from Buy to Neutral and set a price target of $2.15.
- Jefferies' analyst Suji Jeong has downgraded Paratek Pharmaceuticals from Buy to Hold and lowered the price target from $5 to $2.15.
The stock lost over 90% of its value since its IPO in 2015 with all analysts recommending to buy and carrying potential upside in the process. Currently there are no analysts that gave realistic price targets that were met and as result all analysts have a performance score of zero on the stock.
Daily stock Analysts Top Price Moves Snapshot
June 8, 2023: Selected stock price target news of the day: June 08, 2023
By: Matthew Otto
Academy Sports Outdoors Reports Earnings Decline; Revises Down Fiscal 2023 Guidance
Academy Sports and Outdoors released its financial results yesterday for Q1 2023 ending April 29, showing a decline in sales and profits compared to the same period last year. Net sales fell by 5.7% from $1.47 billion to $1.38 billion, while comparable sales declined by 7.3%. Income before income tax was down by 39.2% to $118.7 million, while net income dropped by 37.3% to $94 million.
The company attributed the underwhelming results to macroeconomic pressures, unfavorable weather, and stronger sales in the hunting business during the same period in 2022. However, Academy's leadership remains confident in its business model and the new long-range plan to drive growth.
During Q1, Academy opened one new store and plans to open between 13 to 15 stores during 2023, with a five-year plan of opening between 120 to 140 stores. The company's cash and cash equivalents have fallen by 37.4% to $295.5 million, while net merchandise inventories rose by 4.7% to $1.39 billion. Long-term debt reduced by 14.5% to $584.1 million.
In light of the Q1 results and ongoing macroeconomic challenges, Academy has revised its 2023 fiscal guidance. Net sales are now projected to be between $6.18 billion and $6.37 billion, down from the previous estimate of between $6.5 billion and $6.7 billion. The company also expects GAAP net income to be between $520 million and $575 million, and GAAP earnings per common share, diluted, to be between $6.50 and $7.20.
Wall Street Action
- Morgan Stanley analyst Simeon Gutman has maintained an Equal-Weight rating and lowered the price target from $70 to $55.
- Evercore ISI Group analyst Greg Melich maintains an Outperform rating and has lowered the price target from $80 to $70.
- UBS analyst Michael Lasser has kept a Buy rating and lowered the price target from $78 to $65.
- Wedbush analyst Seth Basham maintains an Outperform rating and has reduced the price target from $75 to $60.
- Baird analyst Justin Kleber keeps an Outperform rating and has lowered the price target from $75 to $70.
- Oppenheimer analyst Brian Nagel reiterated an Outperform rating for Academy Sports, maintaining a price target of $85.
- BofA Securities analyst Robert Ohmes has lowered the price target to $75.
The stock had quadrupled in value in the last two years with all analysts having their price target above the stock price despite the last few months' withdrawal. However as mentioned earlier Simeon Gurman has changed his rating which might be a cautionary signal.
Analyst Christopher Horvers of JP Morgan has currently the highest performing score on AOS with 5/6 (83.33%) price target fulfillment ratio. His price targets carry on average an $10.01 (25.42%) potential upside and are fulfilled within an average of 195 days.
Rent the Runway Exceeds on Revenue Increase, disappoints on outlook
Rent the Runway has announced its Q1 2023 financial results. The company reported a Q1 EPS of ($0.46), which was $0.02 better than the analyst estimate of ($0.48). Revenue for the quarter came in at $74.2 million, surpassing the consensus estimate of $72.99 million.
The company's active subscriber count reached a record high of 145,220, indicating a 15% quarter-over-quarter growth. This growth was accompanied by a reduction in net loss, from $42.5 million in Q1 2022 to $30.1 million in Q1 2023. Adjusted EBITDA also showed a significant improvement, going from a loss of $8.8 million in Q1 2022 to a positive $4.5 million in Q1 2023.
Looking forward, Rent the Runway provided guidance for Q2 2024, expecting revenues in the range of $77-79 million, compared to the consensus estimate of $81 million. For the full fiscal year 2024, the company anticipates revenues between $320-330 million, closely aligning with the consensus estimate of $325 million.
Wall Street adjusts but not much
- Raymond James analyst Rick Paterson maintains an Outperform rating, but lowers the price target from $8 to $5.
- Telsey Advisory analyst Dana Telsey reiterates an Outperform rating and a $4 price target.
The stock had lost over 85% since its IPO at the end of 2021, some analysts such as Morgan Stanley Lauren Schenk and Michael Binetti of Credit Suisse have downgraded to a Hold rating last year. The rest still carry a Buy with potential upside in their price targets.
Analyst Ross Sandler Barclays has currently the highest performing score on RENT with 1/6 (16.67%) price target fulfillment ratio. His price targets carry on average an $4.75 (85.17%) potential upside and are fulfilled within average of 4 days.
HashiCorp Disappoints on Guidance Expectations:
HashiCorp has released financial results for the first quarter of fiscal 2024, ending April 30, 2023. The company reported a Q1 FY2024 EPS of ($0.07), which is an improvement over the analyst consensus estimate of ($0.14). The company's revenue of $138 million did exceed the consensus estimate of $133.13 million.
Looking forward, HashiCorp's guidance for Q2 FY2024 paints a less rosy picture. It predicts an EPS of ($0.16)-($0.14), which is worse than the consensus estimate of ($0.12). Also, the projected Q2 FY2024 revenue of $137-139 million is lower than the consensus estimate of $141 million, indicating a potential slowdown in sales.
For the full fiscal year 2024, HashiCorp's projections are also lower than analyst expectations. They foresee an EPS of ($0.27)-($0.24), compared to the consensus estimate of ($0.39). Similarly, the expected revenue of $564-570 million falls short of the consensus estimate of $593 million.
Amidst these results and forecasts, HashiCorp has also announced a workforce reduction of approximately 8%. The company's expressed commitment to breakeven by the second half of fiscal year 2025.
Wall Street Action
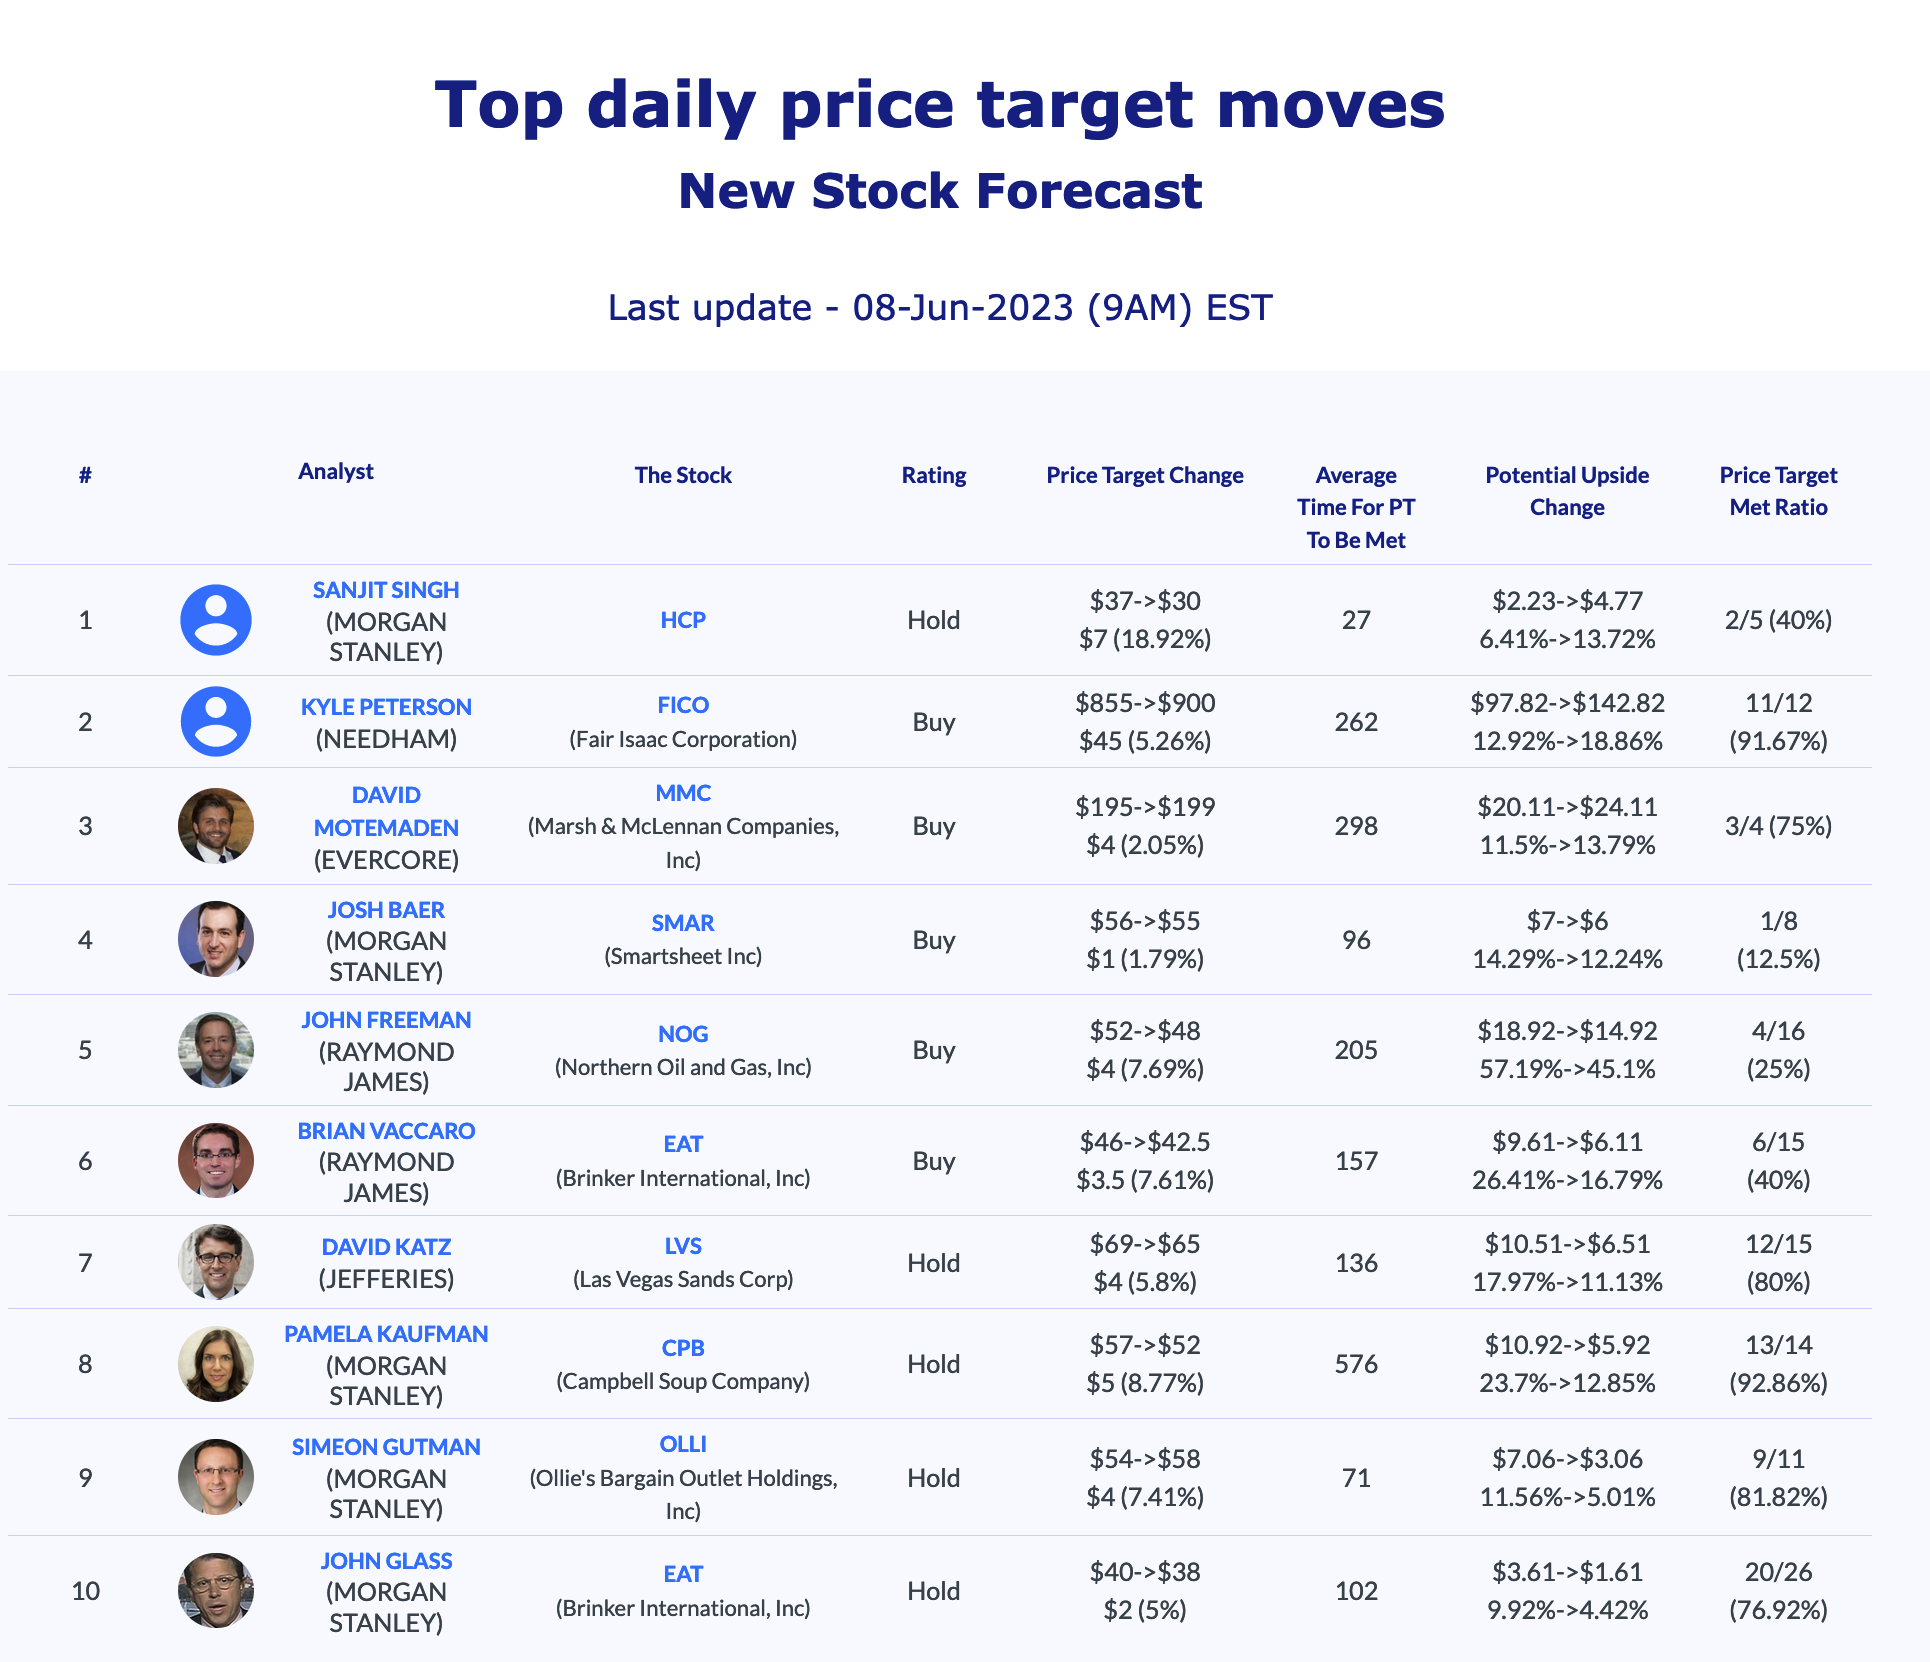
- Morgan Stanley analyst Sanjit Singh maintained an Equal-Weight rating, but reduced the price target from $37 to $30.
- Oppenheimer analyst Ittai Kidron reiterated an Outperform rating, maintaining a $42 price target.
- Needham analyst Alex Henderson continued to rate HashiCorp as a Buy, but lowered the price target from $39 to $34.
- BTIG analyst Gray Powell lowered the price target to $32.
- Wolfe Research analyst Alex Zukin reduced the price target to $30, down from $33.
- JPMorgan analyst Mark Murphy reduced his price target to $26.
- Goldman Sachs analyst Kash Rangan adjusted the price target to $30.
- Stifel analyst Brad Reback maintained a Buy rating, but lowered the price target from $38 to $31.
The stock has lost a bit more than half of its value since going public last year. Most analysts keep adjusting their price targets lower as the stock continues with its trend down with half keeping their Buy rating.
Analyst Sanjit Singh of Morgan Stanley has currently the highest performing score on HCP with 2/5 (40%) price target fulfillment ratio. His price targets carry on average an $13.69 (42.34%) potential upside and are fulfilled within average of 27 days.
Daily stock Analysts Top Price Moves Snapshot
June 9, 2023: Selected stock price target news of the day: June 9, 2023
By Matthew Otto
DocuSign's Q1 2024 Financials Outperform Projections
DocuSign posted revenue for the quarter of $661.4 million, exceeding both its guidance range ($639 million to $643 million) and the Street's consensus ($642 million). Billings for the period reached $674.8 million, outperforming the projected range of $615 million to $625 million.
Investors are likely to welcome the robust growth in billings. Allan Thygesen, CEO of DocuSign, stated that while there is more work to be done, he's optimistic about the company's progress in delivering smarter, easier, trusted agreements. He also emphasized the firm's rapid pace of product innovation and improved go-to-market execution, attributing much of their success to AI.
However, Thygesen remains wary of the macroeconomic outlook. While there's increased caution among enterprise customers, this is offset by the small business segment's strength. His guidance for the company does not anticipate any significant economic shifts.
For the next quarter ending July 31, 2023. DocuSign's revenue is expected to range between $675 million and $679 million, above the Street's forecast of $670 million. Projected billings range from $646 million to $656 million.
For FY 2024, the company raised its revenue outlook to between $2.713 billion and $2.725 billion. From the prior range of $2.695 billion to $2.707 billion, slightly above the Street's consensus of $2.7 billion. The new forecast for full-year billing is a range of $2.737 billion to $2.757 billion. Up from a previous forecast of $2.705 billion to $2.725 billion.
Moreover, DocuSign is making strides in adding new AI features to its contract management software, including software that creates summaries of documents for signees' understanding. By year-end, the firm will roll out new software to analyze trends and search across a company's corporate agreements, potentially across hundreds of thousands of contracts.
Financial Analysts Boost DocuSign's Price Targets Following Q1 Results
- Citi analyst Tyler Radke has raised his price target to $78.
- BofA Securities analyst Brad Sills has increased his price target to $72.
- UBS analyst Karl Keirstead has raised his price target to $48.
The stock price has been trading in a small range around $50 for the last year with analysts split in their opinion on its future prospect.
Analyst Mark Murphy of JP Morgan has currently the highest performing score on DOCU with 3/4 (75%) price target fulfillment ratio. His price targets carry on average an $21.93 (14.59%) potential upside and typically reach target within an average of 83 days.
Braze Beats Q1 Estimates, Provides Optimistic Guidance
Braze reported a 31.3% YoY increase in Q1 2024 revenue, amounting to $101.8 million. the increase is primarily from new customers, upsells, and renewals. Their net cash from operating activities stood at $22.5 million, and free cash flow at $21.7 million. Despite a GAAP operating loss of $41.9 million. Their non-GAAP net loss per share was $0.13, better than the predicted $0.18. Braze's customer base has expanded to 1,866, with 164 customers having an annual recurring revenue (ARR) of over $500,000.
For the second quarter of 2024, Braze anticipates an EPS of ($0.13)-($0.14). A revenue projection of $108-109 million, both figures surpassing consensus estimates. They also updated their FY2024 guidance. An expected EPS of ($0.51)-($0.55) and revenue of $442.5-446.5 million, exceeding the consensus revenue estimate.
Wall Street Action
- Piper Sandler analyst Brent Bracelin maintains an Overweight rating and raises the price target from $40 to $43.
- UBS analyst Taylor McGinnis lifts the price target to $38.
- Canaccord Genuity analyst David Hynes keeps a Buy rating and increases the price target to $42, up from $38.
All analysts that cover the stock are either bullish or Neutral at the moment.
Analyst Taylor Mcginnis of UBS has currently the highest performing score on BRZE with 1/2 (50%) price target fulfillment ratio. His price targets carry on average an $6.97 (17.90%) potential upside and typically reach target within an average of 17 days.
Ford and GM agree to use Tesla’s Supercharger network
Tesla announced that Ford and General Motors would utilize the Tesla Supercharger network for their electric vehicles. This decision places almost 70% of the U.S. electric vehicle (EV) market on Tesla's North American Charging Standard, creating pressure for other companies to transition from the currently dominant Combined Charging System (CCS) to Tesla's infrastructure.
Tesla's market value is projected to increase by over $30 billion to approximately $780 billion due to this development.
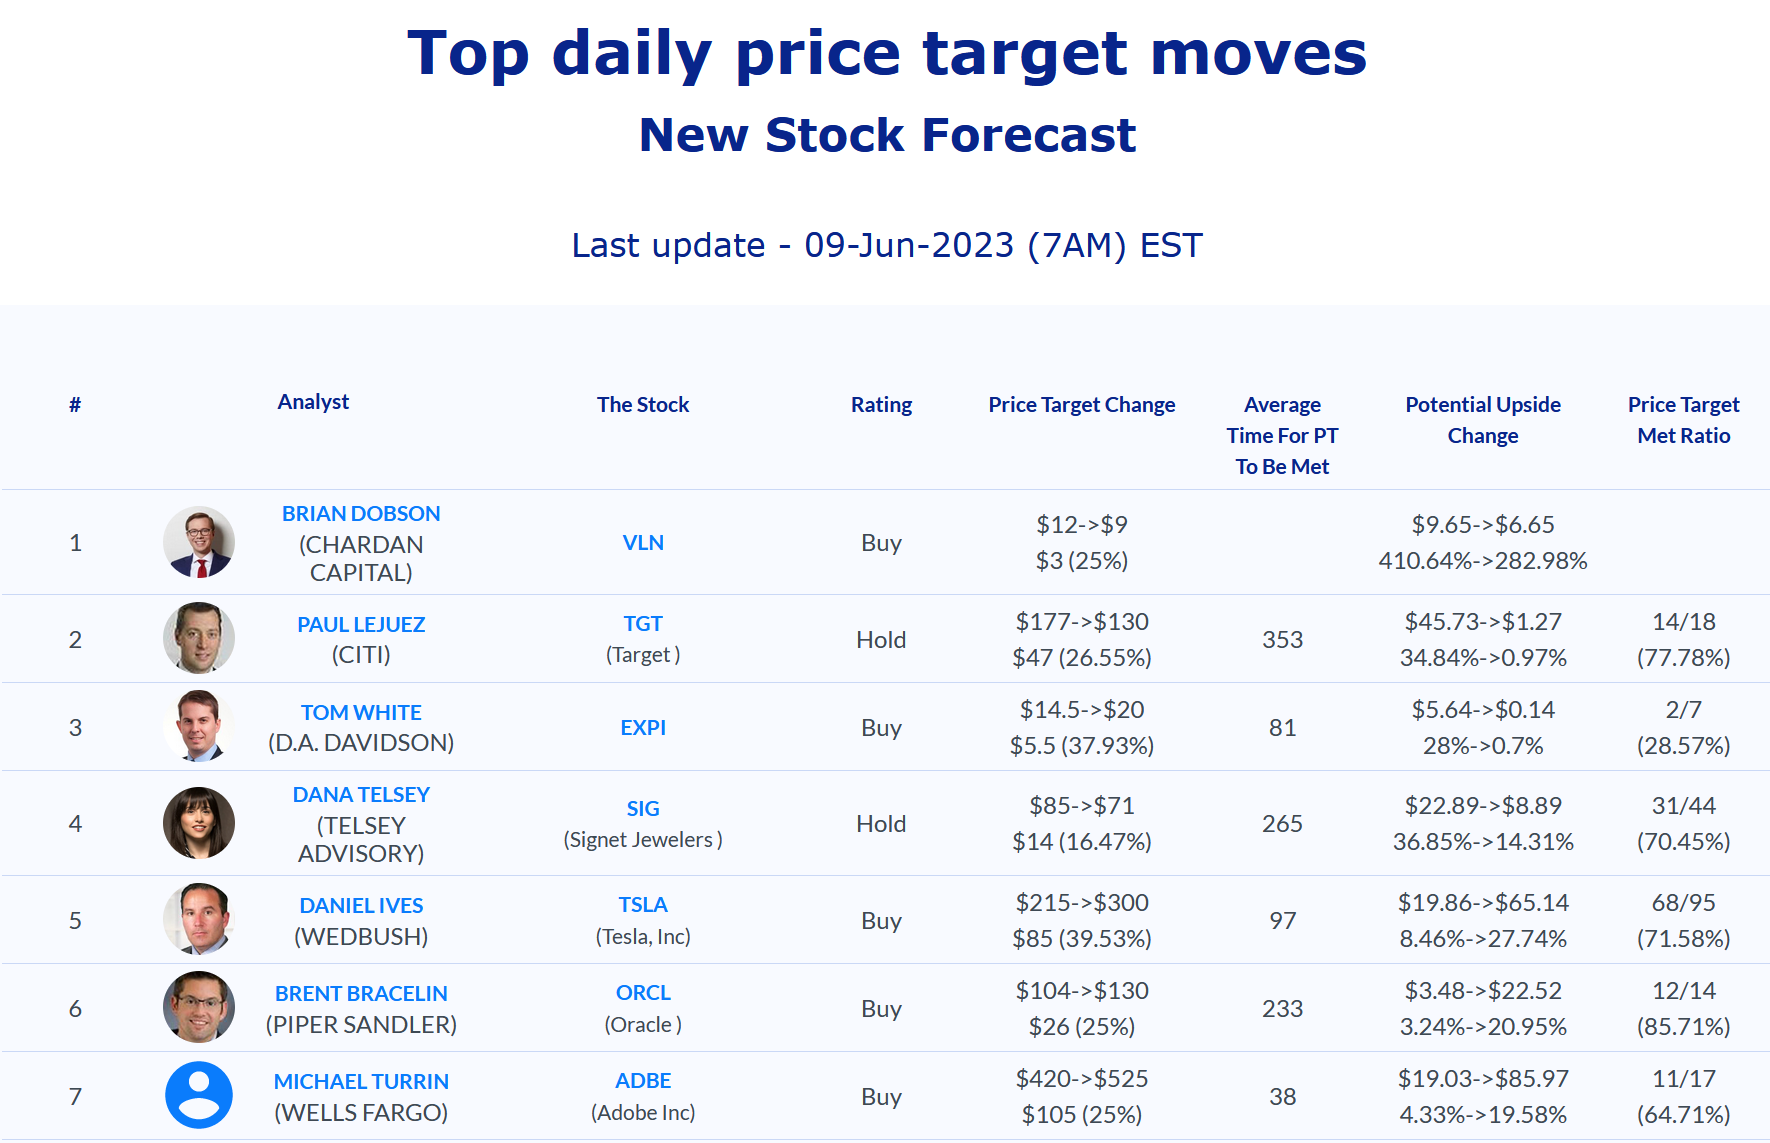
Wedbush Securities analyst Dan Ives predicted that the inclusion of Ford and GM could potentially add an extra $3 billion to Tesla's EV charging services revenue over the coming years. Consequently, they raised their price target on Tesla's shares to $300, approximately 30% higher than the last close.
The brokerage also indicated that the decision will help GM's ambition to expand charging access for its EV drivers through the Ultium Charge 360 initiative and mobile apps. Despite these moves, data from AutoForecast Solutions suggest that both Detroit automakers are expected to lag significantly behind market leaders Tesla and Volkswagen in the EV sector until at least 2028.
Analyst Dan Ives has a 68/95 (71.58%) price target fulfillment ratio on Tesla. His price targets carry on average an $44.1 (20.77%) potential upside and typically reach target within an average of 97 days.
Daily stock Analysts Top Price Moves Snapshot
June 12, 2023: Selected stock price target news of the day: June 12, 2023
By: Matthew Otto
NIO Reports Narrower-Than-Expected Loss in Q1, Boosts Investor Confidence
Chinese electric vehicle maker NIO reported a narrower-than-expected adjusted loss in its fiscal first quarter, which has provided some relief to investors. NIO's adjusted per share loss was 36 cents, with sales amounting to $1.6 billion. Analysts had anticipated a loss of 39 cents per share on sales of $1.7 billion. In the same period last year, the company reported a loss of 12 cents per share from $1.5 billion in sales.
Overall gross profit margins for the first quarter stood at 1.5%, down from 3.9% in the fourth quarter and significantly lower than the 14.6% reported a year ago. While the numbers were in line with analysts' expectations, they do not indicate substantial growth. Steven Wei Feng acknowledged the changing market environment and emphasized the need to analyze the competitive landscape promptly, strengthen competitive advantages, optimize cost structure, and improve operating efficiency.
Mizuho analyst Vijay Rakesh had anticipated a weak quarter, but the results were slightly better than expected. NIO projects delivering 10,000 to 12,000 vehicles in June, up from 6,155 vehicles delivered in May. This would bring second-quarter deliveries to approximately 23,000 to 25,000 units, down from 31,041 units delivered in the first quarter of 2023.
Over the past year, NIO's stock has declined by approximately 59% due to increased competition, falling EV prices, and slower sales growth, leading to diminished investor enthusiasm.
Analyst Reactions to NIO's Q1 Results: Price Targets Lowered but Overall Sentiment Remains Positive
- Mizuho analyst Vijay Rakesh maintains a Buy rating but lowers the price target from $25 to $20.
- Following NIO's Q1 results, analysts have revised their forecasts, expressing concerns.
- Citigroup analyst Jeff Chung maintains a Buy rating but reduces the price target from $13.4 to $11.5.
- JP Morgan analyst Nick Lai maintains a Neutral rating and lowers the price target from $10 to $8.5.
- BofA Securities analyst Ming Hsun Lee maintains a Buy rating but decreases the price target from $12 to $11.
- Jefferies analyst Xiaoyi Lei lowered the price target to HK$52.74.
- Nomura analyst Frank Fan downgraded from Buy to Neutral.
Analyst Nick Lai (JP Morgan) has currently the highest performing score on NIO with 4/8 (50%) price target fulfillment ratio. His price targets carry on average an $8.95 (25.00%) potential upside and typically reach target within an average of 15 days.
FDA Unanimously Backs Alzheimer's Drug Leqembi, Paving Way for Potential Approval Without Major Safety Warnings
The Alzheimer's drug, Leqembi,of Biogen has received unanimous support from the FDA's panel of advisors. This development increases the possibility of the drug receiving a traditional approval without major new safety warnings.
- Highly Significant Slowing of Cognitive and Functional Decline (27%, p=0.00005) compared to placebo over 18 months
- Significant Treatment Effects Observed for All Validated Secondary Endpoints
- Common Adverse Events: Infusion Reactions, ARIA-H, ARIA-E, Headache, and Fall
- Infusion Reactions Mostly Mild-to-Moderate (96% grade 1-2), Occurring on First Dose
- Results Presented at CTAD Conference and Published in The New England Journal of Medicine
Analyst Upgrades on Biogen (BIIB)
- Oppenheimer analyst Jay Olson maintains an Outperform rating and raises the price target from $350 to $360.
- Canaccord Genuity analyst Sumant Kulkarni keeps a Buy rating and raises the price target from $330 to $350.
- Needham analyst Ami Fadia reiterates a Buy rating and a price target of $321.
- HC Wainwright analyst Andrew Fein maintains a Buy rating and a price target of $325.
Analyst Brian Skorney (BAIRD) has currently the highest performing score on BIIBwith 13/17 (76.47%) price target fulfillment ratio. His price targets carry on average an $25.22 (9.40%) potential upside and typically reach target within an average of 201 days.
Adobe Introduces Subscription-Based Version of AI Tool Firefly
Adobe announced last week a series of new AI software tools and is introducing a pricing model to offset the computing time consumed by these tools. A notable feature is a website called Firefly, which offers tools for editing images in Photoshop and creating new images from text commands. Since its launch in March, beta users have generated over 200 million images.
To monetize these tools, Adobe recently unveiled Firefly for Enterprise, a subscription-based version targeting commercial customers. Adobe assures businesses that the AI-generated content is "commercially safe," and offers indemnification against potential trademark infringement for content created on Firefly's Enterprise version.
Adobe also plans to implement usage limits on the free version of Firefly and develop a subscription-based version for consumers. The company is integrating generative AI capability across its marketing software tools, leveraging multiple large language models, to assist brands in generating and modifying text-based experiences.
- Evercore ISI Group analyst Kirk Materne maintains an Outperform rating and raises the price target from $425 to $475.
- Jefferies analyst Brent Thill keeps a Buy rating and raises the price target from $440 to $530.
- Morgan Stanley analyst Keith Weiss reiterates an Equal-Weight rating and raises the price target from $385 to $470.
- Wolfe Research analyst Alex Zukin maintains an Outperform rating and raises the price target from $420 to $540.
Analyst Karl Keirstead (UBS) ) has the highest performing score on ADBE with 7/11 (63.64%)) price target fulfillment ratio. His price targets carry on average an $51.91 (10.75%) potential upside and typically reach target within an average of 116 days.
Daily stock Analysts Top Price Moves Snapshot

June 13, 2023: Selected stock price target news of the day: June 13, 2023
By Matthew Otto
Chinook Therapeutics' Zigakibart Shows Promising Phase 1/2 Trial Results in IgA Nephropathy Patients, gets purchased by Novartis
Swiss multinational pharmaceutical company Novartis has announced an agreement to acquire Chinook Therapeutics. Novartis will acquire the clinical-stage biopharmaceutical company for $3.2 billion upfront. The deal bolsters Novartis's innovative medicines strategy. It also expands its renal disease pipeline. Chinook's late-stage assets treat IgA nephropathy, a rare and severe chronic kidney disease. Both boards have approved the agreement, and the companies expect it to close in H2 2023, contingent on customary closing conditions.
Chinook Therapeutics also released an update involving Zigakibart (BION-1301),. The drug is currently in phase 2 clinical trials. IgA Nephropathy (IgAN) is a kidney disease that can lead to end-stage kidney failure.
Highlights from the release include:
- The ongoing phase 1/2 study of Zigakibart has shown promising results. In patients with IgAN, it demonstrated reductions in IgA and Gd-IgA1 levels, significant biomarkers in IgAN, which led to clinically meaningful proteinuria (excessive protein in the urine) reductions. The drug has been well-tolerated with no significant adverse effects or discontinuation of treatment due to adverse events.
- The drug demonstrated mean proteinuria reductions of 20% at 12 weeks, 39% at 24 weeks, 67% at 52 weeks, and sustained reduction up to 72% at 100 weeks of treatment.
- Updated interim results of the Zigakibart phase 1/2 trial will be presented at the 60th European Renal Association (ERA) Congress.
- Other presentations at the Congress will include data from phase 2 ASSIST and phase 3 BEYOND study designs, initial data from the phase 1 study of CHK-336 in healthy volunteers, and research on the impact of maladaptive tubular epithelial cells on chronic kidney disease progression.
- The investor conference call and webcast that was scheduled for June 16, 2023, has been canceled due to the pending acquisition of Chinook by Novartis AG.
Wall Street analysts adjust
- Stifel analyst Alex Thompson downgrades from Buy to Hold and reduces price target from $43 to $41.
- SVB Leerink analyst Joseph Schwartz shifts from Outperform to Market Perform, trims price target from $44 to $40.
- HC Wainwright analyst Ed Arce alters Chinook Therapeutics from Buy to Neutral, sets $40 price target.
- SVB MoffettNathanson downgrades to Market Perform.
- William Blair analyst Tim Lugo demotes to Market Perform.
Analyst Justin Kim (OPPENHEIMER) has currently the highest performing score on KDNY with 3/3 (100%) price target fulfillment ratio. His price targets carry on average an $10.21 (49.98%) potential upside and typically reach target within an average of 333 days.
Rexford Industrial Realty Faces Analyst Downgrades Despite Strong Q2 Leasing Activity
Rexford Industrial Realty has announced its leasing activity for Q2 2023. The company has executed 1.5 million square feet of new and renewal leases. Rental rates on these leases rose 94% on a net effective basis and 73% on a cash basis.
This signifies an acceleration compared to Q1 2023 and the full year 2022. Additionally, the company leased up 375,000 square feet of repositioning and redevelopment projects, achieving an average unlevered stabilized yield of 6.7%.
Wall Street Analysts adjust Lower
- Wells Fargo analyst Blaine Heck maintains an Overweight rating but has lowered the price target from $71 to $66.
- Citigroup analyst Emmanuel Korchman downgrades from Buy to Neutral, and lowers the price target from $66 to $53.
- BMO Capital's John Kim has also downgraded Rexford Industrial Realty from Outperform to Market Perform, lowering the price target from $69 to $56.
Analyst Blaine Heck (WELLS FARGO) has currently the highest performing score on REXR with 6/10 (60%) price target fulfillment ratio. His price targets carry on average an $8.53 (14.00%) potential upside. The analyst price targetstypically reach target within an average of 68 days.
Daily stock Analysts Top Price Moves Snapshot

June 14, 2023: Selected stock price target news of the day: June 14, 2023
By Matthew Otto
Oracle Grows on revenue, beats expectations.
Oracle released its fiscal fourth-quarter results for the period ending May 31, 2023. The tech giant announced revenue of $13.8 billion, marking a 17% growth year-over-year or 18% in constant currency terms. This financial performance fell squarely within Oracle's projected growth range, with non-GAAP profit surpassing Wall Street's consensus at $1.67 per share.
The results are largely attributed to the company's burgeoning cloud division, which experienced a whopping 54% growth in revenue. This exceeded analysts' predictions, which had pegged the likely growth around 50%.
Over the full fiscal year, Oracle reached a milestone with an all-time high of $50 billion in revenue. This marks an 18% increase as reported or 22% in constant currency. Specific divisions of Oracle have performed notably well, with its cloud-infrastructure business seeing a 76% growth in revenue for the quarter, while cloud applications revenue went up 45%.
In recent months, Oracle has aligned with more than 30 AI development companies, which have committed to purchase over $2 billion of capacity in Oracle’s Gen 2 cloud. Among these partnerships, the company's collaboration with AI software company Cohere stands out, offering customers the ability to build their own models while protecting their data.
Outlook is within Wall Street expectations
Looking forward, Oracle projects an 8% to 10% increase in revenues for the fiscal first quarter ending in August. The company anticipates a profit of $1.12 to $1.16 per share for the quarter, which aligns with Wall Street's estimate of $1.14 per share.
Oracle CEO, Safra Catz, painted a rosy picture of fiscal 2024, predicting "unprecedented cloud demand." Despite the increasingly higher base, Catz expects the growth rate of cloud demand to match or even exceed the rate witnessed in 2023.
The tech company remains steadfast in its previous forecast of achieving $65 billion in sales by 2026. The increasing demand for AI is seen as a significant growth factor in the company's future.
Oracle's consistent growth and positive future outlook have been met with enthusiasm from the market. The company's shares have rallied over recent weeks, resulting in a market valuation that exceeds $300 billion.
Erica Schultz, an insider at Confluent, recently offloaded shares of the company. According to the transaction dated June 13, 2023, Schultz sold a significant portion of her Confluent holdings, amounting to a total of $1,808,500.00.
Wall Street Action
- Morgan Stanley analyst Keith Weiss maintains an Equal-Weight, raising the price target from $90 to $105.
- Goldman Sachs analyst Kash Rangan maintains a Neutral, lifting the price target from $75 to $120.
- Evercore ISI Group analyst Kirk Materne maintains an In-Line, increasing the price target from $110 to $125.
- JP Morgan analyst Mark Murphy maintains an Overweight, with a price target rise from $109 to $112.
- DA Davidson analyst Gil Luria keeps a Neutral, pushing the price target up from $85 to $115.
- TD Cowen analyst J. Derrick Wood maintains an Outperform, raising the price target from $117 to $137.
- Stifel analyst Brad Reback keeps a Hold, increasing the price target from $84 to $120.
- B of A Securities analyst Brad Sills maintains a Neutral, with the price target going up from $112 to $132.
- Mizuho analyst Siti Panigrahi maintains a Buy, raising the price target from $116 to $150.
- Citigroup analyst Tyler Radke keeps a Neutral, boosting the price target from $106 to $121.
- Wolfe Research analyst Alex Zukin maintains an Outperform, raising the price target from $130 to $140.
- Deutsche Bank analyst Brad Zelnick maintains a Buy, with a price target increase from $120 to $135.
- Barclays analyst Raimo Lenschow keeps an Equal-Weight, raising the price target from $113 to $126.
- Jefferies analyst Brent Thill maintains a Buy, boosting the price target from $125 to $135.
- Bernstein analyst Mark Moerdler maintains an Outperform and raised the price target to $142 from $120.
Opinions on the stock forecast remain varied regardless of the last report.
Analyst Brent Bracelin (PIPER SANDLER) has the highest current performing score on ORCL with 12/15 (80%) price target fulfillment ratio. His price targets carry on average an $5.33 (8.65%) potential upside and are fulfilled within average of 233 days.
Confluent sees insider holding offload while WallStreet upgrades its outlook
Erica Schultz, an insider at Confluent, offloaded shares of the company. According to the transaction dated June 13, 2023, Schultz sold a significant portion of her Confluent holdings, amounting to a total of $1,808,500.
Confluent Director Jonathan Chadwick also sells $605,150 of his share in the firms
Wall Street Action
- Guggenheim analyst Howard Ma downgraded from Buy to Neutral.
- Wells Fargo analyst Michael Turrin maintains an Overweight rating and raised the price target from $35 to $41.
- Mizuho analyst Gregg Moskowitz maintains a Buy rating and raised the price target from $28 to $40.
- Barclays analyst Raimo Lenschow maintains an Overweight rating and raised the price target from $26 to $42.
- Needham analyst Mike Cikos reiterated a Buy rating and maintains a $45 price target.
- UBS analyst Karl Keirstead maintained a Neutral rating and raised the price target to $39, up from $24.
- JP Morgan analyst Pinjalim Bora raised Confluent's price target to $31.
- TD Cowen analyst J. Derrick raised the Confluent price target to $40.
- JMP Securities analyst Patrick Walravens raised the price target for Confluent to $41.
Analyst Raimo Lenschow (BARCLAYS) has currently the highest performing score on CFLT with 10/11 (90.91%) price target fulfillment ratio. His price targets carry on average an $2.52 (11.54%) potential upside and are fulfilled within average of 43 days.
Amazon Web Services Considering Using AMD's New AI Chips
Advanced Micro Devices has announced yesterday that its highly anticipated GPU (graphics processing unit) for artificial intelligence, the MI300X, will start shipping to some customers later this year. This new development is seen as a significant challenge to Nvidia, which currently holds over 80% of the market share in AI chips.
The MI300X and its CDNA architecture are specially designed for large language models and other advanced AI models. The MI300X has a memory capacity of up to 192GB, significantly larger than Nvidia's H100, which supports only 120GB of memory. This increased memory size allows the handling of larger AI models, potentially reducing the need for multiple GPUs.
AMD has also developed an Infinity Architecture that allows the combination of eight M1300X accelerators into one system, similar to solutions offered by Nvidia and Google. However, AMD may need to overcome developers' preference for Nvidia chips, which have a well-developed software package called CUDA. AMD has stated it has its own software for its AI chips, known as ROCm.
CEO Lisa Su referred to AI as AMD's "largest and most strategic long-term growth opportunity," forecasting a rise in the data center AI accelerator market from $30 billion this year to over $150 billion by 2027. The move to ship MI300X later this year could potentially put pricing pressure on Nvidia's GPUs, thereby driving down costs in generative AI applications.
Amazon might be the big ticket
Today, Amazon Web Services (AWS) was reported to be contemplating using new artificial intelligence chips from Advanced Micro Devices Inc (AMD), according to an AWS executive. However, a final decision has not yet been made.
AMD presented its AI strategy at an event where they are looking to challenge the dominance of Nvidia in the AI market. AMD CEO Lisa Su explained their approach to winning significant cloud computing customers by offering all the components needed to construct the kind of systems to power services similar to ChatGPT, but allowing customers to select what they need, using industry-standard connections.
While AWS hasn't made any public commitment to use AMD's new MI300 chips in its cloud services, Dave Brown, vice president of elastic compute cloud at Amazon, stated AWS is evaluating them.
Wall Street Action
- Aaron Rakers, an analyst at Wells Fargo, keeps an Overweight rating, elevating the price target from $120 to $150.
- Vijay Rakesh, an analyst at Mizuho, also upholds a Buy rating and escalates the price target from $90 to $140.
- Blayne Curtis, an analyst at Barclays, sustains an Overweight rating, hiking the price target from $90 to $145.
- Matt Bryson, an analyst at Wedbush, reaffirms an Outperform rating and preserves a $145 price target.
- Ross Seymore, an analyst at Deutsche Bank, boosted the price target to $110.
- Christian Schwab, an analyst at Craig-Hallum, upgraded the price target to $158.
- Ambrish Srivastava, an analyst at BMO Capital, uplifted the price target to $150.
Analyst Christopher Danely (CITI) has currently the highest performing score on AMD with 6/8 (75%) price target fulfillment ratio. His price targets carry on average an $-4.77 (-2.24%)
potential downside and are fulfilled within an average of ten days.
Daily stock Analysts Top Price Moves Snapshot

June 15, 2023: Selected stock price target news of the day: June 15, 2023
By Matthew Otto
Lennar Beats Q2 Estimates and Wall Street Expectations Amid Housing Market Recovery
Lennar announced strong financial results for its second quarter ended May 31, 2023. The company posted net earnings per diluted share of $3.01 and total revenue of $8 billion. These figures surpassed Wall Street's expectations, which had predicted earnings per share of $2.33 and revenue of $7.2 billion, according to FactSet.
In addition to exceeding earnings estimates, Lennar also surpassed expectations for orders and deliveries during the typically strong spring season. The company reported 17,885 new orders and delivered 17,074 homes in the second quarter.
Furthermore, the company also provided optimistic guidance for the upcoming third quarter, projecting home deliveries to range from 17,750 to 18,250, which was above analysts' expectations.
The results captured an unusual spring selling season marked by the fallout of the Federal Reserve's aggressive interest rate hikes in 2022. Despite these adjustments, prospective buyers seemed to have accepted a "new normal" of higher rates and demand has accelerated.
With the housing market recovering, the company’s average sales price per home delivered declined to $449,000, but its deliveries and new orders were both up compared with the year prior. This was largely due to the company's strategic pricing adjustments and incentives offerings.
Wedbush adjusts price targets higher
Wedbush analyst Jay McCanless keeps a Neutral but raises the price target from $94 to $123.
McCanless got burned during the stock fall in 2022 from $112 to $68 after which he turned more conservative and as a result missed the recovery after.
Analyst Nishu Sood (DEUTSCHE BANK) has currently the highest performing score on LEN with 13/14 (92.86%) price target fulfillment ratio. "On average, his price targets offer a potential upside of $4.33 (11.13%) and typically reach fulfillment within 181 days.
Citigroup Prepares to Absorb Severance Costs from 1,600 Job Cuts in Q2
Citigroup has announced that it will incur severance costs related to approximately 1,600 job cuts in the second quarter of 2023, according to Chief Financial Officer Mark Mason. Speaking at a conference in New York on Wednesday, Mason indicated that the bank's expenses for Q2 will be between $300 million and $400 million higher than those of Q1 due to these restructuring and repositioning charges.
Since the start of 2023, Citigroup has faced costs from a company-wide reduction of 5,000 positions, predominantly affecting the banking, markets, and functions departments. While not all of these individuals have left the firm, the majority have been informed of the impending changes.
Several of the cuts are coming from units that Citigroup has decided to divest. However, the exact number was not disclosed. To date, Citigroup has withdrawn from seven of the 14 markets from which it plans to divest. Following unsuccessful attempts to sell its Mexican unit, the bank has now opted to spin off this division in 2024, with plans to list it in 2025.
Mason also cautioned investors about a potential decline in investment banking and trading revenues. Market revenues have fallen by 20% so far this quarter compared to the same period in 2022. In investment banking, revenues are projected to be down 25% year over year. Mason admitted, "It's been tough to call exactly when the wallet will rebound. " but noted there have been "green shoots" in debt capital markets activity.
Morgan Stanley remains pessimistic
Morgan Stanley analyst Betsy Graseck keeps an Underweight rating and a $45 price target. The analyst turned bearish on her fellow bank in April last year which proved to be a correct move.
Graseck has currently the highest performing score on C with 4/7 (57.14%) price target fulfillment ratio. On average, her price targets offer a potential upside of $3.5 (5.90%) and typically reach fulfillment within 13 days.
T-Mobile Partners with Google Cloud to Leverage 5G
T-Mobile is set to connect its 5G Advanced Network Solutions (ANS) suite, which includes public, private, and hybrid 5G networks, with Google Distributed Cloud Edge (GDC Edge). This combination will support the creation of next-generation 5G applications and use cases, including augmented reality and virtual reality experiences.
As digital transformation becomes a priority, more companies are turning to edge computing. The global edge computer market size is projected to increase by 37.9% to reach $155.9 billion by 2030. Combining edge computing with 5G's low latency, high speeds, and reliability could unlock significant use cases in various sectors, such as retail, manufacturing, logistics, and smart cities.
T-Mobile and Google Cloud's partnership is targeting enterprises and government organizations. The main focus will be enhanced capability offering of control and monitoring using IoT (Internet of Things).
To showcase the potential of 5G ANS and GDC Edge in retail. T-Mobile has developed a proof of concept at its Tech Experience 5G Hub – the "magic mirror" – supported by Google Cloud. This interactive display uses cloud-based processing and image rendering at the edge to bring retail products to life interactively.
Morgan Stanley slightly adjusts higher
Morgan Stanley analyst Simon Flannery maintains an Overweight rating and lifts the price target from $177 to $178.
Analyst Brandon Nispel (KEYBANK) has currently the highest performing score on TMUS with 9/16 (56.25%) price target fulfillment ratio. On average, his price targets present a potential upside of $16.22 (16.31%) and usually achieve fulfillment within 149 days
Daily stock Analysts Top Price Moves Snapshot

June 16, 2023: Selected stock price target news of the day: June 16, 2023
By Matthew Otto
Kroger Shares Fall Despite Beating Q1 Estimates; Analysts Give Mixed Reviews on Performance and Outlook
Kroger, the supermarket chain, has maintained its annual forecasts despite surpassing Wall Street estimates for first-quarter profit and same-store sales. This is a result of consistent demand for essentials and easing supply chain costs.
However, this conservative outlook led to a 4.5% drop in the company's shares to $45.07, as investors were expecting an upgraded forecast. Telsey Advisory Group analyst, Joseph Feldman, noted that the market hoped Kroger would have shown stronger performance given the robust grocery sales at its competitors. Last month, Walmart, for instance, raised its annual forecasts as more Americans shopped for its lower-priced groceries and essentials.
Rodney McMullen, Kroger's CEO, attributed the decision not to upgrade the forecast to the economic environment, which is significantly impacting its budget-conscious shoppers. McMullen pointed out that the least loyal customers were primarily focusing on the price at the shelf, over personalized offers, convenience, and quality.
In the first quarter, Kroger, which plans to acquire its smaller competitor Albertsons in a $25 billion deal, saw a 1.3% increase in net sales to $45.17 billion. However, this was slightly below the estimated $45.24 billion.
Despite not reaching top and bottom-line estimates this quarter. Kroger's gross margins increased by 21 basis points, benefiting from lower supply chain costs and sourcing some products closer to its distribution centers. The company also profited from shoppers, including those with higher incomes seeking economical options amidst ongoing inflation, who preferred its store-label brands over more expensive national brands.
Wall Street Action
- Morgan Stanley analyst Simeon Gutman has maintained an Equal-Weight ratingand lowered the price target from $49 to $48.
- Telsey Advisory Group analyst Joseph Feldman has reiterated an Outperform rating on Kroger, maintaining a $55 price target.
- Evercore ISI analyst Michael Montani has lowered the price target to $54.
- Roth/MKM analyst Bill Kirk has lowered the price target to $48.
- UBS analyst Michael Lasser has lowered the price target to $48.
Analyst Scott Mushkin (R5 CAPITAL) has currently the highest performing score on KR with 1/2 (50%) price target fulfillment ratio. His price targets carry on average an $-0.59 (1.97%) potential downside and typically reach target within an average of 53 days.
Jabil Exceeds Q3 Expectations, Raises Outlook for FY 2023 Amid Strong Performance
Jabil reported Q3 EPS (Earnings Per Share) of $1.99, surpassing the analyst estimate of $1.88. This better-than-expected EPS performance suggests that Jabil's profitability was higher than what analysts predicted, adding to the company's positive earnings surprise.
Furthermore, Jabil's Q3 revenue was $8.5 billion, which also outpaced the consensus estimate of $8.19 billion. This indicates that the company's sales performance was stronger than what was forecasted by the market analysts.
Looking ahead, Jabil's guidance for Q4 2023 is projecting an EPS of between $2.14 and $2.50, in comparison to the consensus estimate of $2.30. Also, Jabil expects Q4 2023 revenue of $8.2 to $8.8 billion, compared to the consensus estimate of $8.57 billion. It will be interesting to watch whether Jabil can continue to outperform market expectations in the next quarter.
Wall Street Action
- Credit Suisse analyst Shannon Cross keeps Jabil with an Outperform rating and lifts the price target from $110 to $125.
- Raymond James analyst Melissa Fairbanks maintains Jabil with a Strong Buy rating and raises the price target from $100 to $120.
- Stifel analyst Matthew Sheerin raised Jabil's price target to $115.
- BofA Securities analyst Ruplu Bhattacharya raised the price target for Jabil to $108.
Analyst Mark Delaney (GOLDMAN) has currently the highest performing score on JBL with 14/14 (100%) price target fulfillment ratio. His price targets carry on average an $3.27 (7.23%) potential upside and typically reach target within an average of 89 days.
American Express gets Warning From Citi of Slowing Credit Card Spending
Citigroup warned about decelerating American Express credit card spending trends. The downward movement came as Citigroup initiated a negative catalyst watch on the credit card company, citing a sharper than expected slowdown in travel and entertainment categories.
Analysts Maintain Cautious Outlook on American Express Amid Slowing Spending Trends
- Citigroup analyst Arren Cyganovich has maintained a Sell rating on American Express and lowered the price target from $150 to $148.
- Stephens & Co. analyst Vincent Caintic has reiterated an Underweight rating on American Express and maintained a $146 price target.
Analyst Moshe Orenbuch (CREDIT SUISSE) has currently the highest performing score on AXP with 22/24 (91.67%) price target fulfillment ratio. His price targets carry on average an $-0.38 (5.45%) potential downside and typically reach target within an average of 169 days.
Daily stock Analysts Top Price Moves Snapshot
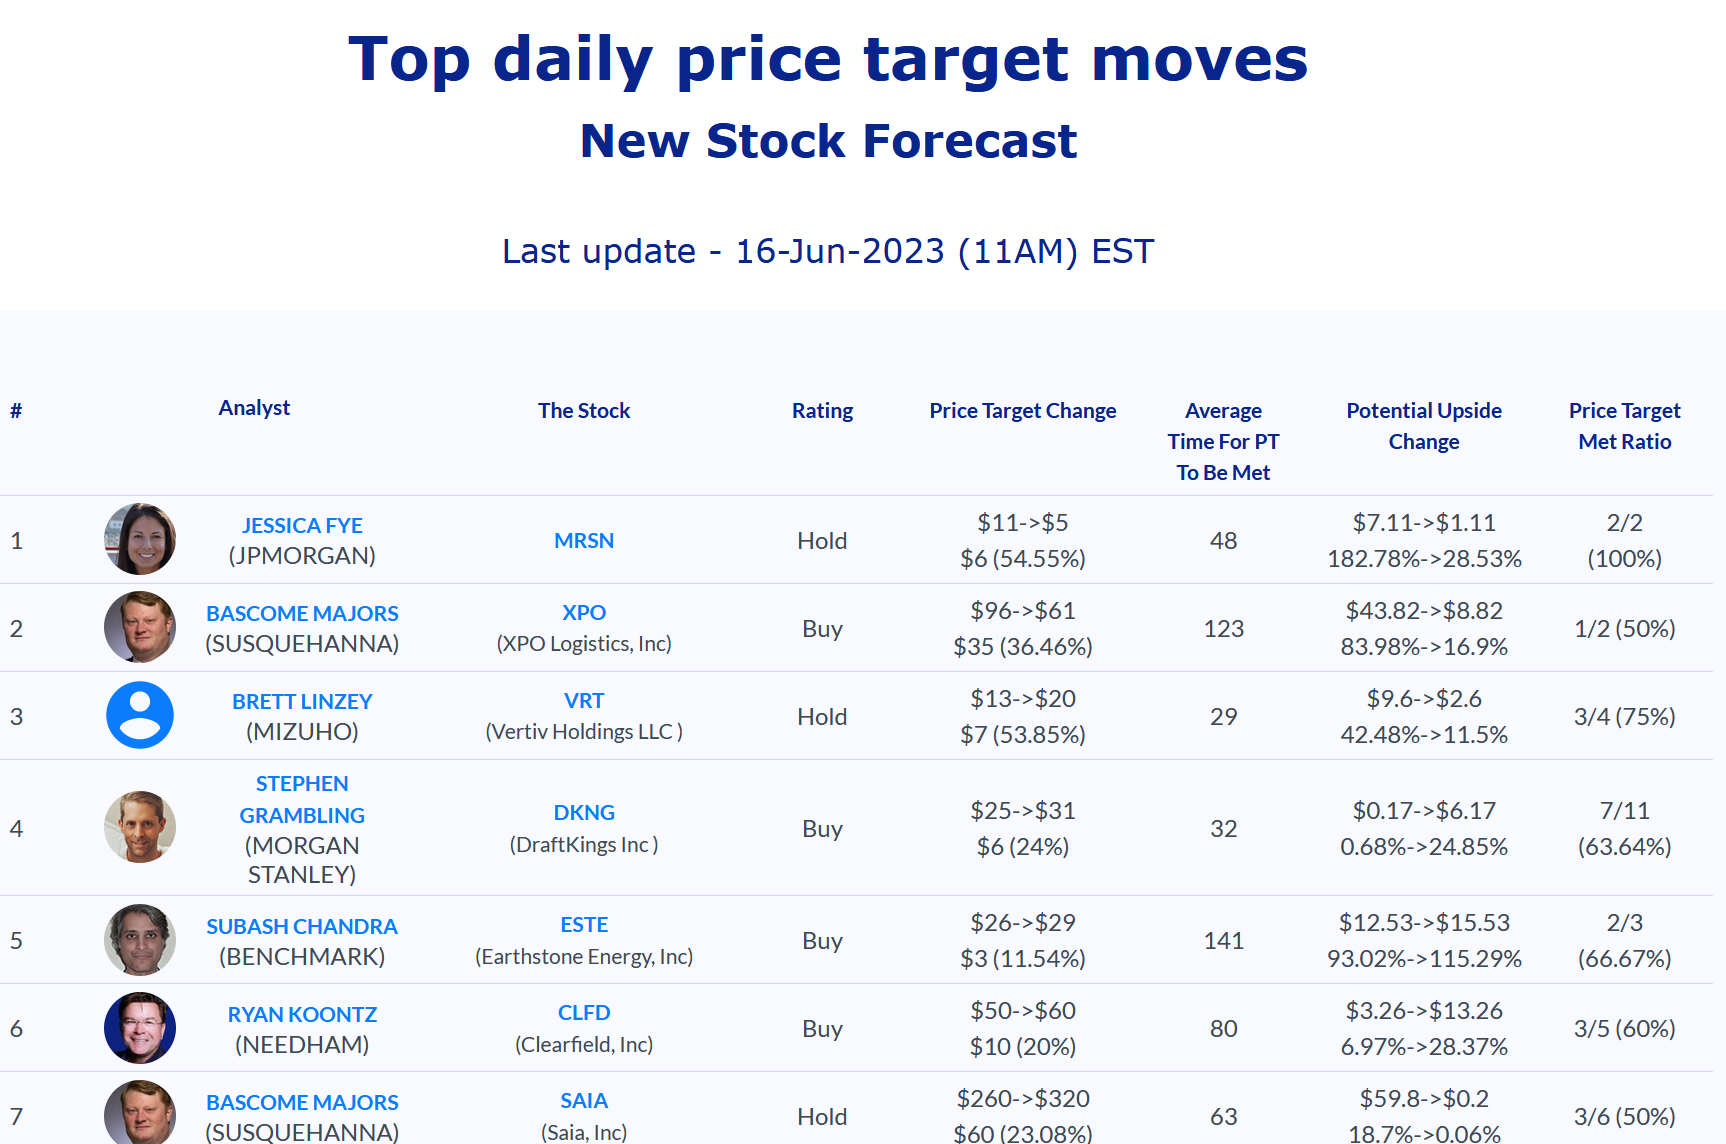
June 20, 2023: Selected stock price target news of the day: June 20, 2023
By Matthew Otto
Arcellx's CART-ddBCMA Drug Faces Clinical Hold by FDA
Arcellx has announced that it received notification from the U.S. Food and Drug Administration (FDA). The notification concerned a clinical hold on its CART-ddBCMA investigational new drug (IND) for the treatment of patients with relapsed or refractory multiple myeloma (rrMM). The FDA issued the clinical hold on June 16 following a patient death. The company believes that limitations on bridging therapy may have played a role. It is working with the FDA to amend the protocol, providing more options for patients in line with current clinical practices.
Rami Elghandour, Chairman and CEO of Arcellx, stated that patients safety is their top priority. The company is collaborating with investigators, the data safety monitoring board (DSMB), and their partners at Kite Pharma to address the clinical hold. They are seeking to expand the bridging therapy regimens to align with what is currently available in clinical practice, aiming to benefit patients. Arcellx is also considering other potential improvements to the study. Despite the clinical hold, they remain confident in the potential of CART-ddBCMA as a leading therapy for rrMM. That confidence is based on the positive clinical profile observed in patients treated thus far across their studies.
Analysts Reiterate Positive Outlook on Arcellx with Price Target Increases
- Needham analyst Gil Blum maintains a Buy rating and keeps the price target at $51.
- H.C. Wainwright analyst Emily Bodnar raises the price target to $49.
- Barclays analyst Carter Gould also raises the price target to $49.
- Truist Securities analyst Asthika Goonewardene lowered the price target to $57.
- Baird analyst Jack Allen lowered the price target to $40.
Analyst John Newman (CANACCORD) has currently the highest performing score on ACLX with 3/3 (100%)price target fulfillment ratio. His price targets carry on average an $7.31 (30.10%) potential upside and typically reach target within an average of 93 days
Coherent Introduces PowerLine PS 30 Picosecond Laser Markers
Coherent has introduced the PowerLine PS 30 picosecond laser markers. They are specially designed for corrosion-resistant black marking and precision micromachining in the medical device manufacturing sector. The demand for efficient, reliable, and cost-effective laser technology for black marking on medical devices is on the rise. This technology remains unaffected by passivation and autoclave cycling. The PowerLine PS 30 offers high average power, enabling rapid black marking and micromachining. That results in improved production throughput and cost-effectiveness, while maintaining a high level of reliability.
Dr. Alexander Roth, Vice President and Managing Director of the Laser Systems Business Unit at Coherent, emphasized the criticality of traceability in medical device manufacturing. Black marking must meet strict requirements for readability and durability. Laser technology facilitates production scaling with high quality, particularly during rapid volume growth. The PowerLine PS 30 ensures a quick return on investment, easy integration, and user-friendly operation, maximizing labor efficiency.
Analysts' Ratings and Price Targets for Coherent Receives Positive Outlook
- Needham Analyst James Ricchiuti maintained a Buy rating and with a Raised Price Target of $64 from $33.
- Ruben Roy from Stifel Nicolaus maintains a Buy rating and has a price target of $42.
- Meta Marshall from Morgan Stanley maintains a Buy rating and has a price target of $48.
Analyst Ruben Roy (STIFEL) has currently the highest performing score on COHR with 2/2 (100%) price target fulfillment ratio. His price targets carry on average an $11.54 (35.56%) potential upside and typically reach target within an average of 114 days.
Philip Morris to Launch $30 Million Production Facility in Western Ukraine
Philip Morris has announced its plans to launch a new $30 million production facility in the Lviv region of western Ukraine. The facility is set to open in the first quarter of next year. The facility should create 250 jobs, providing employment opportunities in the region.
Maksym Barabash, the Chief Executive Officer of Philip Morris Ukraine, expressed their commitment to Ukraine as a long-term economic partner with this investment. Barabash stated, "We are not waiting for the end of the war - we are investing now." That statement emphasized their dedication to supporting Ukraine's economy despite the ongoing conflict.
Analysts Raise Price Targets and Upgrade Philip Morris
- Citigroup analyst Simon Hales upgrades from Neutral to Buy and raises the price target from $109 to $117.
- Goldman Sachs analyst Bonnie Herzog increases the price target $95.00 to $120.
- Cowen analyst Vivien Azer raised the price target on Philip Morris to $120 from $115.
Analyst Vivien Azer (COWEN) has currently the highest performing score on PM with 13/19 (68.42%) price target fulfillment ratio. Her price targets carry on average an $27.98 (40.69%) potential upside and typically reach target within an average of 1086 days.
Daily stock Analysts Top Price Moves Snapshot
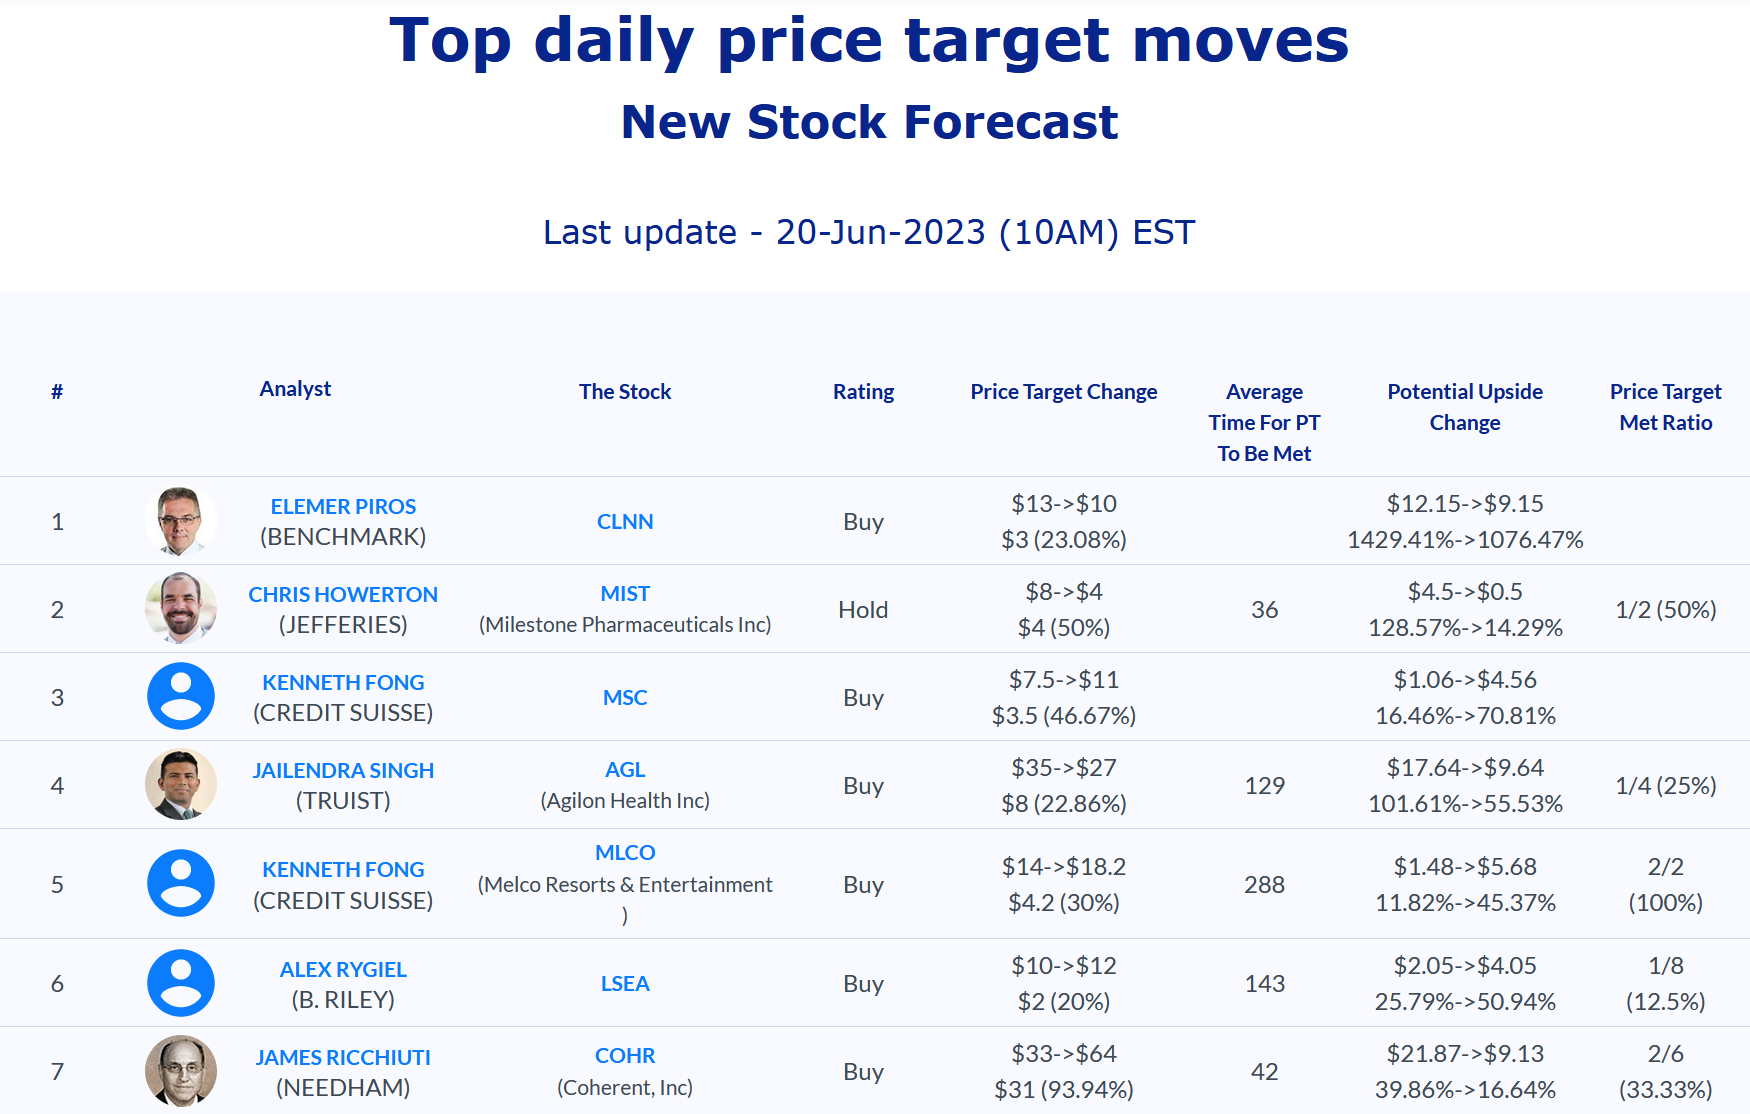
June 21, 2023: Selected stock price target news of the day: June 21, 2023
By Matthew Otto
Rivian to Use Electric Vehicle Tesla’s Charging Infrastructure
Rivian Automotive has recently revealed a new agreement with Tesla, signaling a collaboration to enhance the charging infrastructure for electric vehicles. Under this agreement, Rivian drivers will gain access to Tesla's Supercharger network across the United States and Canada, complementing Rivian's own charging network known as the Rivian Adventure Network. The agreement will provide Rivian drivers access to Tesla's Supercharger network marks an important step in expanding the charging infrastructure for electric vehicles. By joining forces, these companies aim to facilitate the adoption of electric vehicles and contribute to the mission of decarbonizing transportation.
Analysts Reiterate Buy Ratings for Rivian Automotive with Varying Price Targets
- Canaccord Genuity analyst George Gianarikas reiterates a Buy rating and a $40 price target.
- Truist Securities analyst Jordan Levy remains in a Buy rating and maintains a $28 price target.
- Vijay Rakesh from Mizuho Securities maintained a Buy rating with a price target of $27.
Analyst Mark Delaney (GOLDMAN SACHS) has currently the highest performing score on RIVN with 3/5 (60%) price target fulfillment ratio. His price targets carry on an average of $-6.8 (4.77%) potential downside and typically reach target within an average of 14 days.
Civitas Resources to Acquire Permian Basin Oil and Gas Operations
Civitas Resources has announced its plan to acquire oil and gas operations in the Permian basin managed by NGP Energy Capital Management, a private equity firm. The acquisition will be made for a total of $4.7 billion. This move signifies a significant expansion for Civitas, which has previously operated exclusively in Colorado's Denver-Julesburg basin.
Civitas Resources Receives Positive Analyst Ratings
- Roth MKM analyst Leo Mariani reiterates Buy rating and maintains a $74 price target.
- Truist analyst Neal Dingmann maintains a Buy rating and sets a price target of $91.
Analyst Leo Mariani (MKM) has currently the highest performing score on CIVI with 8/9 (88.89%) price target fulfillment ratio. His price targets carry on an average of $10.66 (22.02%) potential upside and typically reach target within an average of 168 days.
FedEx Reports Better-than-Expected Q4 Earnings Amid Cost-Cutting Initiatives
FedEx reported better-than-expected adjusted fiscal Q4 earnings per share of $4.94, on sales of $21.9 billion, compared to Wall Street predictions of $4.85 EPS from sales of $22.5 billion. However, these results didn't meet investors' expectations, leading to a decline in FedEx stock in after-hours trading.
The company observed a 10% YoY decrease in daily package volumes in the Express business, and a 14% YoY drop in average daily freight pounds shipped. Despite these figures, FedEx is optimistic about the coming fiscal year, expecting earnings between $16.50 and $18.50 a share, up from nearly $15 a share earned in fiscal year 2023. This forecast, however, falls short of Wall Street's expected $18.30 a share.
FedEx CEO, Raj Subramaniam, stated that the company is making significant progress in its global transformation efforts. It has become a more adaptable, efficient, and data-driven organization, despite the dynamic demand environment, a phrase often used to describe recessionary periods.
FedEx is also undergoing a restructuring effort known as DRIVE, initiated late in 2022. The program aims to consolidate the Express and Ground networks, reduce costs by eliminating route overlaps, and improve profitability. By the end of fiscal 2025, FedEx is targeting about $4 billion in profit-margin improvements through the DRIVE initiative.
In fiscal year 2023, DRIVE contributed to $1.8 billion in gains while other factors presented a $1 billion profit headwind. Full-year operating profit came in at $6.2 billion, up from $5.4 billion in fiscal year 2022. Despite the improved results, the company expects business conditions to remain uncertain in the coming period.
Analysts Adjust FedEx Price Targets Amid Economic Uncertainty Despite Earnings Beat
- Stifel analyst J. Bruce Chan keeps a Buy rating and lowers the price target from $264 to $259.
- JP Morgan analyst Brian Ossenbeck maintains a Neutral rating and raises the price target from $228 to $251.
- Morgan Stanley analyst Ravi Shanker reiterates an Equal-Weight rating and raises the price target from $180 to $186.
- Stephens & Co. analyst Jack Atkins keeps an Overweight rating and a $290 price target.
- Raymond James analyst Patrick Tyler Brown maintains an Outperform rating but lowers the price target from $280 to $270.
- Wolfe Research analyst Scott Group has lowered the price target to $284.
- Bernstein analyst David Vernon has raised the price target to $284.
Analyst Fadi Chamoun (BMO) has currently the highest performing score on FDX with 13/18 (72.22%) price target fulfillment ratio. His price targets carry on an average of $37.21 (21.08%) potential upside and typically reach target within an average of 307 days.
Daily stock Analysts Top Price Moves Snapshot

June 22, 2023: Selected stock price target news of the day: June 22, 2023
By Matthew Otto
Accenture Lowers Revenue Growth Outlook for Fiscal Year
Accenture lowered its revenue growth outlook for the fiscal year. The HR firm now expects revenue growth in the range of 8% to 9% for fiscal 2023. Compared to its previous expectation of 8% to 10% growth.
In the fiscal third quarter, Accenture reported adjusted earnings of $3.19 per share on revenue of $16.56 billion. This exceeded analysts' expectations, as they were anticipating earnings of $3.01 per share on revenue of $16.49 billion.
Despite the lowered revenue growth outlook, Accenture's CEO, Julie Sweet. Expressed satisfaction with the company's solid performance in terms of bookings. Revenue, adjusted operating margin, earnings per share, and free cash flow in the third quarter.
Before the decline, Accenture's stock had experienced a 17% increase in value during the year.
Analysts Provide Mixed Recommendations and Price Targets for Accenture
- BMO Capital analyst Keith Bachman maintains a Market Perform rating and increases the price target from $327 to $365.
- Piper Sandler analyst Arvind Ramnani upgrades from Underweight to Neutral and raises the price target from $250 to $316.
- Citigroup analyst Ashwin Shirvaikar maintains a Buy recommendation and raises the price target from $306 to $358.
Analyst Jeff Cantwell (WELLS FARGO) has currently the highest performing score on ACN with 2/2 (100%) price target fulfillment ratio. His price targets carry on an average of $19.41 (7.14%) potential upside and are fulfilled within an average of 33 days.
Boeing's Approval for MAX 10 Hinges on Certification of MAX 7 by FAA
Boeing is awaiting approval from the Federal Aviation Administration (FAA) for its smaller MAX 7 aircraft before it can secure approval for the MAX 10 variant. The certification process for both models has faced significant delays, partly due to heightened regulatory scrutiny following the fatal crashes involving the MAX 8 in 2018 and 2019.
David Minicucci, the chief commercial officer of Alaska Air Group. Expressed a preference for the MAX 10 due to its larger capacity. The MAX 10 can accommodate 189 passengers, compared to the MAX 9's capacity of 178 passengers. Minicucci noted that for similar trip costs, the MAX 10 allows for an additional 11 passengers.
Alaska Air Group is eager for the approval of the MAX 10 but emphasizes the importance of ensuring safety and appropriate certification. They anticipate being strong supporters of the MAX 10 once it is cleared for operation.
Boeing mentioned that the certification process for the MAX 7 is taking longer due to new documentation requirements. The company still anticipates receiving approval by the end of the year.
Analysts Provide Varied Ratings and Price Targets for Boeing
- RBC Capital analyst Ken Herbert reiterates a Sector Perform rating and maintains a $220 price target.
- Bernstein analyst Douglas Harned reaffirms an Outperform rating with a price target of $252.00.
Analyst Jason Gursky (CITI) has currently the highest performing score on BA with 16/18 (88.89%) price target fulfillment ratio. His price targets carry on an average of $41.52 (36.91%) potential upside and are fulfilled within an average of 480 days.
Intel Expects Major Cost Savings from New Business Structure
Intel's foundry initiative appears to be moving ahead. CFO David Zinsner providing valuable on Barron’s insights on the plan and its implications for the company.
Here are the key takeaways from this interview:
- Structure Change: The company's new structure will see Intel's internal product businesses treated like any other customer by the foundry unit. Market-based pricing for chip manufacturing. Zinsner believes this will incentivize units to become more efficient and will ultimately result in significant cost savings for Intel. The expected savings could be around $500 million to $1 billion a year due to reduced rush orders, testing time, and iterations of chip designs.
- Geographical Security: Intel is presenting its new foundry services business as a compelling option for customers looking for a more geographically secure supply chain, especially in the U.S. and Europe.
- Intellectual Property Protection: Zinsner mentioned that potential clients are particularly interested in the protection of their intellectual property. Intel's new structure will provide assurance that their IP is safe and a priority for the company.
- Future Customer Announcements: Intel expects to announce a major customer for its 18A node process later this year. The 18A process is the leading-edge chip manufacturing process that Intel has said will give the company industry performance leadership by 2025.
- Spin-off Possibility: Zinsner dismissed the possibility of a spin-off where Intel would separate its product and foundry businesses. He emphasized the benefits of the combined model, particularly in driving technological improvements on the leading edge nodes.
Analysts Reiterate Positive Outlook for Darden Restaurants and Maintain Price Targets
- Mizuho: Analyst Vijay Rakesh reiterated a Neutral rating and maintained a $30 price target.
- Benchmark: Analyst Cody Acree also reiterated a Buy rating and a $39 price target.
- Needham: Analyst Quinn Bolton gave Intel a Buy rating, with a price target of $36.
- Jefferies: Analyst Mark Lipacis has raised the price target to $35.
- BofA Securities: Analyst Vivek Arya raised the price target to $32, up from $28.
Analyst David Tarantino (BAIRD) has currently the highest performing score on DRI with 18/20 (90%) price target fulfillment ratio. His price targets carry on an average of $18.27 (22.34%) potential upside and are fulfilled within an average of 310 days..
Daily stock Analysts Top Price Moves Snapshot
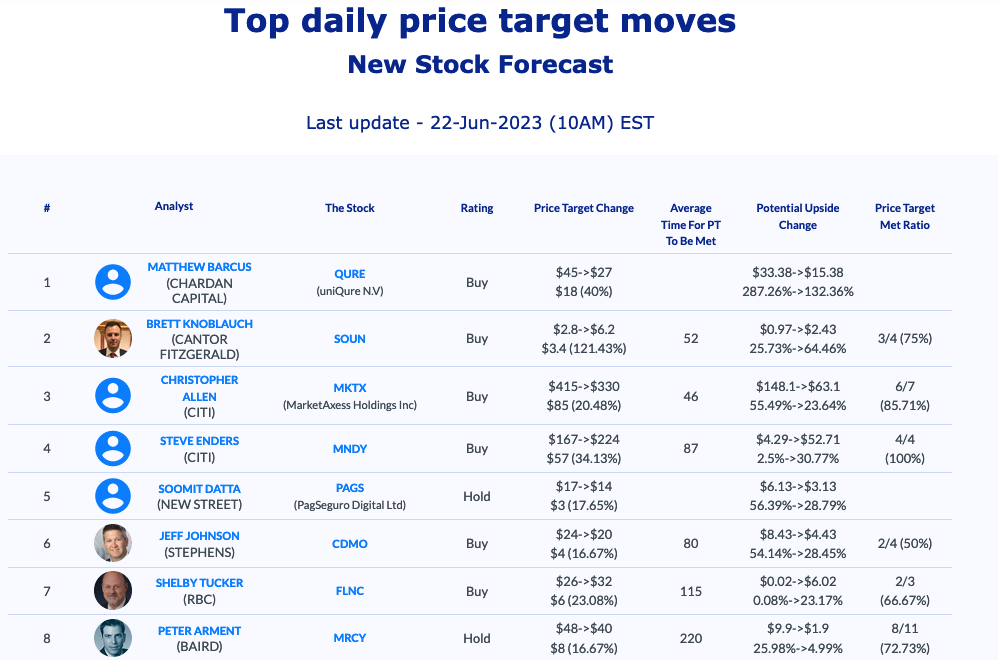
June 23, 2023: Selected stock price target news of the day: June 23, 2023
By Matthew Otto
Darden beats revenue, disappoints on outlook
Darden Restaurants has reported Q4 earnings exceeding Wall Street's estimates, largely due to strong sales at LongHorn Steakhouse. The company announced net income of $315.1 million or $2.58 per share (which was $0.04 better than the analyst estimate of $2.54), up from $281.7 million or $2.24 per share from the previous year, with net sales increasing by 6.4% to $2.77 billion.
LongHorn Steakhouse contributed to this increase with a 7.1% same-store sales growth, which surpassed StreetAccount estimates of 4.9%. However, the company's forecast for fiscal 2024 disappointed investors, with predicted adjusted earnings per share from continuing operations between $8.55 and $8.85, lower than analysts' expectations of $8.79 per share. Olive Garden, responsible for approximately 45% of Darden's sales, also underperformed with same-store sales growth of 4.4%, compared to an expected 5%.
The fine dining segment, which includes The Capital Grille and Eddie V's, experienced same-store sales declines of 1.9%. The company also announced that former CEO Gene Lee is set to step down as board chair.
Analysts Adjusts Darden Outlook Amid AI Partnerships
- DChristopher Carril from RBC Capital has maintained his Outperform rating but adjusted the price target down from $185 to $183.
- Brian Nowak from Morgan Stanley has kept his Overweight rating, lifting the price target from $168 to $171.
- Andrew Strelzik from BMO Capital has retained his Market Perform rating and increased the price target from $150 to $160.
- Brian Bittner from Oppenheimer has reaffirmed his Outperform rating, keeping the price target at $185.
- Nick Setyan from Wedbush has maintained his Outperform rating, boosting the price target from $175 to $178.
- Andrew Charles from TD Cowen has reiterated his Outperform rating, raising the price target from $160 to $175.
- Joshua Long from Stephens has held onto his Overweight rating, keeping the price target steady at $170.
- Jon Tower from Citi has increased Darden's price target to $195.
- Jeffrey Bernstein from Barclays has lifted the price target to $177.
Analyst David Tarantino (BAIRD) has currently the highest performing score on DRI with 18/20 (90%) price target fulfillment ratio. His price targets carry on average an $18.27 (22.34%) potential upside and typically reach target within an average of 310 days.
MongoDB Launches AI Innovators Program to Accelerate Generative AI in Business Operations
MongoDB has announced the AI Innovators Atlas Program during its developer conference. This program aims to provide organizations creating AI technology with resources to hasten their innovation and reach the market faster.
Generative AI is transforming technology stacks across different areas. Amid rapid innovation, both startups and well-established companies are keen to leverage generative AI to revolutionize business operations and disrupt industries. The MongoDB AI Innovators Program aims to provide these organizations a clearer path to innovation, using the best tools for the job, partnering with subject matter experts, and identifying ways to bring their AI-powered applications to market quickly.
Analysts Raise MongoDB Price Targets Following AI Innovators Program Announcement
- Brent Bracelin from Piper Sandler reasserted his Overweight rating and held steady with a $400 price target.
- Needham analyst Mike Cikos reiterated his Buy rating and kept his price target at $430.
- Brad Reback from Stifel raised his price target from $375 to $420 while preserving a Buy rating.
- Kash Rangan from Goldman Sachs elevated the price target from $420 to $440.
- Matthew Broome of Mizuho Securities increased the price target to $240.
- Sanjit Singh of Morgan Stanley lifted the price target to $440.
- Rishi Jaluria from RBC Capital heightened the price target to $445.
- Truist Securities analyst Miller Jump boosted the price target to $420.
Analyst Brent Bracelin (PIPER SANDLER) has currently the highest performing score on MDB with 20/24 (83.33%) price target fulfillment ratio. His price targets carry on an average of $46.21 (20.64%) potential upside and typically reach target within an average of 84 days.
FDA Grants Accelerated Approval to Sarepta's Gene Therapy for Duchenne Muscular Dystrophy
The US Food and Drug Administration (FDA) has granted accelerated approval for Sarepta Therapeutics' one-time gene therapy treatment, Elevidys, for children with Duchenne muscular dystrophy (DMD). The approval, the first of its kind for a gene therapy to treat DMD, allows the drug to be sold based on lab measures anticipated to predict clinical benefit, rather than direct evidence of benefit.
However, the approval is confined to children between 4 and 5 years old who can still walk, narrower than Sarepta's initial request for approval in all DMD patients able to walk. This approval comes after the FDA had reportedly planned to reject the application.
DMD is a progressive disease that leads to muscle atrophy, disability, and death. Sarepta's drug enables DMD patients to produce a protein related to muscle growth, which their bodies are otherwise unable to do. However, the company is yet to provide clear evidence that the gene therapy can halt muscle decline in patients.
The company's decision to seek approval for the drug prior to the completion of an ongoing Phase 3 trial took Wall Street by surprise last year. This trial is expected to yield top-line results later this year. The FDA plans to review these results upon availability and may consider revising the drug's indication or withdrawing Elevidys.
Analysts Respond with Mixed Revisions to Price Targets
- Matthew Harrison from Morgan Stanley reaffirmed an Overweight rating on Sarepta Therapeutics, persisting with a price target of $183.
- Brian Abrahams from RBC Capital restated an Outperform rating and sustained a price target of $218.
- Judah Frommer from Credit Suisse continued with a Neutral rating and stuck with a price target of $141.
- Gavin Clark-Gartner from Evercore ISI Group downgraded Sarepta Therapeutics from Outperform to Neutral and set a price target of $139.
- Gil Blum from Needham endorsed a Buy rating again and held his price target of $185.
- Goldman Sachs escalated its price target on Sarepta Therapeutics to $215.
- Gena Wang from Barclays also elevated her price target to $193.
Analyst Brian Skorney (BAIRD) has currently the highest performing score on SRPT with 38/50 (76%) price target fulfillment ratio. His price targets carry on an average of $38.05 (75.14%) potential upside and typically reach target within an average of 305 days.
Daily stock Analysts Top Price Moves Snapshot
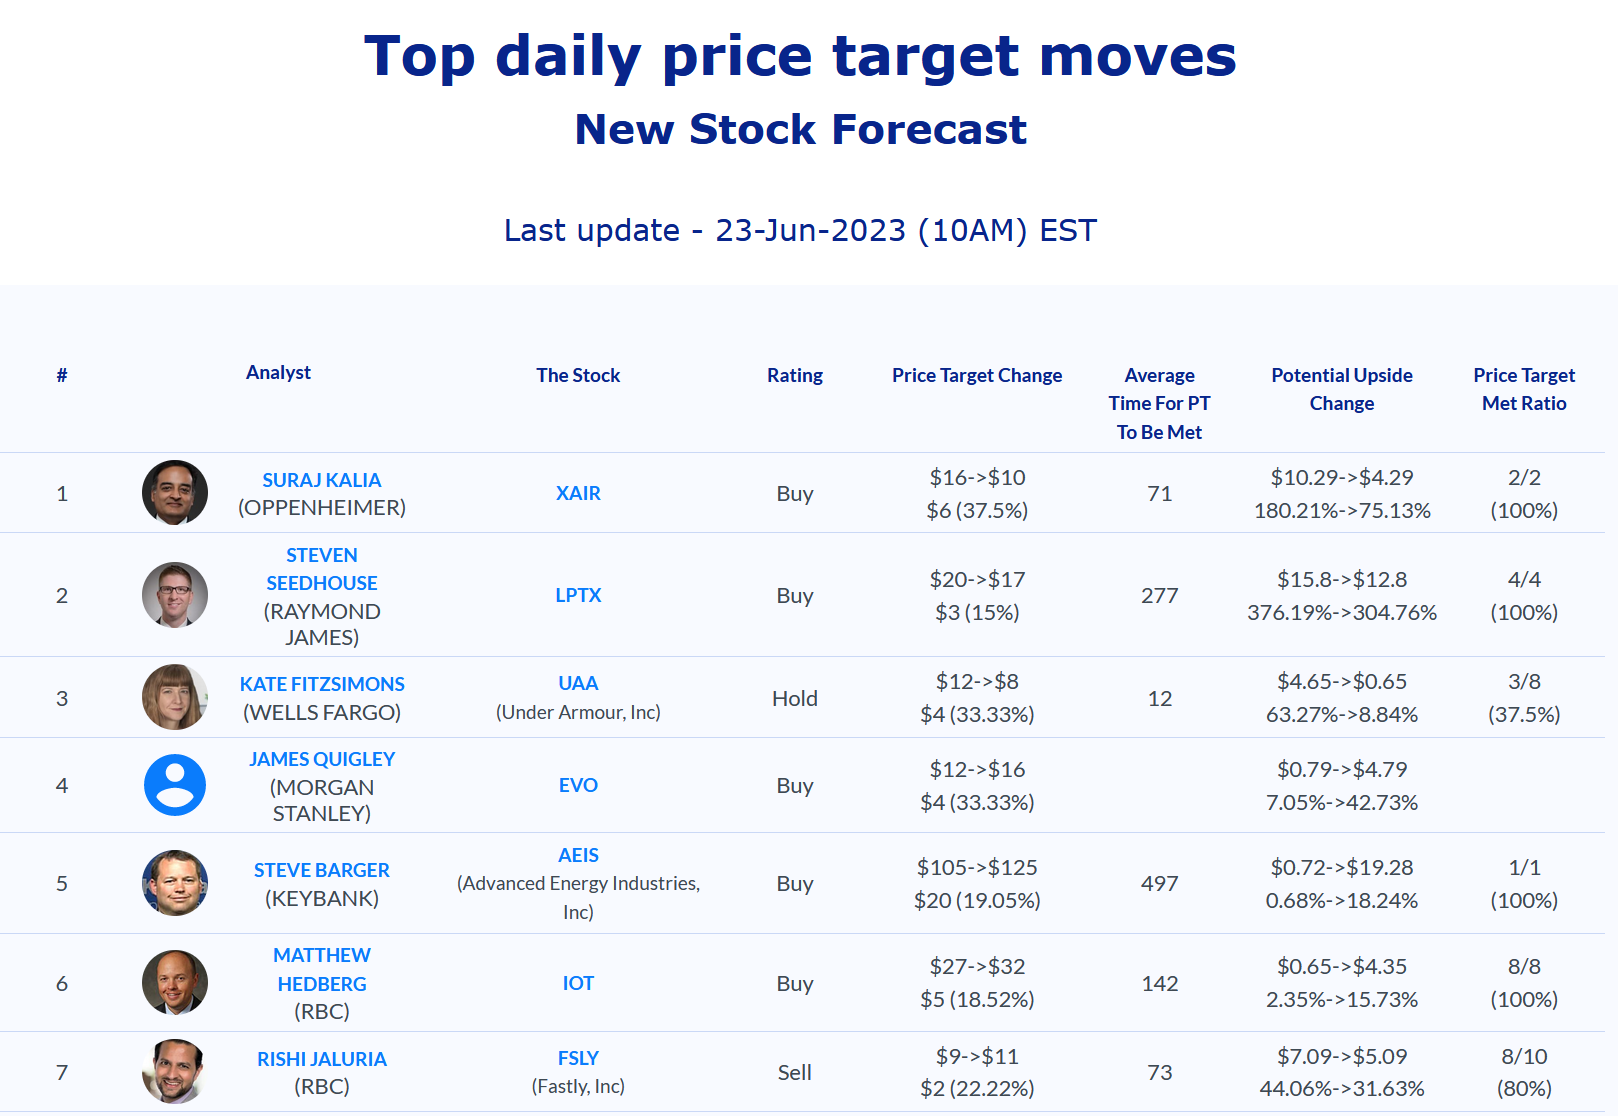
June 26, 2023: Selected stock price target news of the day: June 26, 2023
By Matthew Otto
FDA Approves Sarepta's Gene Therapy for Duchenne Muscular Dystrophy But with Conditions
The U.S. Food and Drug Administration (FDA) has given its approval to Sarepta Therapeutics' gene therapy, Elevidys, marking it as the first-ever gene therapy to treat Duchenne muscular dystrophy (DMD). This progressive and fatal condition appears in early childhood and gradually weakens the muscles. Elevidys, priced at $3.2 million for a one-time treatment, is among the world's most expensive medicines. Sarepta adopted a bold strategy by seeking accelerated approval for the drug, using preliminary data showing that the therapy allows patients to produce a protein related to muscle growth.
However, the FDA's approval came with certain restrictions and warnings. The approval only applies to children between the ages of 4 and 5 who can still walk, a much narrower demographic than the 4 to 13 age range Sarepta initially tested and sought approval for. Additionally, the FDA issued a warning that it might withdraw its approval if the results of the ongoing Phase 3 EMBARK trial do not turn out positive.
Analysts Give Mixed Reviews on Sarepta Therapeutics Following FDA Approval of Elevidys
- Neena Bitritto-Garg, a Citigroup analyst maintains a Buy rating, but has lowered the price target from $204 to $161.
- Kristen Kluska from Cantor Fitzgerald keeps an Overweight rating and raised the price target from $153 to $166.
- Salveen Richter from Goldman Sachs maintains a Buy rating and raises the price target from $188 to $215.
- Anupam Rama, JP Morgan analyst, continues to endorse an Overweight rating but slightly lowered the price target from $217 to $213.
- Matthew Harrison from Morgan Stanley reaffirms an Overweight rating, maintaining a $183 price target.
- Brian Abrahams, RBC Capital analyst reiterates an Outperform rating and maintains a $218 price target.
- Judah Frommer from Credit Suisse sticks with a Neutral rating and maintains a $141 price target.
- Gavin Clark-Gartner, analyst from Evercore has downgraded Sarepta Therapeutics from Outperform to Neutral and announces a $139 price target.
Analyst Brian Skorney (BAIRD) has currently the highest performing score on SRPT with 38/50 (76%) price target fulfillment ratio. His price targets carry on an average of $38.05 (75.14%) potential upside and typically reach target within an average of 305 days.
Sonic Automotive Restructures Operations and Aims for Enhanced Profitability
Sonic Automotive has made changes to navigate the current challenging conditions in the pre-owned vehicle market. In a strategic move, the company has indefinitely suspended operations at eight EchoPark locations and associated Delivery/Buy Centers. This step aims to focus Sonic's resources on key markets to meet existing demand more efficiently.
The company is striving to ensure EchoPark's agility, enabling it to adapt swiftly to fluctuating market conditions. Sonic predicts that price volatility will persist into 2024, even though there have been signs of improvement in pre-owned wholesale pricing. Looking ahead, Sonic expects increased production of new vehicles over the next 12-18 months.
Analysts Give Mixed Ratings to Sonic Automotive
- Daniel Imbro from Stephens & Co. has reiterated an Overweight rating and maintains a price target of $55.
- Rajat Gupta from JP Morgan maintains a Neutral rating but has raised the price target from $50 to $52.
Analyst Rajat Gupta (JPMORGAN) has currently the highest performing score on SAH with 11/12 (91.67%) price target fulfillment ratio. His price targets carry on an average of $7.1 (20.14%) potential upside and typically reach target within an average of 123 days.
Vertex Pharmaceuticals and Lonza Announce Collaboration to Advance Stem Cell-Derived Therapies for Type 1 Diabetes
Vertex Pharmaceuticals and Lonza have announced a strategic collaboration to support the manufacture of Vertex's investigational stem cell-derived islet cell therapies for individuals with Type 1 diabetes (T1D). The collaboration focuses on Vertex's VX-880 and VX-264 programs, which have shown promising results in clinical trials. The partnership involves process development, scale-up, and the construction of a dedicated facility in New Hampshire, operated by Lonza. This collaboration leverages Lonza's expertise in cell and gene technologies and is expected to accelerate the development and commercialization of Vertex's transformative therapies.
Analysts Reiterate Buy Rating on Vertex Pharmaceuticals
- HC Wainwright analyst Andrew Fein reiterates Buy rating and a $380 price target.
- Liisa Bayko from Evercore ISI raises her price target to $379.
Analyst Do Kim (PIPER SANDLER) has currently the highest performing score on VRTX with 32/35 (91.43%) price target fulfillment ratio. His price targets carry on an average of $19.8 (11.72%) potential upside and typically reach target within an average of 169 days.
Daily stock Analysts Top Price Moves Snapshot

June 27, 2023: Selected stock price target news of the day: June 27, 2023
By Matthew Otto
Carnival Surpasses Q2 2023 Expectations,
In Q2 2023, Carnival Cruise had an adjusted EBITDA of $681 million, driven by a revenue increase from higher ticket prices. However, higher fuel prices and currency impacts, as well as adjusted cruise costs, offset the revenue favorability.
The company prepays $1.4 billion of variable rate debt, reducing their interest expense by over $80 million this year. They forecasted an adjusted EBITDA of $4.10 billion to $4.25 billion for full-year 2023. The SEA Change Program has improved the financial position, with projected total debt at year-end under $33 billion. The company predicted average annual adjusted free cash flow of over $3 billion from 2024 to 2026. It aimed to reduce debt, targeting over $10 billion in debt reduction and transferring enterprise value from debt holders to shareholders. That would position Carnival to approach investment grade leverage metrics by the end of 2026.
Carnival Receives Mixed Analyst Ratings and Price Targets
- Stifel analyst Steven Wieczynski reiterated a Buy rating and a $18 price target.
- Truist Securities analyst Patrick Scholes maintains a Sell rating and a target price of $11.
- Deutsche Bank analyst Chris Woronka lowered the price target to $14.
- Susquehanna analyst Christopher Stathoulopoulos raised the price target to $17.
- Wells Fargo analyst Daniel Politzer increased the price target to $15.
- Barclays analyst Brandt Montour raised the price target to $19 while maintaining an Overweight rating.
Analyst James Ainley (CITI) has currently the highest performing score on CCL with 4/5 (80%) price target fulfillment ratio. His price targets carry on an average of $4.23 (20.95%) potential upside and typically reach target within an average of 22 days.
Alaska Airlines Expands Travel Options with New International Flights
Alaska Airlines is expanding its international flights to include the Bahamas and Mexico. This marks the airline's first-ever flights to the Bahamas, with nonstop journeys from both Los Angeles and Seattle. It also increases its service to Mexico with new routes from Las Vegas to both Cabo San Lucas and Puerto Vallarta. These new routes are set to commence in mid-December.
The move comes as a response to strong demand for travel to leisure destinations. The addition of more 737-9 aircraft to the Alaska Airlines fleet covers longer distances, enabling trips like Seattle to Nassau.
Analysts Raise Price Targets for Alaska Air Group, Maintaining Positive Outlook
- BofA Securities analyst Andrew Didora maintains a Buy rating and raises the price target from $58 to $62.
- Raymond James analyst Savanthi Syth maintains a Strong Buy rating on Alaska Air Group and raises the price target from $70 to $75.
Analyst Brandon Oglenski (BARCLAYS) has currently the highest performing score on ALK with 29/36 (80.56%) price target fulfillment ratio. His price targets carry on average an $7.82 (27.99%) potential upside and typically reach target within an average of 264 days.
Snowflake Partners With NVIDIA to Enable Custom Generative AI Applications
Snowflake and NVIDIA have announced a partnership. It will enable businesses to develop customized generative AI applications using their proprietary data within the Snowflake Data Cloud. This collaboration combines NVIDIA's NeMo platform and GPU-accelerated computing with Snowflake's secure data platform to empower enterprises of all sizes. With the ability to create and fine-tune custom language models, businesses can leverage their data. They can build advanced generative AI services such as chatbots and search functionalities.
The joint effort between Snowflake and NVIDIA provides businesses with an opportunity to leverage their own data while ensuring security and governance. By integrating AI capabilities within the Snowflake Data Cloud, enterprises can build generative AI applications where their data resides, reducing costs and latency.
Analysts Reiterate Positive Outlook for Snowflake and Raise Price Targets
- JMP Securities analyst Joe Goodwin maintains a Market Outperform rating and the price target at $200.
- Deutsche Bank analyst Brad Zelnick maintains a Buy rating and raises the price target from $170 to $185.
Analyst Brad Reback (STIFEL) has currently the highest performing score on SNOW with 6/6 (100%) price target fulfillment ratio. His price targets carry on an average of $-1.92 (2.68%) potential downside and typically reach target within an average of 16 days.
Lordstown Motors Restructuring after Failed Foxconn Partnership
In a strategic restructuring effort, Lordstown Motors aims to capitalize on the value of its assets. Those assets include the Endurance all-electric (EV) pickup truck and its corresponding intellectual property, platform, and development team. This move comes after the recent breakdown of the partnership with Hon Hai Technology Group (Foxconn).
The suit claims Foxconn acted fraudulently and failed to meet its commercial and financial commitments to Lordstown. That resulted in significant harm to the company and its future prospects.
Lordstown is initiating a marketing and sale process for the Endurance vehicle and related assets in response to the damage caused by Foxconn. To facilitate this process and provide prospective buyers with an asset free from legacy issues, Lordstown is restructuring under Chapter 11 of the U.S. Bankruptcy Code.
The lawsuit against Foxconn centers around a strategic partnership aimed to combine Lordstown's resources with Foxconn's established automotive capabilities. However, the suit alleges that Foxconn never intended to uphold its commitments. It instead used the partnership to further its own business interests at the expense of Lordstown.
Wall Street Reaction
No new analyst recommendations were given at this moment.
Analyst Emmanuel Rosner (DEUTSCHE BANK) has currently the highest performing score on RIDE with 4/4 (100%) price target fulfillment ratio. His price targets carry on average an $-0.31 (3.53%) potential downside and typically reach target within an average of 40 days.
Daily stock Analysts Top Price Moves Snapshot
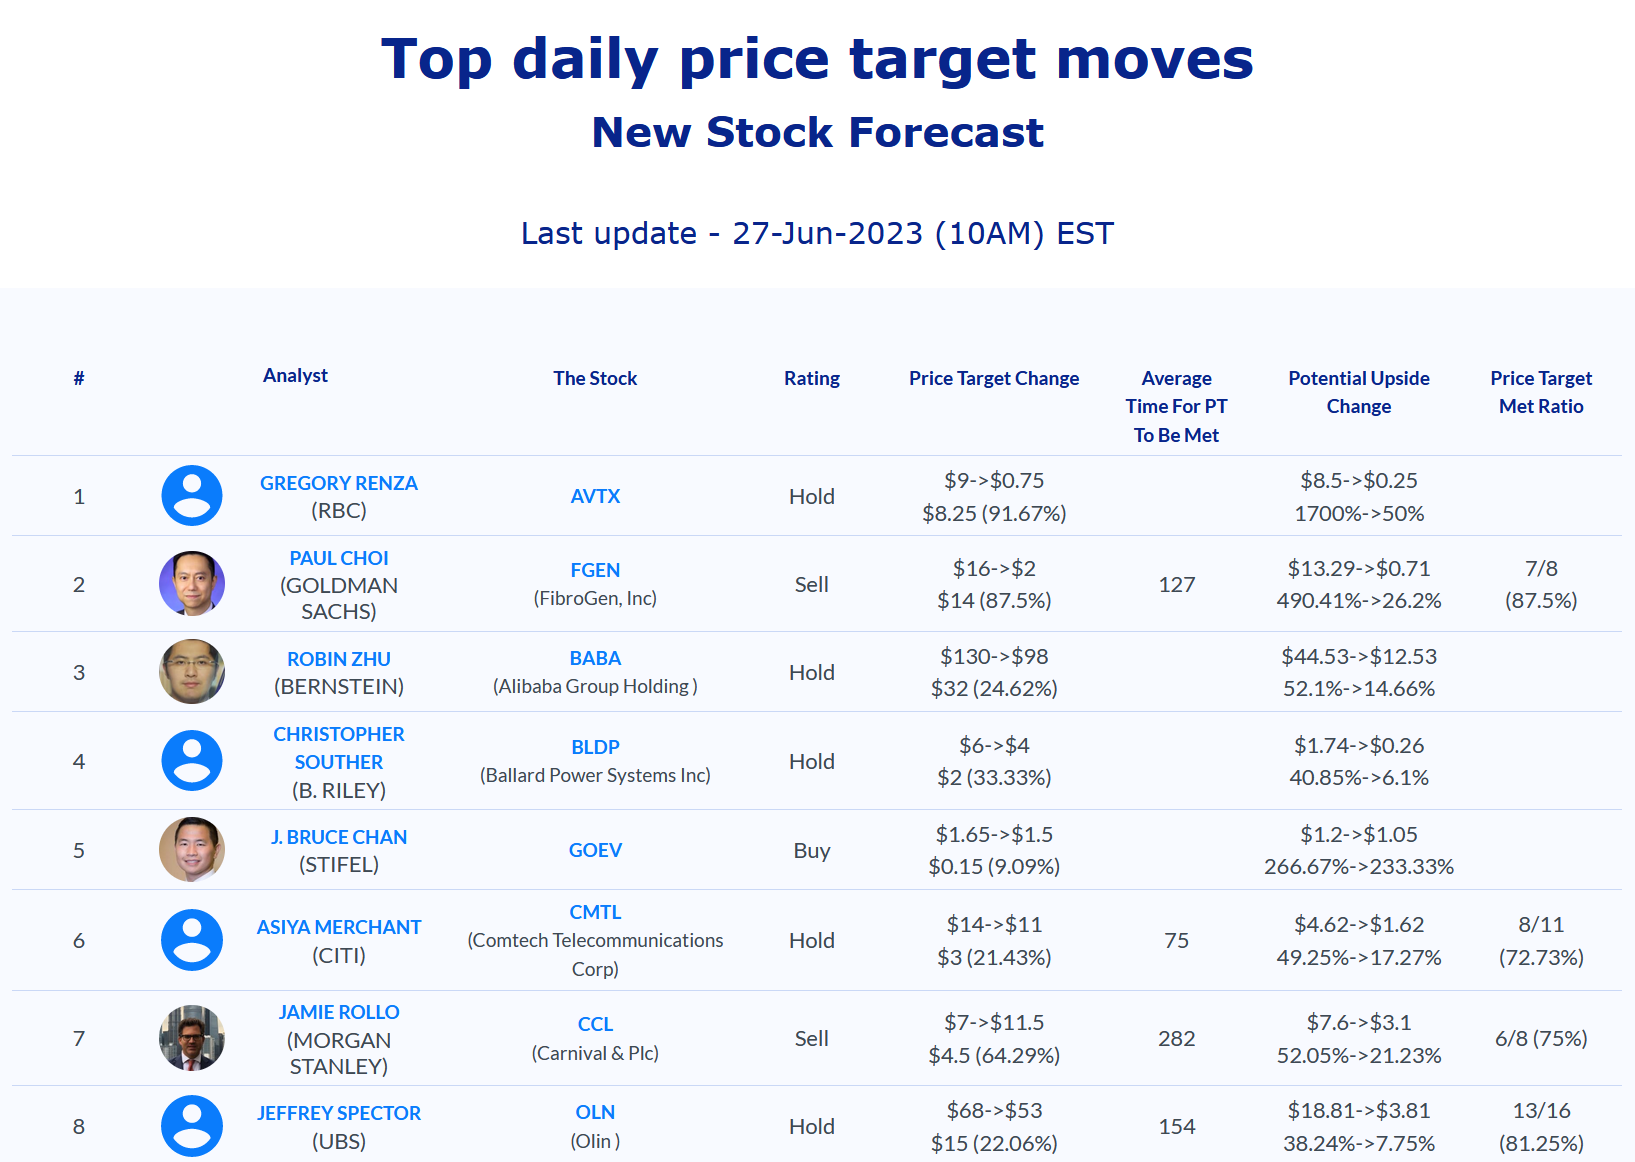
June 28, 2023: Selected stock price target news of the day: June 28, 2023
By Matthew Otto
Black Diamond Therapeutics Announces BDTX-1535 in Phase 1 Clinical Trial for Lung Cancer Treatment
Black Diamond Therapeutics has announced initial clinical data from the Phase 1 study of BDTX-1535. , a fourth-generation epidermal growth factor receptor (EGFR) MasterKey inhibitor. This drug, currently in development for the treatment of non-small cell lung cancer (NSCLC) and glioblastoma multiforme (GBM). Has shown activity in NSCLC patients harboring both acquired resistance and intrinsic driver EGFR mutations.
BDTX-1535 is the first EGFR Tyrosine Kinase Inhibitor (TKI) to demonstrate radiographic responses across a range of NSCLC patients, including those with acquired resistance mutations post-osimertinib therapy and those with cancers driven by classical and intrinsic driver mutations. The company plans to collaborate with the FDA to define their Phase 2 dose selection strategy and potentially discuss a path to accelerated approval for this drug.
Meanwhile, Non-small cell lung cancer (NSCLC) is the most common type of lung cancer, accounting for approximately 85% of all cases. It is a malignant condition that affects the tissues of the lungs and can spread to other parts of the body. NSCLC is generally divided into three subtypes: adenocarcinoma, squamous cell carcinoma, and large cell carcinoma.
Analysts Provide Mixed Recommendations for Black Diamond Therapeutics Following Clinical Data Release
- HC Wainwright analyst Robert Burns has upgraded from Neutral to Buy, maintaining a price target of $11.
- Stifel analyst Bradley Canino has reiterated his position, maintaining a Hold recommendation and a $2 price target.
- Wedbush analyst Robert Driscoll has upgraded from Neutral to Outperform, and the price target from $3 to $10.
So, Analyst Robert Driscoll (WEDBUSH) has currently the highest performing score on BDTX with 1/4 (25%) price target fulfillment ratio. His price targets carry on an average of $10.43 (67.41%) potential upside and are fulfilled within an average of 48 days.
Delta Air Lines Raises Q2 Forecast and Expects Full-Year Earnings at the High End of Estimates
Delta Air Lines has increased its financial forecast for Q2 2023. As well as for the full year, attributing the upgrade to strong travel demand and an uptick in premium fare purchases. The company now predicts Q2 earnings per share between $2.25 and $2.50, an increase from the previous estimate of $2 to $2.25. The airline also expects full-year adjusted earnings of $6 per share.
Delta is also benefitting from a 30% decrease in jet fuel prices compared to the previous year. The airline expects revenue per available seat mile (an important airline industry metric) to increase by up to 18% compared to the previous year, beating an earlier forecast of 15% to 17% growth.
Wall Street Action
- Susquehanna analyst Christopher Stathoulopoulos: Remains in a Positive rating and raises the price target from $45 to $54.
- Goldman Sachs analyst Catherine O'Brien: Stays on a Buy rating and raises the price target from $42 to $52.
- Morgan Stanley analyst Ravi Shanker: Reiterates an Overweight rating and a $70 price target.
- Jefferies analyst Sheila Kahyaoglu: Maintains a Buy rating and raises the price target from $45 to $50.
- BofA Securities analyst Andrew Didora: Reiterates a Buy rating and raises the price target from $40 to $48.
Meanwhile, Analyst Brandon Oglenski (BARCLAYS) has currently the highest performing score on DAL with 31/36 (86.11%) price target fulfillment ratio. His price targets carry on an average of $8.55 (43.34%) potential upside and are fulfilled within an average of 547 days.
FDA Declines Regeneron’s Approval of Higher-Dose Eylea
A recent setback for Regeneron Pharmaceuticals in their bid to have a higher-dose version of their drug. Eylea, approved by the U.S. Food and Drug Administration (FDA). Eylea is used to treat a disease called wet age-related macular degeneration (AMD). Approximately 20 million people in the United States have AMD. , and nearly 1.5 million Americans have the advanced form of the disease.
The FDA, however, issued a complete response letter which asks a reply for unanswered questions. However, the letter does not indicate issues with the drug's efficacy, safety. Trial design, labeling, or substance manufacturing, and does not request additional clinical data or studies. The regulator's concerns seem to be focused on inspection findings at a third-party filler of the higher dose.
Analysts Provide Diverse Ratings and Price Targets for Regeneron
- Canaccord Genuity analyst John Newman has downgraded from Buy to Hold and the price target from $953 to $720.
- Truist Securities analyst Robyn Karnauskas has reiterated a Buy rating and a price target of $1050.
- RBC Capital analyst Brian Abrahams has reiterated a Sector Perform rating, maintaining a price target of $816.
- Barclays analyst Carter Gould has downgraded the price target to $888 from $915.
- Jefferies analyst Akash Tewari has lowered the price target to $870.
- Wells Fargo analyst Mohit Bansal has dropped the price target to $875.
Analyst Tyler Van Buren (COWEN) has currently the highest performing score on REGN with 6/8 (75%) price target fulfillment ratio. His price targets carry on an average of $25.94 (3.56%) potential upside and are fulfilled within an average of 16 days.
Daily stock Analysts Top Price Moves Snapshot

June 29, 2023: Selected stock price target news of the day: June 29, 2023
By Matthew Otto
Micron Releases Positive Q3 Results,Upbeats Q4 Forecast
Micron Technology reported a better-than-expected Q3 fiscal performance and issued an upbeat outlook for Q4. Despite facing significant headwinds due to recent decisions by the Cyberspace Administration of China. The company has managed to post an adjusted loss of $1.43 per diluted share on a revenue of $3.75 billion, surpassing analysts' predictions of a $1.59 loss per share on a revenue of $3.67 billion.
Looking ahead, Micron estimates an adjusted Q4 loss of around $1.19 per diluted share and anticipates a revenue of about $3.90 billion. The optimistic outlook, which exceeds Wall Street's predictions, arises from the company's assertion that the memory industry has surpassed its lowest point in revenue. The company anticipates improved margins as the industry supply-demand balance is gradually restored, despite the ongoing challenges associated with China's recent regulatory actions.
Wall Street Action
- Needham analyst Rajvindra Gill maintains a Buy rating and raises the price target from $71 to $80.
- Raymond James analyst Srini Pajjuri maintains an Outperform rating and raises the price target from $70 to $76.
- Piper Sandler analyst Harsh Kumar upgrades from Underweight to Neutral and the price target from $45 to $70.
- Keybanc analyst John Vinh maintains an Overweight rating and raises the price target from $70 to $80.
- Barclays analyst Tom O'Malley raised the price target to $75, up from $70.
Meanwhile, Analyst Brian Chin (STIFEL) has currently the highest performing score on MU with
3/4 (75%) price target fulfillment ratio. His price targets carry on average an $1.65 (3.59%) potential upside and typically reach target within an average of 15 days.
Walgreens Misses Earnings Expectations, Faces Stock Downgrade and Multiple Business Challenges
Walgreens didn't perform well in the fiscal third quarter, with its earnings not meeting expectations. As a result, the company lowered its full-year guidance. This was mainly attributed to fewer Covid-19 related visits and the economic stress experienced by consumers. These factors led to a significant drop in Walgreens' share price over two days, reaching its lowest value since 2010.
In addition, Deutsche Bank analyst, George Hill, who had previously been supportive of Walgreens and considered it a strong buy. Admitted his misjudgment and downgraded the stock to a Hold status. Hill listed multiple issues within the company, including reduced guidance in the Healthcare business, ongoing difficulties in the Pharmacy unit, dividend concerns. Potential overestimations in Covid vaccine demand, which might negatively impact the 2024 guidance if the anticipated profitability in Healthcare does not happen.
Analysts Provide Mixed Outlook for Walgreens Boots Alliance with Price Target Adjustments
- Mizuho analyst Ann Hynes reiterates a Neutral rating and a $35 price target.
- JP Morgan analyst Lisa Gill maintains a Neutral rating and lowers the price target from $40 to $35.
- Barclays analyst Steve Valiquette remains with an Equal-Weight rating and lowers the price target from $38 to $32.
- Credit Suisse analyst Jonathan Yong maintains a Neutral rating and lowers the price target from $41 to $33.
- Deutsche Bank analyst George Hill downgrades from Buy to Hold and the price target from $46 to $34.
So, Analyst Elizabeth Anderson (EVERCORE) has currently the highest performing score on WBA with 2/3 (66.67%) price target fulfillment ratio. Her price targets carry on an average of $2.38 (5.76%) potential upside and typically reach target within an average of 7 days.
Synnex Shares Plunges as Q2 Fiscal 2023 Results Miss Expectations
Synnex's Q2 fiscal 2023 results missed expectations. Non-GAAP earnings of $2.43 per share falling short of the estimated $2.50 per share. Revenue fell 7.9% YoY to $14.1 billion, missing the consensus mark of $14.37 billion. This decline is largely due to reduced demand for Endpoint Solutions. Was partially offset by increased sales from the Advanced Solutions portfolio.
Looking forward, Synnex issued a weak outlook for the third quarter of fiscal 2023, expecting revenues between $13.5 billion and $14.5 billion. Lower than the consensus estimate of $14.8 billion. Non-GAAP net income is projected to range between $206 million and $253 million, and Q3 non-GAAP earnings per share are expected to be between $2.20 and $2.70, below the consensus estimate of $2.69 per share.
Analysts Lower Price Targets for Synnex and Maintained Mixed Recommendations
- Barrington Research analyst Vincent Colicchio maintains an Outperform rating and lowers the price target from $120 to $115.
- RBC Capital analyst Ashish Sabadra remains a Sector Perform rating and lowers the price target from $110 to $98.
- Barclays analyst Tim Long maintains an Equal-Weight rating and lowers the price target from $103 to $98.
- Credit Suisse analyst Shannon Cross reiterates a Neutral rating and lowers the price target from $106 to $90.
- Raymond James analyst Adam Tindle maintains a Strong Buy rating and lowers the price target from $125 to $120.
Meanwhile, Analyst Shannon Cross (CREDIT SUISSE) has currently the highest performing score on SNX with 3/6 (50%) price target fulfillment ratio. Her price targets carry on average an $11.12 (11.77%) potential upside and typically reach target within an average of 76 days.
Daily stock Analysts Top Price Moves Snapshot
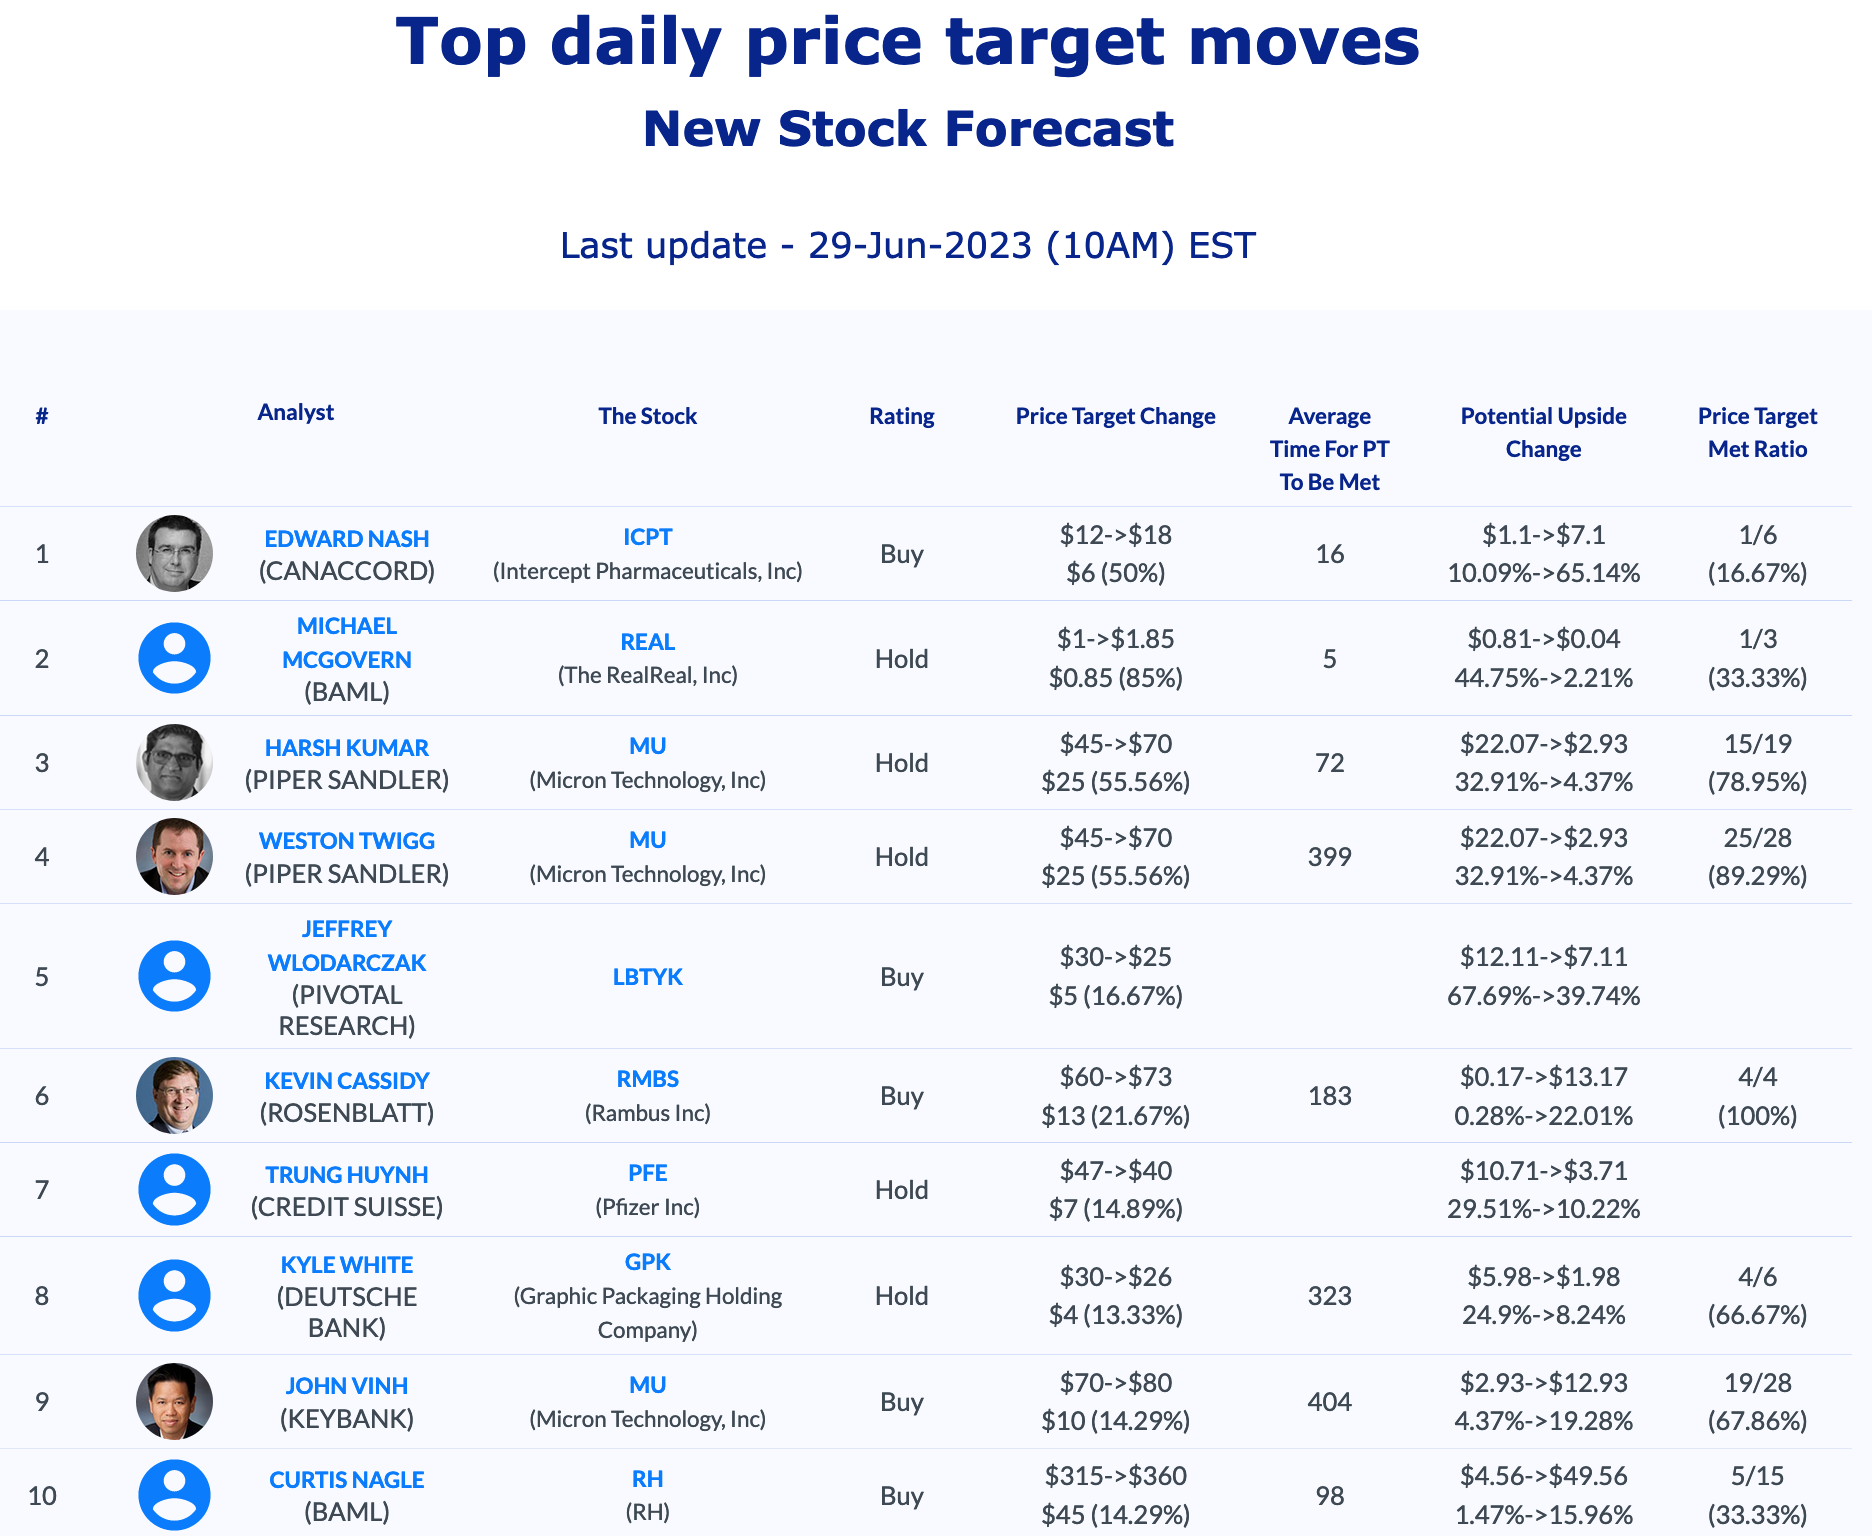
June 30, 2023: Selected stock price target news of the day: June 30, 2023
By: Matthew Otto
Nike Beats on Revenue; Earnings and Q1 Guidance Fall Short
Nike's fiscal fourth-quarter results released show that the company has beaten revenue estimates but fallen short on earnings per share and issued first-quarter guidance that failed to meet expectations.
Nike reported revenue of $12.8 billion for its fiscal fourth quarter, ahead of estimates for $12.58 billion. However, it missed earnings per share predictions, coming in at 66 cents a share, lower than the expected 68 cents a share.
The company's gross margins also took a hit, dropping 1.4 percentage points to 43.6% due to higher input costs and ongoing discounting to move excess inventory. Despite this, Nike returned about $1.9 billion to shareholders in the fourth quarter in the form of dividends and share repurchases.
Looking to the future, Nike forecasts that first-quarter revenue will either remain flat or grow by low-single digit percentage points, which is lower than Wall Street's estimates for 6% growth. For fiscal 2024, Nike projects that its revenue will grow by mid-single digit percentages, in line with current analyst estimates.
Despite the concerns, the company remains confident in its ability to drive sustainable long-term growth, especially in China. Nike's CFO, Matthew Friend, highlighted strong consumer momentum, a robust product innovation pipeline, healthy inventory, and a normalized flow of supply as advantages entering the new year. However, the company is also closely monitoring the macro environment, consumer behavior, and retail trends.
For the full fiscal year 2023. Nike's reported revenues were $51.2 billion, up 10 percent compared to the prior year, and up 16 percent on a currency-neutral basis. Net income for the year was $5.1 billion, down 16 percent, and diluted earnings per share were $3.23, down 14 percent compared to the prior year.
Analysts Maintain Optimistic Outlook on Nike Despite Earnings Miss and Lowered Guidance
- Wedbush analyst Tom Nikic maintains an Outperform rating and has raised the price target from $129 to $131.
- Raymond James analyst Rick Patel also continues with an Outperform rating, but lowered the price target from $135 to $128.
- Telsey Advisory Group analyst Joseph Feldman reiterated an Outperform rating and maintains a $135 price target.
- Morgan Stanley analyst Alex Kurtz remains positive with an Overweight rating, but lowered the price target from $130 to $127.
- RBC Capital analyst Piral Dadhania continues with an Outperform rating but lowered the price target from $138 to $134.
- Jefferies analyst Randal Konik, while maintaining a Buy rating, lowered the price target significantly from $160 to $140.
Analyst Rick Patel (RAYMOND JAMES) has currently the highest performing score on NKE with 14/16 (87.5%) price target fulfillment ratio. His price targets carry on average an$12.78 (13.12%) potential upside and typically reach target within an average of 119 days.
Accolade Exceeds Q1 2024 Revenue Estimates, Raises Full-Year Guidance
Accolade announced financial results for the fiscal first quarter ended May 31, 2023, exceeding both its top and bottom line guidance. The firm reported revenues of $93.2 million, a 9% increase from $85.5 million in the corresponding quarter of the previous year and above the consensus estimate of $90.27 million.
The company reported a net loss of $38.4 million, which was a substantial improvement from a loss of $342.8 million in the same quarter of the previous year. Largely due to a non-cash goodwill impairment charge that was recorded last year. The reported Q1 EPS of -$0.52 was $0.10 better than the analyst estimate of -$0.62.
Accolade's non-GAAP financial data demonstrated growth as well, with Adjusted EBITDA improving by 18% to -$12.6 million, compared to -$15.4 million in the first quarter of the prior fiscal year. Adjusted Gross Profit also grew slightly, from $39 million in Q1 2022 to $40.6 million this quarter.
Accolade has raised its revenue and Adjusted EBITDA guidance for the fiscal year. For the fiscal second quarter ending August 31, 2023, the company expects revenue to be between $93 million and $95 million, which aligns with the consensus estimate of $93 million. For the fiscal year ending February 29, 2024, Accolade projects revenue to range between $410 million and $414 million, with the lower end of this range aligning with the consensus estimate of $410 million. The company has not provided a specific guidance for net loss.
Wall Street Action
- tifel's analyst David Grossman maintains a Buy rating, raising the price target from $15 to $17.
- Morgan Stanley's Ricky Goldwasser reiterates an Equal-Weight rating, keeping the price target at $14.
- Stan Berenshteyn from Wells Fargo maintains an Equal-Weight rating, while increasing the price target from $13 to $14.
- Credit Suisse's Jonathan Yong holds a Neutral position, adjusting the price target upward from $13 to $15.
- Needham & Company's Ryan MacDonald raises the price target from $15 to $17, holding the Buy rating.
Analyst Ricky Goldwasser (MORGAN STANLEY) has currently the highest performing score on ACCD with 4/10 (40%) price target fulfillment ratio. Her price targets carry on average an $7.07 (26.83%) potential upside and typically reach target within an average of 31 days.
FDA Grants Approval to BioMarin's Roctavian
The U.S. Food and Drug Administration (FDA) has granted approval to Roctavian,
The treatment was developed by BioMarin Pharmaceutical. Roctavian, a one-time therapy, uses a viral vector to carry a gene for clotting Factor VIII, reducing the risk of uncontrolled bleeding. A cohort of 112 patients showed decreased annualized bleeding rates from 5.4 bleeds per year at baseline to 2.6 bleeds per year after Roctavian treatment.
A companion diagnostic test, the AAV5 DetectCDx, was also approved to identify eligible patients for the gene therapy. The test, developed by ARUP Laboratories. Has been shown to accurately detect pre-existing anti-AAV5 antibodies that could reduce the effectiveness of the gene therapy.
The CDC estimates about 10 in 100,000 people have hemophilia A
Wall Street Adjust on Biomarin
- Citigroup analyst David Lebowitz maintains a Neutral stance Pharmaceutical and lowers the price target from $103 to $96.
- Baird analyst Joel Beatty reiterates an Outperform rating Pharmaceutical and maintains a $127 price target.
- Wedbush analyst Andreas Argyrides maintains a Neutral stance Pharmaceutical, but raises the price target from $69 to $73.
Analyst Joseph Schwartz (LEERINK) has currently the highest performing score on BMRN with 17/25 (68%) price target fulfillment ratio. His price targets carry on average an $34.03 (42.37%) potential upside and typically reach target within an average of 883 days.
Daily stock Analysts Top Price Moves Snapshot