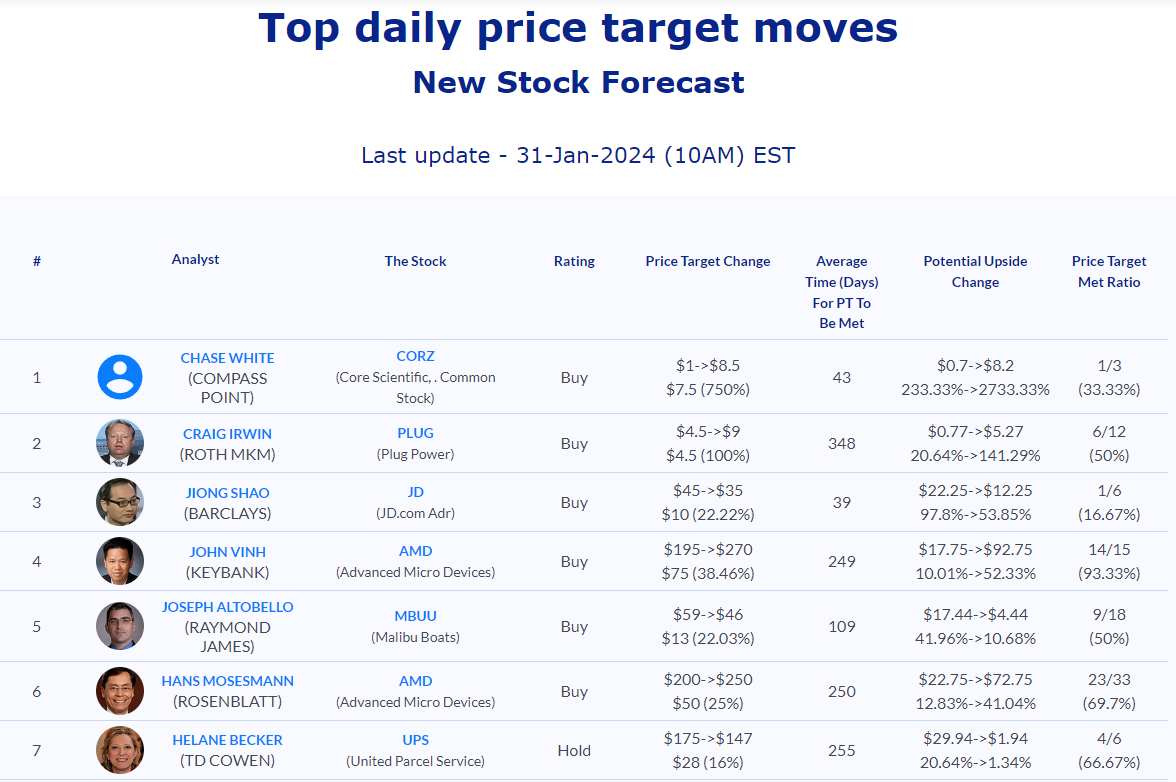
The analyst price target moves we wrote up each trading day in January 2024, 21 daily posts on one page. Jump to a day below, or open a ticker or analyst link for the full record behind each call.
January 2, 2024:
By: Matthew Otto
Apple Downgraded: iPhone and Mac Sales Concerns
Apple experienced a setback as Barclays downgraded its rating to Underweight. Analysts, led by Tim Long, cited weakening sales of iPhones and Mac computers as the primary reasons for the downgrade. The latest sales checks revealed a softness in iPhone 15 sales, particularly in China and developed markets.
Barclays analysts also pointed out a potential slowdown in the growth of services, such as the App Store, for the coming year. Additionally, the note highlighted a perceived risk to services in 2024. Apple's 2023 was somewhat marred when the U.S. temporarily banned the sale of its newest Apple Watch due to patent issues.
Analyst Downgraded Rating and Price Target
- Barclays Analyst Tim Long Downgraded to Underweight rating and Price Target from $161 to $160.
Which Analyst has the best track record to show on AAPL?
Analyst Toni Sacconaghi (BERNSTEIN) currently has the highest performing score on AAPL with 62/70 (88.57%) price target fulfillment ratio. His price targets carry an average of $16.25 (9.09%) potential upside. Apple stock price reaches these price targets on average within 204 days.
Moderna: A Comeback Forecast
Moderna has experienced a turnaround as Oppenheimer analyst, Hartaj Singh, upgraded the stock to Outperform. Despite a decline in value over the past year due to diminishing interest in Covid-19 vaccine sales, analysts are optimistic about Moderna's future. With a revised price target of $142, they cite increased visibility on Covid-19 vaccine sales, a well-structured framework for operating expenses, and anticipate Moderna becoming a five-product commercial company by 2026, driven by catalysts in 2024 and 2025, including advancements in respiratory syncytial virus and influenza vaccines.
Oppenheimer analysts acknowledge a possible sales low-point in 2024 due to vaccine fatigue and market complexities but foresee a rebound in 2025 as education and awareness around Covid-19 continue to grow.
Moderna Surges as Analyst Upgrades Rating
- Oppenheimer analyst Hartaj Singh upgraded to Outperform rating and set a $142 price target.
Which Analyst has the best track record to show on MRNA?
Analyst Salveen Richter (GOLDMAN) currently has the highest performing score on MRNA with 13/18 (72.22%) price target fulfillment ratio. Her price targets carry an average of $153.47 (197.95%) potential upside. Moderna stock price reaches these price targets on average within 60 days.
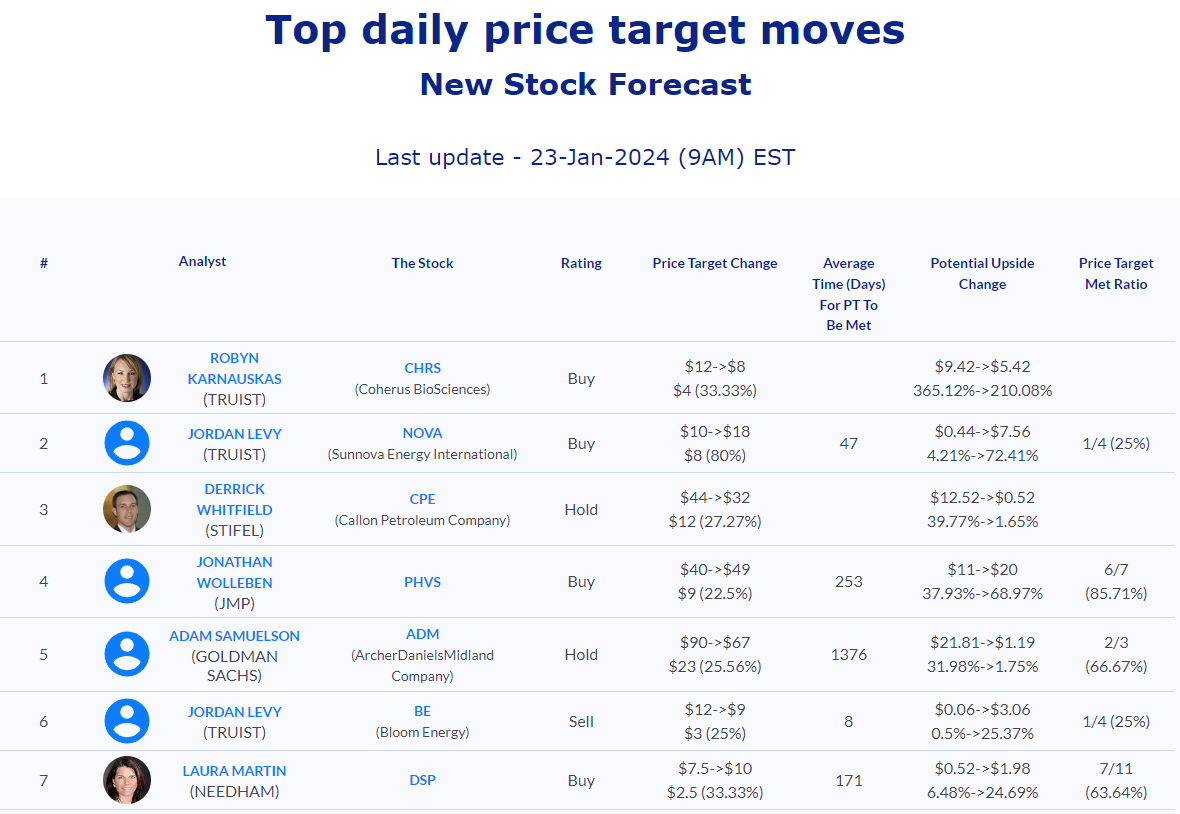
Daily stock Analysts Top Price Moves Snapshot

January 3, 2024:
By: Matthew Otto
Verizon Gains Traction on Wall Street with Upgraded Outlook for 2024
Verizon Communications has garnered attention on Wall Street due to an upgrade by KeyBanc Capital Markets. The telecom firm's shares were elevated from Sector Weight to Overweight. KeyBanc analyst, Brandon Nispel, titled 'New Year, New Verizon,' expresses optimism about the company's prospects in the wireless industry for 2024, highlighting an anticipated growth in earnings before interest, taxes, depreciation, and amortization exceeding the flat performance witnessed in the previous year. Nispel underscores Verizon's current valuation, noting that it trades at historically low levels with a forward enterprise value-to-EBITDA ratio of 6.25 times, compared to its three-year average of 6.9 times.
According to Nispel, the expected positive trajectory for Verizon in 2024 is grounded in factors such as the anticipation of above-average postpaid-phone subscriber growth, a decline in capital expenditure, and a perceived lack of competitive intensity within the sector. Nispel suggests that wireless carriers, including Verizon, appear content with their performance, contributing to a stable market environment.
Analysts Upgraded Rating for Verizon
- Keybanc analyst Brandon Nispel upgraded from Sector Weight to Overweight rating and set a $45 price target.
Which Analyst has the best track record to show on VZ?
Analyst Kannan Venkateshwar (BARCLAYS) currently has the highest performing score on VZ with 3/8 (37.5%) price target fulfillment ratio. His price targets carry an average of $4.31 (12.79%) potential upside. Verizon Communications stock price reaches these price targets on average within 193 days.
Lattice Semiconductor Shines Amidst Recent Underperformance
Lattice Semiconductor is positioned as a potential buying opportunity, according to Benchmark analyst David Williams. Despite a recent underperformance of 0.86% compared to its chip-industry peers, Williams raised his price target on Lattice stock to $95 from $70, reaffirming a Buy rating. The analyst is optimistic about the long-term prospects of Lattice's Avant product lineup, introduced in late 2022, anticipating a doubling of its contribution to the company's overall revenue by fiscal 2025. Despite challenges in the industrial and automotive markets, Williams believes Avant's higher price points and superior performance can drive an inflection in revenue and earnings as the industrial segment recovers.
In October, Lattice faced a decline following a disappointing forecast, citing softened demand and deteriorating order trends in Asia and Europe. However, Williams expresses increasing conviction in Lattice's execution, design momentum, margin sustainability, and expanding cash flow. Although Lattice has underperformed with a 5% rise over the past 12 months, compared to the 61% gain in the iShares Semiconductor exchange-traded fund, Williams sees the company as uniquely positioned for potential share appreciation in the evolving semiconductor landscape.
Analyst Upgrades Lattice to Buy and Raises Price Target
- Benchmark analyst David Williams upgraded to Buy and the price target from $70 to $95.
Which Analyst has the best track record to show on LSCC?
Analyst John Vinh (KEYBANK) currently has the highest performing score on LSCC with 6/8 (75%) price target fulfillment ratio. His price targets carry an average of $54.39 (97.81%) potential upside. Lattice Semiconductor stock price reaches these price targets on average within 43 days.
Daily stock Analysts Top Price Moves Snapshot

January 4, 2024:
By: Matthew Otto
Apple Settles Gift Card Scam Lawsuit
Apple has reportedly reached a settlement in a lawsuit accusing the tech giant of knowingly enabling scammers to exploit its gift cards. The lawsuit, filed in federal court in San Jose, California, alleges that Apple allowed fraudsters to take advantage of its gift card system, leading to significant financial losses for victims. The settlement terms, currently in the drafting stage, are expected to be presented to U.S. District Judge Edward Davila for preliminary approval.
The lawsuit, covering individuals in the United States who purchased gift cards redeemable on iTunes or the App Store between 2015 and July 31, 2020. This revolves around scammers convincing victims to buy Apple gift cards for various fabricated reasons. Despite warnings on the cards not to share codes, victims were coerced into providing them, resulting in substantial financial losses. The claim contends that Apple retained 30% of the stolen funds as a commission for knowingly converting the stolen codes into dollars. The settlement negotiations mark a crucial step in resolving the legal dispute and addressing the alleged consequences of Apple's role in the scam.
Mixed Signals: Apple Faces Analyst Divergence
- Piper Sandler analyst Harsh Kumar downgraded from Overweight to Neutral rating and the price target from $220 to $205.
- DA Davidson analyst Gil Luria initiated with a Neutral rating and a Price Target of $166.
Which Analyst has the best track record to show on AAPL?
Analyst Toni Sacconaghi (BERNSTEIN) currently has the highest performing score on AAPL with 62/70 (88.57%) price target fulfillment ratio. His price targets carry an average of $16.25 (9.09%) potential upside. Apple stock price reaches these price targets on average within 204 days.
First Solar and Cleantech Solar Collaborate for Sustainable Energy in Tamil Nadu
First Solar has inked a 15-year Power Purchase Agreement (PPA) with Cleantech Solar, marking a stride in renewable energy solutions for corporations in India and Southeast Asia. The agreement outlines Cleantech Solar's construction of 150 MW of photovoltaic solar and 16.8 MW of wind-generating assets in Tamil Nadu, India, contributing approximately 7.3 gigawatt-hours of clean electricity to First Solar's newly established 3.3-gigawatt vertically integrated solar manufacturing facility in the same region. Anticipated to be fully operational by the third quarter of 2024, these assets are expected to cover up to 70% of the manufacturing facility's power needs and displace nearly 7,000 kilotons of CO2 emissions over the PPA's lifespan.
First Solar's Tamil Nadu manufacturing plant aims to set global benchmarks for sustainable solar manufacturing, with net-zero water withdrawal, reliance on treated reverse osmosis water from the city's sewage treatment plant, and a pioneering photovoltaic solar recycling plant. Cleantech Solar will procure 150 MW of India-made Series 7 thin film solar panels from First Solar.
Analyst Upgrades Rating and Price Target
- Mizuho analyst Maheep Mandloi maintained a Buy rating and raised the price target from $188 to $196.
Which Analyst has the best track record to show on FSLR?
Analyst Vikram Bagri (CITI) currently has the highest performing score on FSLR with 2/5 (40%) price target fulfillment ratio. His price targets carry an average of $31.87 (20.81%) potential upside. First Solar stock price reaches these price targets on average within 7 days.
Rivian Downgraded Amid Market Challenges
Rivian has experienced a recent downgrade in its stock rating by Wolfe Research analyst Rod Lache, shifting from Buy to Hold. The company produced 57,232 units in 2023 compared to 24,337 in the previous year. However, Lache's apprehensions revolve around future demand uncertainties, questioning whether the growth observed in 2023, with 50,122 units sold, can be sustained as the company awaits the release of its R2 platform in 2026 and 2027. Despite growth rates, concerns linger regarding the saturation of the luxury EV market and the potential impact on Rivian's sales.
Americans purchased approximately 1.1 million EVs in 2023, reflecting a 45% increase from the previous year. Rivian's market share in the EV segment rose from 3% in 2022 to about 5% in 2023.
Analysts Downgrades Rivian to Peer Perform
- Wolfe Research analyst Rod Lache downgraded from Outperform to Peer Perform rating.
Which Analyst has the best track record to show on RIVN?
Analyst Mark Delaney (GOLDMAN SACHS) currently has the highest performing score on RIVN with 6/6 (100%) price target fulfillment ratio. His price targets carry an average of $1.26 (7.10%) potential upside. Rivian Automotive stock price reaches these price targets on average within 36 days.
Daily stock Analysts Top Price Moves Snapshot

January 5, 2024:
By: Matthew Otto
McDonald's Faces Business Impact Amidst Middle East Conflict and Boycotts
In the wake of the Israel-Hamas conflict. McDonald's CEO Chris Kempczinski has expressed concern over the meaningful business impact in several Middle Eastern markets and beyond due to grassroots boycott campaigns. The fast-food giant, along with other major Western chains like Starbucks, faces accusations of a pro-Israeli stance and alleged financial ties to Israel. The misinformation surrounding the brand is deemed disheartening and ill-founded, highlighting the challenges global corporations navigate amid polarized regional politics during times of war. McDonald's, along with other Western brands, is feeling the impact of boycotts in countries like Egypt and Jordan, with the movement gaining momentum in Muslim-majority Malaysia.
Analyst Views Diverge as Ratings and Price Targets Fluctuate
- Oppenheimer analyst Brian Bittner downgraded from Outperform to Perform.
- Stifel analyst Chris O'Cull maintained a Hold rating and raised the price target from $285 to $322.
- Evercore ISI analyst David Palmer reiterated an Outperform rating and raised the price target from $315 to $330.
Which Analyst has the best track record to show on MCD?
Analyst John Ivankoe (JPMORGAN) currently has the highest performing score on MCD with 19/19 (100%) price target fulfillment ratio. His price targets carry an average of $17.39 (6.67%) potential upside. McDonald’s stock price reaches these price targets on average within 229 days.
Simply Good Foods Q1: Steady Growth and Brand Focus
Simply Good Foods Company has reported a steady performance in its fiscal first quarter of 2024, with net sales reaching $308.7 million, reflecting a 2.6% increase from the previous year. The company's gross margin for the quarter stood at 37.3%, experiencing a 40 basis point rise primarily attributed to reduced ingredient and packaging costs. The adjusted EBITDA reached $62 million, marking a 2% increase compared to the same period in the prior year. The growth in retail takeaway, particularly in the nutritional snacking category, showcased an 8% surge.
Furthermore, the breakdown of retail takeaway within the IRI MULO + C-store universe revealed a 7.1% increase in Simply Good Foods' performance, driven by a 20% growth in Quest volume. Quest, in particular, demonstrated its momentum by achieving nearly $700 million in net sales for fiscal 2023. While Atkins exhibited a stabilized retail takeaway performance, its long-term potential remains a focal point. Overall, Simply Good Foods Company maintains a positive outlook for fiscal 2024, reaffirming its commitment to sustained long-term growth and shareholder value.
Analysts Bullish as Price Targets Soar
- DA Davidson analyst Brian Holland Maintained a Neutral rating and raised the price target from $42 to $44.
- Needham analyst Matt McGinley Reiterated a Buy rating and increased the price target from $42 to $45.
- Mizuho Securities analyst John Baumgartner Raised the price target from $42 to $50.
- Stifel analyst Matthew Smith Raised the price target to $48.
Which Analyst has the best track record to show on SMPL?
Analyst Faiza Alwy (DEUTSCHE BANK) currently has the highest performing score on SMPL with 6/6 (100%) price target fulfillment ratio. Her price targets carry an average of $2.29 (5.77%) potential upside. Simply Good Foods stock price reaches these price targets on average within 174 days.
Snowflake Downgraded Amid Analyst Concerns Over Valuation and AI Hype
Snowflake finds itself under the skeptical gaze of Monness Crespi Hardt analyst Brian White, who recently downgraded from Neutral to Sell. White emphasizes that Snowflake's revenue growth has decelerated for eight consecutive quarters, plummeting from 110% in the fiscal 2022 third quarter to 32% in the latest quarter. Additionally, Snowflake's operating margin stands at 9.8%, the lowest among White's enterprise software coverage, contributing to its unenviable position as the sector's most highly valued company.
White remains cautiously pessimistic about Snowflake's future prospects, pointing out the company's thin margins, rich valuation, and dynamic competition in the enterprise software landscape. Despite acknowledging Snowflake's long-term positioning in key secular trends like cloud computing, he believes the company faces challenges ahead, particularly amid an uncertain macroeconomic outlook. White contends that Snowflake's enthusiastic embrace of generative AI has been overstated by some investors, challenging the company's status as a pioneer or leading player in the generative-AI movement.
Analysts Offer Varied Perspectives with Mixed Ratings
- RBC Capital analyst Matthew Hedberg initiated an Outperform rating and a Price Target of $230.
- Monness, Crespi, Hardt analyst Brian White downgraded from Neutral to Sell and set a $160 price target.
Which Analyst has the best track record to show on SNOW?
Analyst Connor Murphy (CAPITAL ONE) currently has the highest performing score on SNOW with 2/2 (100%) price target fulfillment ratio. His price targets carry an average of $36.42 (22.97%) potential upside. Snowflake stock price reaches these price targets on average within 21 days.
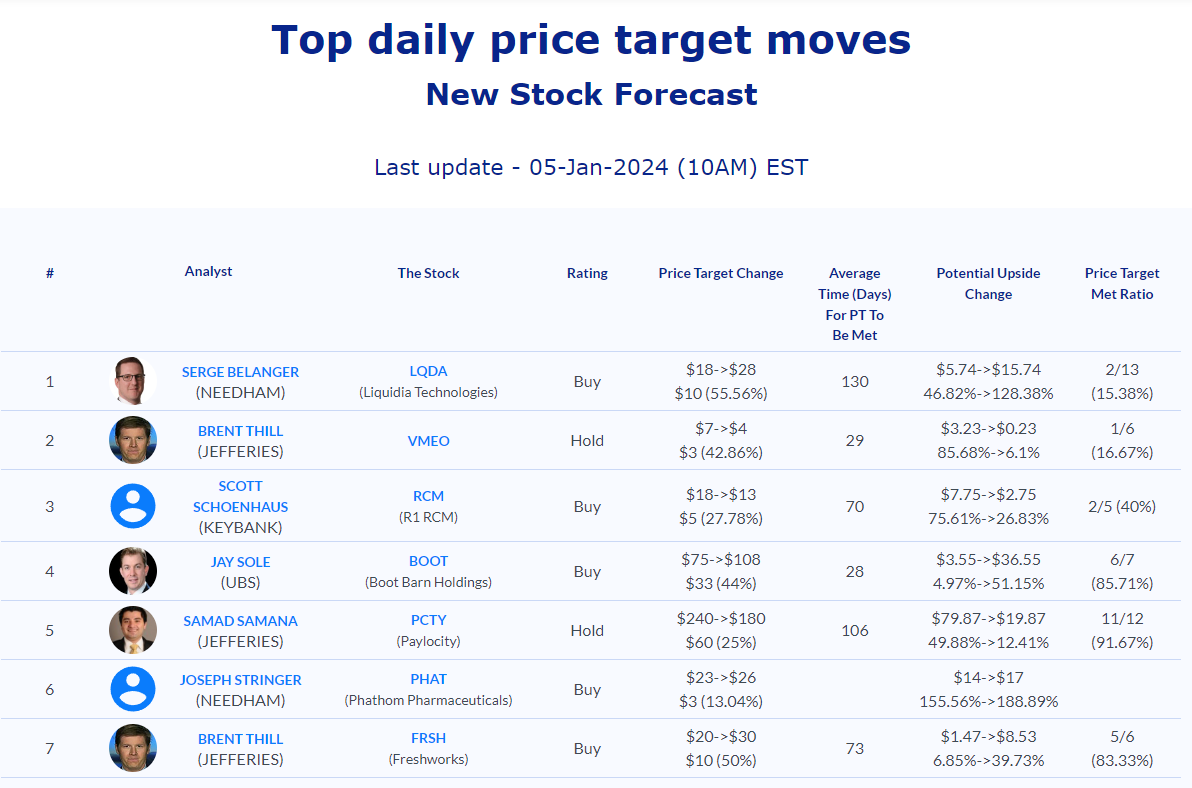
Daily stock Analysts Top Price Moves Snapshot
January 8, 2024:
By: Matthew Otto
Agilon Health Unveils Financial Projections for 2023 and 2024
Agilon Health has released detailed numerical insights into its financial expectations for the fiscal years 2023 and 2024. In the revised guidance for 2023, the company foresees Medicare Advantage membership ranging from 386,000 to 387,000, with total revenues projected between $4,295 million and $4,305 million. However, challenges have led to a shift in the adjusted EBITDA outlook, ranging from ($69) million to ($55) million, alongside geography entry costs estimated at $71 million. Looking forward to 2024, Agilon Health aims to expand its Medicare Advantage membership to 548,000 to 553,000, with an anticipated revenue range of $6,350 million to $6,420 million. The medical margin for 2024 is forecasted to be between $560 million and $600 million, supported by an adjusted EBITDA projection of $40 million to $60 million, and consistent geography entry costs of $70 million.
Analysts Downgrade Amid Market Shift
- Wolfe Research analyst Justin Lake shifted from Outperform to Peer Perform.
- Truist Securities analyst Jailendra Singh downgraded from Buy to Hold and the price target from $23 to $10.
- JP Morgan analyst Lisa Gill downgraded from Overweight to Neutral and the price target from $17 to $9.
- Benchmark analyst Bill Sutherland lowered the price target to $13.
- RBC Capital analyst Sean Dodge decreased the price target to $11.
- JMP Securities analyst Constantine Davides adjusted the price target to $11.
- Leerink Partners analyst Whit Mayo downgraded to Market Perform.
Which Analyst has the best track record to show on AGL?
Analyst George Hill (DEUTSCHE BANK) currently has the highest performing score on AGL with 4/11 (36.36%) price target fulfillment ratio. His price targets carry an average of $1 (9.09%) potential upside. Agilon Health stock price reaches these price targets on average within 35 days.
AMD's AI Growth with TSMC Collaboration
Reports from the United Daily News, industry sources in Taiwan suggest that AMD's foray into artificial intelligence is closely tied to multiple implementations of TSMC's advanced 5-nanometer and 6-nanometer semiconductor manufacturing processes. The integration of these processes through TSMC's cutting-edge packaging technologies positions AMD as a key player in the competitive landscape. Speculations indicate that major AI players, including Microsoft and Meta, may diversify and shift some of their computing hardware to AMD, potentially driving demand for AMD's MI300 accelerators to reach 400,000 units in 2024 and 600,000 units in 2025. The success of this projection is contingent on TSMC's ability to scale up its manufacturing capacity.
Analyst Updates Ratings and Raised Price Targets
- Melius Research analyst Ben Reitzes upgraded from Hold to Buy and set a price target of $188.
- Mizuho analyst Vijay Rakesh maintained a Buy rating and increased the price target from $130 to $162.
Which Analyst has the best track record to show on AMD?
Analyst Timothy Arcuri (UBS) currently has the highest performing score on AMD with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $27.17 (25.20%) potential upside. Advanced Micro Devices stock price reaches these price targets on average within 95 days.
Daily stock Analysts Top Price Moves Snapshot

January 9, 2024:
By: Matthew Otto
Accolade Beats Q3 Expectations, Raises Full-Year Guidance
Accolade has reported financial results for the fiscal third quarter ending November 30, 2023. The company showcased a 9% increase in revenue, reaching $99.4 million compared to $90.9 million in the same period in 2022. Despite posting a net loss of $21.1 million, the company demonstrated an improvement, marking a 47% reduction from the previous year's net loss of $39.9 million. Adjusted EBITDA standing at $(4.6) million, a 55% improvement from the $(10.2) million reported in 2022. Additionally, the company's Adjusted Gross Profit grew by 10%, reaching $46.0 million, and Adjusted Gross Margin stood at 46.3%, showcasing an increase from the previous year's 45.9%.
Looking ahead, Accolade remains optimistic about its fiscal performance, with an upward revision of guidance for fiscal year 2024. The company anticipates revenue between $411 million and $415 million, expecting approximately 20% growth. Adjusted EBITDA is projected to range between $(6) million and $(10) million for the fiscal year ending February 29, 2024. Furthermore, the company is affirming preliminary guidance for fiscal year 2025, predicting a continued revenue growth of around 20%, with Adjusted EBITDA anticipated to be between 2% and 4% of revenue.
Analysts Bullish as Price Targets Surge Following Performance
- Piper Sandler analyst Jessica Tassan maintained an Overweight rating and raised the price target from $12 to $15.
- Wells Fargo analyst Stan Berenshteyn reiterated an Equal-Weight rating and increased the price target from $10 to $12.
- Raymond James analyst John Ransom remained with an Outperform rating and upgraded the price target from $12 to $16.
- Truist Securities analyst Jailendra Singh raised the price target to $16.
Which Analyst has the best track record to show on ACCD?
Analyst Jessica Tassan (PIPER SANDLER) currently has the highest performing score on ACCD with 2/2 (100%) price target fulfillment ratio. Her price targets carry an average of $4.03 (50.56%) potential upside. Accolade stock price reaches these price targets on average within 19 days.
Netflix's Uncertain Future: Citi Analysts Issue Caution
Citi analyst Jason Bazinet has downgraded Netflix from Buy to Neutral. Bazinet points to three potential risks: optimistic 2024 revenue estimates, the likelihood of content investments exceeding expectations in 2025, and the possibility of significant acquisitions. These considerations come at a juncture when Netflix is anticipated to have over $8 billion in net cash by 2025, opening avenues for strategic moves, particularly in the gaming sector through potential acquisitions.
While Citi's stance introduces a note of caution, other industry analysts maintain an optimistic outlook. J.P. Morgan analysts, for instance, anticipate nearly 15% average revenue growth for Netflix in 2024 and 2025. As Netflix continues to navigate a competitive market, characterized by evolving content demands, its future trajectory remains a focal point for investors.
Analysts Divergent Views on Netflix Future Performance
- Goldman Sachs analyst Eric Sheridan maintained a Neutral rating and raised the price target from $400 to $500.
- BMO Capital analyst Brian Pitz initiated an Outperform rating and set a Price Target of $566.
- Citigroup analyst Jason Bazinet downgraded from Buy to Neutral and set a $500 price target.
Which Analyst has the best track record to show on NFLX?
Analyst Benjamin Swinburne (MORGAN STANLEY) currently has the highest performing score on NFLX with 40/46 (86.96%) price target fulfillment ratio. His price targets carry an average of $63.88 (13.14%) potential upside. Netflix stock price reaches these price targets on average within 171 days.
Birmingham Amazon Workers Strike for Fair Pay
Amazon's new distribution center in Birmingham, England, workers have voted to join the ongoing strike over pay and working conditions, according to the GMB trade union. Despite Amazon's assurance that the upcoming strike on January 25 would cause zero disruption to customers, around 100 employees at the warehouse are set to participate. The GMB, not formally recognized by the e-commerce giant, emphasized the need for union recognition and an end to what they term as poverty pay.
Amazon, which employs 75,000 people in Britain, has faced similar challenges in the past year. Workers is staging strikes at another warehouse in Coventry. The company asserts its commitment to addressing the concerns, stating plans to raise the minimum starting pay to £12.30 to £13 ($16 to $17) an hour by April, surpassing the upcoming minimum wage in Britain set at £11.44 ($14.60).
Analysts Bullish on Amazon: Buy Ratings and Raised Targets
- Stifel analyst Mark Kelley maintained a Buy rating and raised the price target from $173 to $175.
- BMO Capital analyst Brian Pitz initiated an Outperform rating and a Price Target of $200.
Which Analyst has the best track record to show on AMZN?
Analyst Barton Crockett (ROSENBLATT) currently has the highest performing score on AMZN with 7/9 (77.78%) price target fulfillment ratio. His price targets carry an average of $57.26 (44.83%) potential upside. Amazon.com stock price reaches these price targets on average within 113 days.
Daily stock Analysts Top Price Moves Snapshot

January 10, 2024:
By: Matthew Otto
Microsoft's AI Advancement in Battery Tech
In a groundbreaking collaboration with the Pacific Northwest National Laboratory, Microsoft has successfully employed artificial intelligence to accelerate the identification of a potential battery material that could reduce lithium requirements by 70%. The innovative approach, combining AI models trained on molecular science data and traditional scientific supercomputers, allowed Microsoft to narrow down over 32 million possibilities to 18 candidates. The PNNL scientists are now engaged in evaluating these candidates to determine their suitability for mass production. This technology could reduce the reliance on expensive and geopolitically concentrated lithium, replacing it with sodium, a more abundant and cost-effective element. The implications extend beyond battery technology, with potential applications in areas such as automotive and energy grids.
Analysts Raises Microsoft Price Target
- BMO Capital analyst Keith Bachman maintained an Outperform rating and raised the price target from $400 to $420.
Which Analyst has the best track record to show on MSFT?
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on MSFT with 22/24 (91.67%) price target fulfillment ratio. His price targets carry an average of $68.63 (21.69%) potential upside. Microsoft stock price reaches these price targets on average within 92 days.
Apple Faces Third Downgrade Amid Growth and Regulatory Concerns
Apple faced its third downgrade from investment firm Redburn. Analyst James Cordwell revised the rating from buy to neutral, emphasizing a limited upside in the coming years, with concerns about the March quarter potentially impacting iPhone growth. Additionally, rising regulatory risks, especially in Europe regarding app store policies, add to the apprehension. With Barclays and Piper Sandler having previously downgraded Apple over worries about iPhone sales, the cumulative effect has prompted caution among analysts, as reflected in Redburn's recent move.
The market sentiment towards Apple seems to be experiencing a shift, with valuation concerns playing a significant role. Redburn's downgrade follows a trend where Apple's price-to-earnings ratio has surpassed that of Nike for an extended period, prompting Cordwell to highlight a full valuation.
Analysts Downgrades: Cautious on Growth
- Redburn Atlantic analyst James Cordwell downgraded from Buy to Neutral rating and maintained a $200 price target.
- KeyBanc analyst Brandon Nispel maintained a Sector Weight rating.
Which Analyst has the best track record to show on AAPL?
Analyst Toni Sacconaghi (BERNSTEIN) currently has the highest performing score on AAPL with 62/70 (88.57%) price target fulfillment ratio. His price targets carry an average of $16.25 (9.09%) potential upside. Apple stock price reaches these price targets on average within 204 days.
Daily stock Analysts Top Price Moves Snapshot

January 11, 2024:
By: Matthew Otto
Juniper Networks' $14B Acquisition by HPE Reshapes Networking Future
Juniper Networks finds itself at the center of a transformative $14 billion all-cash acquisition by Hewlett Packard Enterprise, marking a development in the U.S. networking market. This strategic move positions Juniper and its suite of networking solutions as a pivotal player in the industry's evolution.
HPE’s acquisition underscores the confidence in Juniper’s potential, with a keen eye on integrating Juniper’s Mist offering, known for its innovative use of artificial intelligence to enhance wireless access. Mist's capabilities include real-time packet capture for efficient issue resolution, location-based services for accurate positioning and tracking, and self-healing features that automatically detect and mitigate network anomalies. Additionally, Mist facilitates user engagement through personalized experiences and analytics, making it a comprehensive and intelligent platform for organizations seeking to optimize and streamline their wireless networks.
Mixed Analyst Sentiments for Juniper Networks
- Jefferies analyst George Notter downgraded from Buy to Hold rating and raised the price target from $35 to $40.
- Morgan Stanley analyst Meta Marshall upgraded from Underweight to Equal-Weight rating and set a $40 price target.
- Barclays analyst Tim Long downgraded from Overweight to Equal-Weight rating.
- Raymond James analyst Simon Leopold shifted from Outperform to Market Perform.
Which Analyst has the best track record to show on JNPR?
Analyst Samik Chatterjee (JPMORGAN) currently has the highest performing score on JNPR with 10/11 (90.91%) price target fulfillment ratio. His price targets carry an average of $2.74 (10.43%) potential upside. Juniper Networks stock price reaches these price targets on average within 280 days.
KB Home Q4 2023 Performance Amid Market Challenges
KB Home reported financial results for the fourth quarter of fiscal year 2023, with total revenues reaching $1.7 billion compared to consensus of $1.62 billion. Diluted earnings per share standing at $1.85. The company's outperformance in closings, totaling over 3,400 homes, was attributed to improved build times and a robust backlog of committed buyers. KB Home delivered more than 13,200 homes throughout 2023, generating revenues of $6.4 billion and achieving diluted earnings above $7 per share. Noteworthy operational achievements include a reduction in build times, resulting in an average savings of about $18,000 per home compared to peak costs in August 2022.
KB Home's mortgage joint-venture, KBHS Home Loans, showcased 87% of mortgages funded during the quarter financed through the joint venture. The company's land position stood at approximately 56,000 lots at quarter-end, with 40,800 lots owned. The company's ending backlog for the first quarter of 2024 comprises more than 5,500 homes, valued at approximately $2.7 billion.
Analyst Mixed Ratings Reflect Diverse Market Perspectives
- Goldman Sachs analyst Susan Maklari maintained a Neutral rating and raised the price target from $55 to $61.
- Seaport Global analyst Kenneth Zener downgraded from Buy to Neutral.
- Wedbush analyst Jay McCanless raised the price target to $60.
- Evercore ISI analyst Stephen Kim reiterated an Outperform rating and increased the price target to $76.
- RBC Capital analyst Mike Dahl increased the price target to $63.
- Deutsche Bank analyst Joe Ahlersmeyer raised the price target to $50.
Which Analyst has the best track record to show on KBH?
Analyst Deepa Raghavan (WELLS FARGO) currently has the highest performing score on KBH with 2/2 (100%) price target fulfillment ratio. Her price targets carry an average of $3.89 (7.61%) potential upside. KB Home stock price reaches these price targets on average within 31 days.
Meta Fined $160,000 Daily by Turkish Competition Authority
The Turkish Competition Authority has announced a daily fine of $160,000 on Meta Platforms. This penalty is a consequence of Meta's failure to provide sufficient documentation related to a previous investigation into the online video advertising market in 2022.
As part of the investigation, Meta was required to submit a document outlining compliance measures to address its violation of the law and to restore competition in the market. The Turkish Competition Board found Meta's submitted compliance measures inadequate and, as a result, decided to impose a daily fine starting from December 12. This fine will continue until Meta submits a final compliance solution that meets the board's requirements.
The Turkish Competition Authority had already fined Meta $11.6 million for violating competition law last 2022. Meta has expressed disagreement with the Turkish Competition Authority's findings but has stated its commitment to cooperating with them to resolve the matter promptly.
Analysts Raises Price Target and Maintained its Rating
- Mizuho analyst James Lee maintained a Buy rating and raised the price target from $400 to $470.
Which Analyst has the best track record to show on META?
Analyst Thomas Champion (PIPER SANDLER) currently has the highest performing score on META with 16/19 (84.21%) price target fulfillment ratio. His price targets carry an average of $66.65 (23.11%) potential upside. Meta Platforms stock price reaches these price targets on average within 179 days.
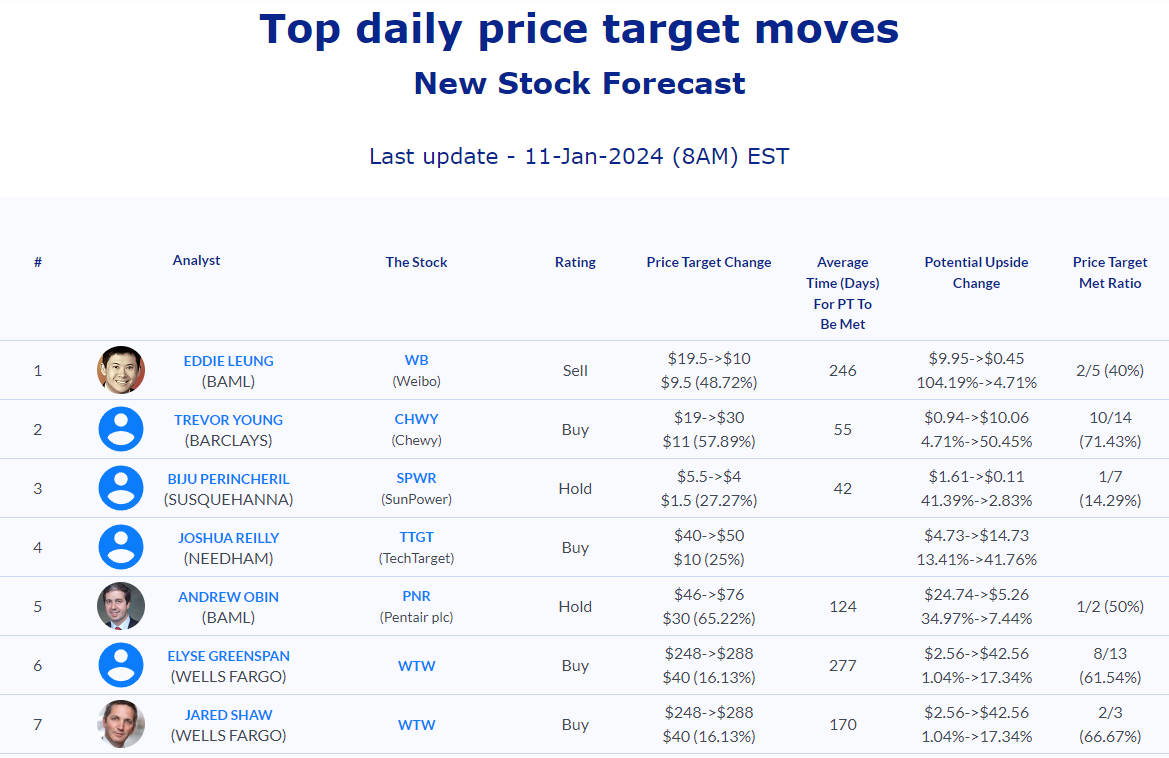
Daily stock Analysts Top Price Moves Snapshot
January 12, 2024:
By Matthew Otto
Coinbase: ETF Approval Sparks Volatility and Opportunities
Coinbase Global experienced a rollercoaster of market activity as the Securities and Exchange Commission's approval of the first spot Bitcoin exchange-traded funds sent shockwaves through the cryptocurrency broker's stock. Analysts remain divided on the outlook for Coinbase, with some, like Moshe Katri of Wedbush, optimistic about the company's potential to benefit from its role as a custodian for the approved ETFs, while others, including Dan Dolev from Mizuho Securities, express skepticism, citing concerns about potential fee pressures and increased competition in the evolving cryptocurrency landscape.
The SEC's nod to Bitcoin ETFs is seen as a pivotal moment that could usher in a fresh wave of investor interest in cryptocurrencies. The approval is anticipated to attract retail and institutional investors to platforms like Coinbase. The regulatory green light provides a regulated avenue for investors to engage with Bitcoin, potentially leading to increased competition, fee pressures, and a reshuffling of the crypto capital landscape.
Analyst Perspectives Diverge as Price Targets Vary
- Wedbush analyst Moshe Katri maintained an Outperform rating and raised the price target from $110 to $180.
- Mizuho Securities analyst Dan Dolev set an Underperform rating and a $54 price target.
- BofA Securities analyst Jason Kupferberg raised the price target from $66 to $79.
Which Analyst has the best track record to show on COIN?
Analyst Richard Repetto (PIPER SANDLER) currently has the highest performing score on COIN with 11/13 (84.62%) price target fulfillment ratio. His price targets carry an average of $-8.04 (-9.13%) potential downside. Coinbase Global stock price reaches these price targets on average within 154 days.
Mastercard's Small Business AI: Empowering Entrepreneurs Globally
Mastercard is spearheading a groundbreaking initiative to bolster small businesses worldwide through the development of Mastercard Small Business AI. Data indicates that eight out of ten small businesses operate without employees and 88% recognizing the value of mentorship. Mastercard Small Business AI endeavors to cater to the unique challenges faced by entrepreneurs. In addition to Mastercard's extensive repository of content, a diverse global media coalition, including Blavity Media Group, Group Black, Newsweek. TelevisaUnivision, will contribute licensed business content to the Generative AI tool, fostering a wealth of resources for small business owners.
The Mastercard Small Business AI tool is designed to address the overwhelming nature of today's data-driven business environment. Aimed at providing always-on assistance, the tool is particularly relevant for the vast majority of small businesses operating without a dedicated workforce. The Generative AI features incorporated into the tool aim to create a conversational and inclusive user experience, ensuring that entrepreneurs receive tailored advice and guidance. With 53 million U.S. consumers reached across linear and digital platforms, TelevisaUnivision joins the global media coalition alongside other prominent partners, contributing to the tool's diverse content offering.
Analysts Offer Varied Views, Adjusting Ratings and Price Targets
- Goldman Sachs analyst Matthew O'Neill maintained a Buy rating and increased the price target from $433 to $482.
- Oppenheimer analyst Dominick Gabriele upgraded from Perform to Outperform and set a new price target of $510.
Which Analyst has the best track record to show on MA?
Analyst Josh Beck (KEYBANK) currently has the highest performing score on MA with 13/15 (86.67%) price target fulfillment ratio. His price targets carry an average of $46.79 (11.90%) potential upside. Mastercard stock price reaches these price targets on average within 145 days.
Bank of America Faces Earnings Decline, Struggles with One-Time Charges in Q4 2023
Bank of America reported declining fourth-quarter earnings. The bank's adjusted earnings per share stood at 70 cents, surpassing the expected 68 cents. Revenue reached $22 billion, although the comparability to analyst estimates remains unclear. The decline in net income to $3.1 billion, down more than 50% from a year ago. Was attributed to significant one-time charges, including a $1.6 billion pretax charge linked to the transition away from the London Interbank Offered Rate. Additionally, a special $2.1 billion fee from the Federal Deposit Insurance Corp., tied to the failures of Silicon Valley Bank and Signature Bank, further impacted the bank's financials.
Revenue from consumer banking experienced a 4% dip to $10.3 billion. Sales and trading revenue saw a 3% increase, reaching $3.6 billion. The provision for credit losses amounted to $1.1 billion, reflecting an increase of $12 million from the same quarter last year. The bank's net interest income decreased by 5% to $13.9 billion, impacted by higher deposit costs and lower deposit balances, offsetting higher asset yields. Bank of America, once anticipated to benefit from higher interest rates, faced challenges due to investments in low-yielding, long-dated securities during the Covid pandemic, which lost value as interest rates climbed.
Analysts Boosts Price Targets for Bank of America
- JPMorgan analyst Vivek Juneja maintained an Overweight rating and increased the price target from $34 to $35.
- Jefferies analyst Ken Usdin reiterated a Hold rating and raised the price target from $29 to $36.
Which Analyst has the best track record to show on BAC?
Analyst Scott Siefers (PIPER SANDLER) currently has the highest performing score on BAC with 2/3 (66.67%) price target fulfillment ratio. His price targets carry an average of $-1.11 (-3.88%) potential downside. Bank of America stock price reaches these price targets on average within 4 days.
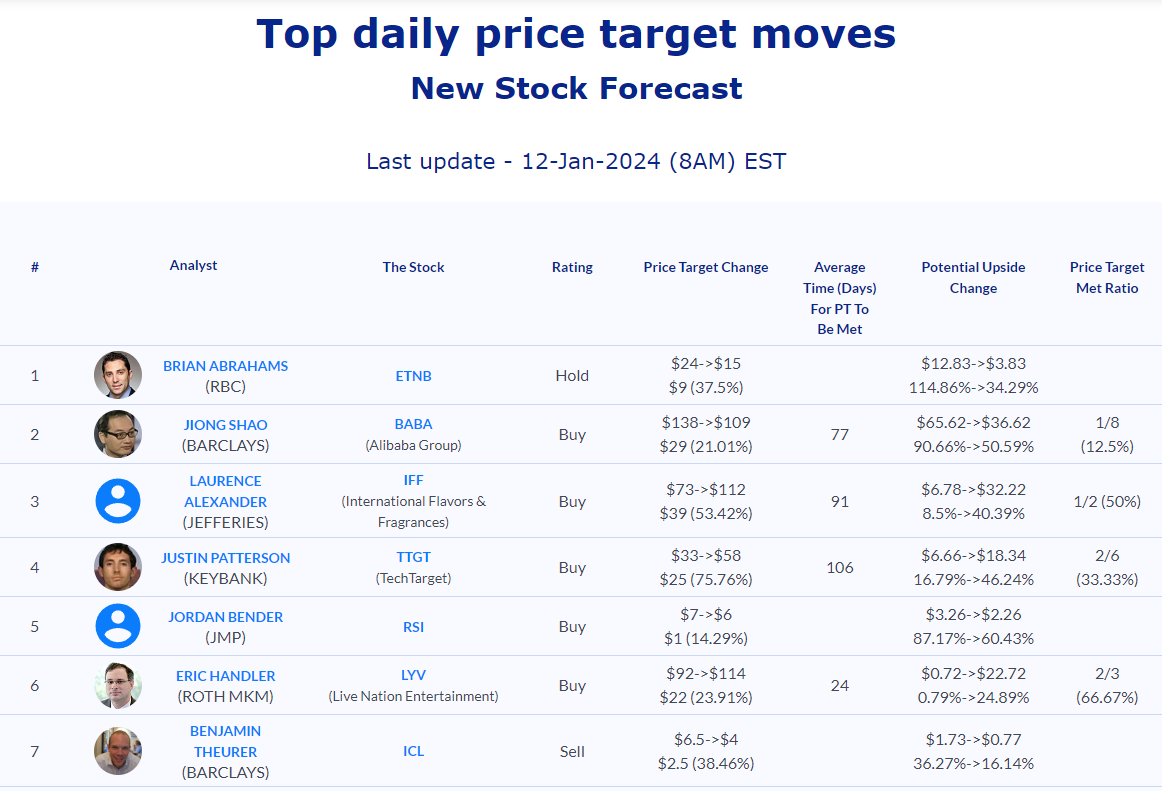
Daily stock Analysts Top Price Moves Snapshot
January 16, 2024:
By: Matthew Otto
Albertsons-Kroger Merger Faces Delay Amid Regulatory Scrutiny
Albertsons faces a setback in its proposed $24.6 billion merger with Kroger as the companies announce a delay in the deal closure to the first half of Kroger's fiscal 2024, rather than the initially anticipated early 2024. The merger, first revealed in October 2022, has triggered concerns among U.S. lawmakers and prompted an investigation by the Federal Trade Commission (FTC) due to potential antitrust issues. Critics worry that the merger could result in adverse consequences for consumers, including higher prices, store closures, and job losses. Albertsons, alongside Kroger, pledges to invest $500 million to reduce prices and an additional $1.3 billion to enhance the overall customer experience. Albertsons is actively engaged in ongoing discussions with regulators, including the FTC and state attorneys general, as they navigate the regulatory landscape and work towards securing approval for the merger.
Analysts Maintain Positive Ratings for Albertsons
- RBC Capital analyst Steven Shemesh reiterated an Outperform rating and a $24 price target.
- Tigress Financial analyst Ivan Feinseth maintained a Buy rating and a $27 price target.
Which Analyst has the best track record to show on ACI?
Analyst Simeon Gutman (MORGAN STANLEY) currently has the highest performing score on ACI with 6/10 (60%) price target fulfillment ratio. His price targets carry an average of $3.79 (18.75%) potential upside. Albertsons stock price reaches these price targets on average within 119 days.
Vertex Withdraws Tender Offer for Pagero
Vertex has announced the withdrawal of its public tender offer for 100% of the shares of Pagero Group AB. This decision comes in light of two competing offers and the acquisition of more than 10 percent of Pagero's shares by a rival bidder. The cancellation of the issuance of a new series of Convertible Preferred Stock in the amount of $500 million is also confirmed, and Pagero shareholders who had committed to Vertex's tender offer have been released from their obligations.
Divergent Analyst Views on Vertex
- Citigroup analyst Steven Enders maintained a Neutral rating and lowered the price target from $29 to $27.
- Needham analyst Joshua Reilly reiterated a Buy rating and a $35 price target.
Which Analyst has the best track record to show on VERX?
Analyst Stan Zlotsky (MORGAN STANLEY) currently has the highest performing score on VERX with 8/9 (88.89%) price target fulfillment ratio. His price targets carry an average of $2.83 (10.42%) potential upside. Vertex stock price reaches these price targets on average within 59 days.
Boeing Downgraded Amid FAA Scrutiny
Boeing faces a challenging start to 2024 as Wells Fargo analyst Matthew Akers downgrades the aerospace giant's shares to Hold, accompanied by a revised price target of $225 per share. The downgrade is triggered by the January 5 incident involving an Alaska Air-operated 737 MAX 9. The FAA promptly grounded 171 MAX 9 jets after an emergency door plug blew out midair, leading to an emergency landing. This event, coupled with the FAA's subsequent announcement of an audit on the Boeing 737-9 MAX production line and its suppliers, has intensified concerns about potential production and delivery delays. Analysts highlight the significant risk posed by Boeing's historical quality issues, making a favorable audit outcome less probable and adding to the headwinds faced by the company.
Boeing's recent woes compound the troubled history of the 737 MAX series. Two deadly crashes in 2019 linked to a software design flaw, the aircraft faced a global grounding until November 2020. In 2023, Boeing disclosed quality problems in 737 MAX parts supplied by Spirit AeroSystems, though these issues did not result in accidents or further groundings. Despite Wall Street's initial optimism for Boeing in 2024, with projections of delivering approximately 700 planes, up from 530 in 2023, and an expected increase in free cash flow from $3 billion to $6 billion, the recent events have prompted a reevaluation.
Analyst Downgrades to Equal-Weight and Slashes Price Target
- Wells Fargo analyst Matthew Akers downgraded from Overweight to Equal-Weight and the price target from $280 to $225.
Which Analyst has the best track record to show on BA?
Analyst Ronald Epstein (BAML) currently has the highest performing score on BA with 18/26 (69.23%) price target fulfillment ratio. His price targets carry an average of $66.25 (28.34%) potential upside. Boeing stock price reaches these price targets on average within 201 days.
Daily stock Analysts Top Price Moves Snapshot

January 17, 2024:
By: Matthew Otto
Allakos Restructuring Plan and Focus on AK006 Clinical Development
Allakos announced a strategic restructuring plan to optimize resources and concentrate efforts on advancing its lead candidate, AK006. The company will discontinue activities related to lirentelimab across various functions, including clinical, manufacturing, research, and administration. This decision will result in a workforce reduction of approximately 50%. With a focus on enhancing its financial position, the company aims to extend its cash runway into mid-2026. As of the end of Q4 2023, Allakos reported approximately $171 million in cash, cash equivalents, and investments. The restructuring plan is anticipated to impact the company's operating activities, with estimated 2024 net cash usage projected between $85 million to $90 million, excluding lirentelimab closeout, severance, and other costs.
Analyst Downgrades Amid Restructuring News
- Barclays analyst Carter Gould maintained an Underweight rating and lowered the price target from $1.5 to $1.
- Jefferies analyst Kevin Strang downgraded from Buy to Hold and the price target from $6 to $1.5.
- JMP Securities analyst Jonathan Wolleben lowered the price target to $3.
Which Analyst has the best track record to show on ALLK?
Analyst Tim Lugo (WILLIAM BLAIR) currently has the highest performing score on ALLK with 1/1 (100%) price target fulfillment ratio. His price targets carry an average of $32.69 (83.16%) potential upside. Allakos stock price reaches these price targets on average within 358 days.
Challenges and Resilience: Morgan Stanley's Q4 Performance
Morgan Stanley faced a downturn in response to a fourth-quarter profit decrease of $535 million. The bank's net income for the three months ended December 31 dropped to $1.5 billion, or 85 cents per diluted share, a decline from $2.2 billion, or $1.26 per diluted share, reported during the same period the previous year. These financial challenges were exacerbated by various charges, including $286 million allocated to refill a government deposit insurance fund, $249 million in legal charges to settle a government probe, and an additional $405 million in mark-to-market losses on corporate loans, including financing for Elon Musk's purchase of Twitter.
Despite the setbacks, Morgan Stanley's investment banking revenue managed to rise by 5% in the fourth quarter compared to the previous year. However, wealth management margins, currently in the mid-20% range, fell short of market expectations. The overall revenue slightly exceeded analysts' expectations, but the adjusted profit came in at 99 cents per share, including the impact of the government's special assessment charge, below the expected $1.01 per share.
Analyst Views Diverge on Morgan Stanley as Price Targets Shift
- BMO Capital's James Fotheringham maintained an Outperform rating and raised the price target from $106 to $107.
- Keefe, Bruyette & Woods' David Konrad downgraded from Outperform to Market Perform and the price target from $102 to $91.
- JP Morgan's Kian Abouhossein downgraded from Overweight to Neutral and the price target from $94 to $87.
- Oppenheimer's Chris Kotowski lowered the price target to $106.
Which Analyst has the best track record to show on MS?
Analyst Kian Abouhossein (JPMORGAN) currently has the highest performing score on MS with 3/4 (75%) price target fulfillment ratio. His price targets carry an average of $1.94 (2.11%) potential upside. Morgan Stanley stock price reaches these price targets on average within 49 days.
FB Financial Q4 2023: Growth and Strategic Outlook
FB Financial Corporation reported its fourth-quarter 2023 earnings with a revenue of $116.43 million versus the consensus estimate of $122.39 million. The company's earnings per share stood at $0.63, with adjusted EPS at $0.77 which is better than the analyst estimate of $0.70. The company achieved a compound annual growth rate of 13.8% in tangible book value per share, excluding the impact of accumulated other comprehensive income since its IPO in September 2016. The company's balance sheet was highlighted by a tangible common equity to tangible assets ratio of 9.7%. Additionally, FB Financial liquidity has a ratio of loans plus securities to deposits at 103%, along with access to $7.1 billion in available liquidity sources.
Despite economic challenges, the company reported a 5.2% annualized loan growth in the fourth quarter, driven by commercial and industrial as well as commercial real estate portfolios. Looking ahead, FB Financial remains optimistic about mid-single-digit loan growth in 2024, supported by selective financing and customer deposit growth.
Analyst Updates: Downgrade and Price Adjustments
- Hovde Group's Brett Rabatin downgraded from Outperform to Market Perform and set a new price target of $40.
- Stephens & Co.'s analyst Matt Olney maintained an Equal-Weight rating and lowered the price target from $45 to $41.
Which Analyst has the best track record to show on FBK?
Analyst Kevin Fitzsimmons (D.A. DAVIDSON) currently has the highest performing score on FBK with 2/2 (100%) price target fulfillment ratio. His price targets carry an average of $3.34 (9.92%) potential upside. FB Financial stock price reaches these price targets on average within 120 days.
Daily stock Analysts Top Price Moves Snapshot
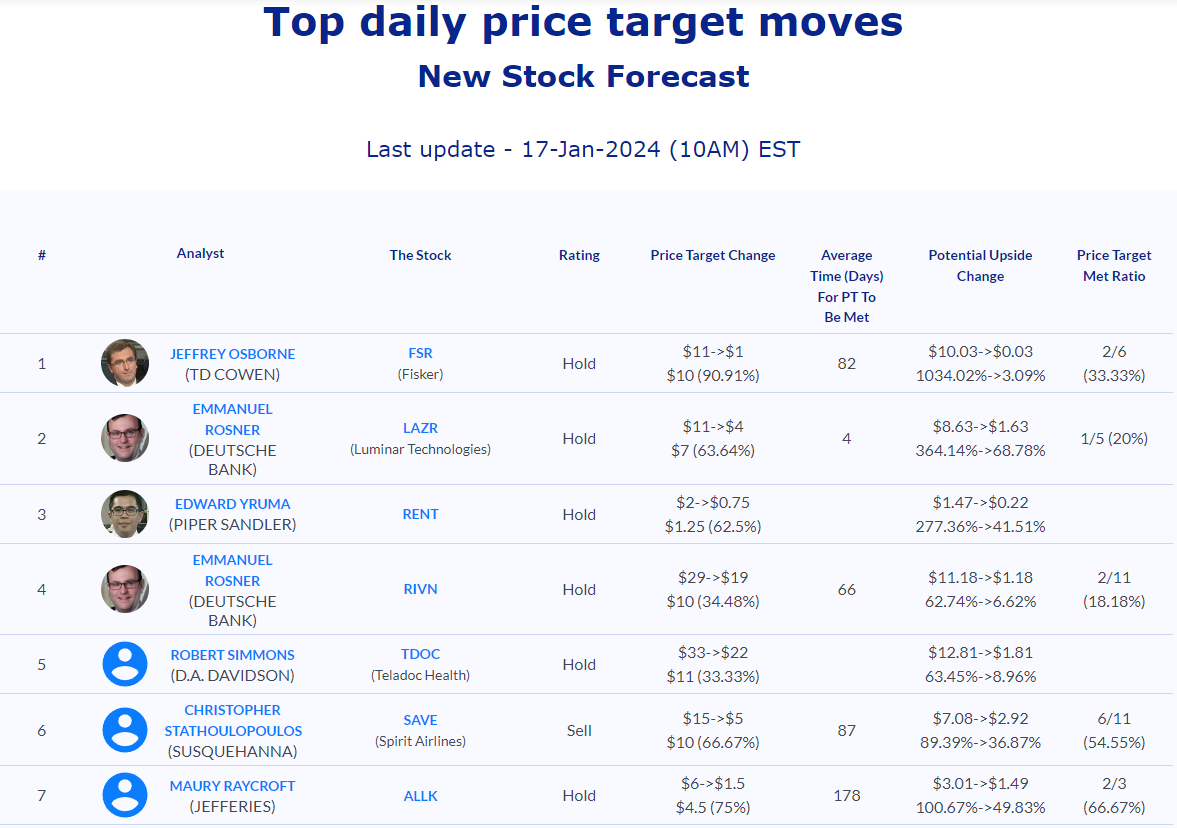
January 18, 2024:
By: Matthew Otto
Citizens Financial Group Reports Financials and Strategic Outlook for 2024
Citizens Financial Group reported financial performance for the fourth quarter and full year of 2023. The bank's capital position showed a CET1 ratio of 10.6%, adjusted for AOCI of approximately 9%, and a tangible common equity ratio of 6.7%. Liquidity reached an all-time high, featuring a loan-to-deposit ratio of 82%, a pro forma Category 1 LCR of 117%, and 156% liquidity coverage for uninsured deposits. Citizens Financial Group reported a 13.5% underlying return on tangible common equity for the full year, with a 95% return of capital to shareholders.
Looking ahead to 2024, Citizens Financial Group aims to limit underlying expense growth to approximately 1% to 1.5% in 2024, with a strategic emphasis on technology, digital initiatives, and artificial intelligence. The bank's medium-term goals include achieving a return on tangible common equity of 16% to 18% and maximizing contributions from private bank buildout.
Analyst Perspectives Diverge on Citizens Financial Group's Outlook
- RBC Capital analyst Gerard Cassidy maintained an Outperform rating and raised the price target from $33 to $35.
- Wedbush analyst David Chiaverini reiterated a Neutral stance and lowered the price target from $36 to $35.
- Baird analyst David A. George lowered the price target to $42.
- BofA Securities analyst Ebrahim Poonawala raised the price target to $37.
Which Analyst has the best track record to show on CFG?
Analyst Bill Carcache (WOLFE) currently has the highest performing score on CFG with 3/4 (75%) price target fulfillment ratio. His price targets carry an average of $-1.71 (-4.31%) potential downside. Citizens Financial Group stock price reaches these price targets on average within 41 days.
U.S. Bancorp Q4 2023 Financial Highlights
U.S. Bancorp reported its financial results for the fourth quarter of 2023. Earnings per share stood at $0.49, incorporating $0.50 per share of notable items. Excluding these, adjusted earnings per share amounted to $0.99, reflecting the bank's resilience amidst industry headwinds. Net revenue for the quarter, on an adjusted basis, reached $6.9 billion, contributing to the annual net revenue of $28.3 billion. Total loans experienced a 1.1% decline on a linked-quarter basis. The average deposit dropped by 1.9%, as the bank maintained a disciplined approach to deposit pricing. Tangible book value per share surged by 14.7% year-over-year. The common equity tier 1 capital ratio reached 9.9%, a 20 basis points increase in the quarter. A 150 basis points higher since the acquisition of Union Bank in 2022.
In terms of key performance metrics, the bank delivered a 19.6% return on tangible common equity in the fourth quarter, and a 21.7% return on tangible common equity for the entire year. Notable items, totaling $1.1 billion pre-tax or $780 million net of tax, had an impact on diluted earnings per share, reducing it by $0.50. These items included an FDIC special assessment charge of $734 million, merger and integration costs of $171 million, a charitable contribution of $110 million, and a balance sheet optimization charge of $118 million. Looking ahead, the bank expects net interest income for the first quarter of 2024 to range between $4.0 billion and $4.1 billion, with the full year 2024 net interest income projected to be consistent with the annualized fourth quarter 2023 level of approximately $4.14 billion, or slightly higher.
Analyst Perspectives: Mixed Ratings and Adjusted Price Targets
- RBC Capital analyst Gerard Cassidy Maintained an Outperform rating and raised the price target from $43 to $47.
- Oppenheimer analyst Chris Kotowski Reiterated an Outperform rating and lowered the price target from $60 to $59.
- Stephens analyst Terry McEvoy Kept an Equal Weight rating and lowered the price target from $49 to $47.
- Evercore ISI analyst John Pancari Maintained an In-Line rating and lowered the price target from $46 to $45.
Which Analyst has the best track record to show on USB?
Analyst Richard Ramsden (GOLDMAN SACHS) currently has the highest performing score on USB with 11/13 (84.62%) price target fulfillment ratio. His price targets carry an average of $-1.72 (-3.93%) potential downside. U.S. Bancorp stock price reaches these price targets on average within 411 days.
Schwab's Q4 2023: 47% Profit Drop Amid Rate Hikes
Charles Schwab reported a 47% decline in fourth-quarter profit, with net interest revenue dropping by 30% to $2.13 billion for the period ending December 31, 2023. The impact of the U.S. Federal Reserve's aggressive rate hikes was evident, as the company, heavily reliant on client deposits and uninvested cash balances, faced higher interest payments on deposits and debt. Schwab's average rate on deposits increased to 1.37% from 0.46% the previous year. The firm's strategic move to borrow from the Federal Home Loan Bank in the first half of 2023 resulted in an interest expense of $423 million, marking a fourfold increase from the prior year.
Asset management and administration fees experienced an 18% surge to $1.24 billion, driven by the management of mutual funds and exchange-traded funds. Schwab's reported profit stood at $1.05 billion, or 51 cents per share, in comparison to $1.97 billion, or 97 cents per share, in the corresponding period of the previous year.
Analyst Views Diverge: Target Price Adjustments Reflect Mixed Sentiments
- Barclays analyst Benjamin Budish maintained an Equal-Weight rating and lowered the price target from $68 to $64.
- Keefe, Bruyette & Woods analyst Kyle Voigt downgraded from Outperform to Market Perform and the price target from $75 to $70.
- Raymond James analyst Patrick O'Shaughnessy reiterated an Outperform rating and lowered the price target from $78 to $75.
- Jefferies analyst Daniel Fannon raised the price target to $85.
- JPMorgan analyst Kenneth Worthington lowered the price target to $83.
- BofA Securities analyst Craig Siegenthaler raised the price target from $54 to $58.
Which Analyst has the best track record to show on SCHW?
Analyst Benjamin Budish (BARCLAYS) currently has the highest performing score on SCHW with 12/14 (85.71%) price target fulfillment ratio. His price targets carry an average of $3.55 (6.64%) potential upside. Charles Schwab stock price reaches these price targets on average within 52 days.
Daily stock Analysts Top Price Moves Snapshot
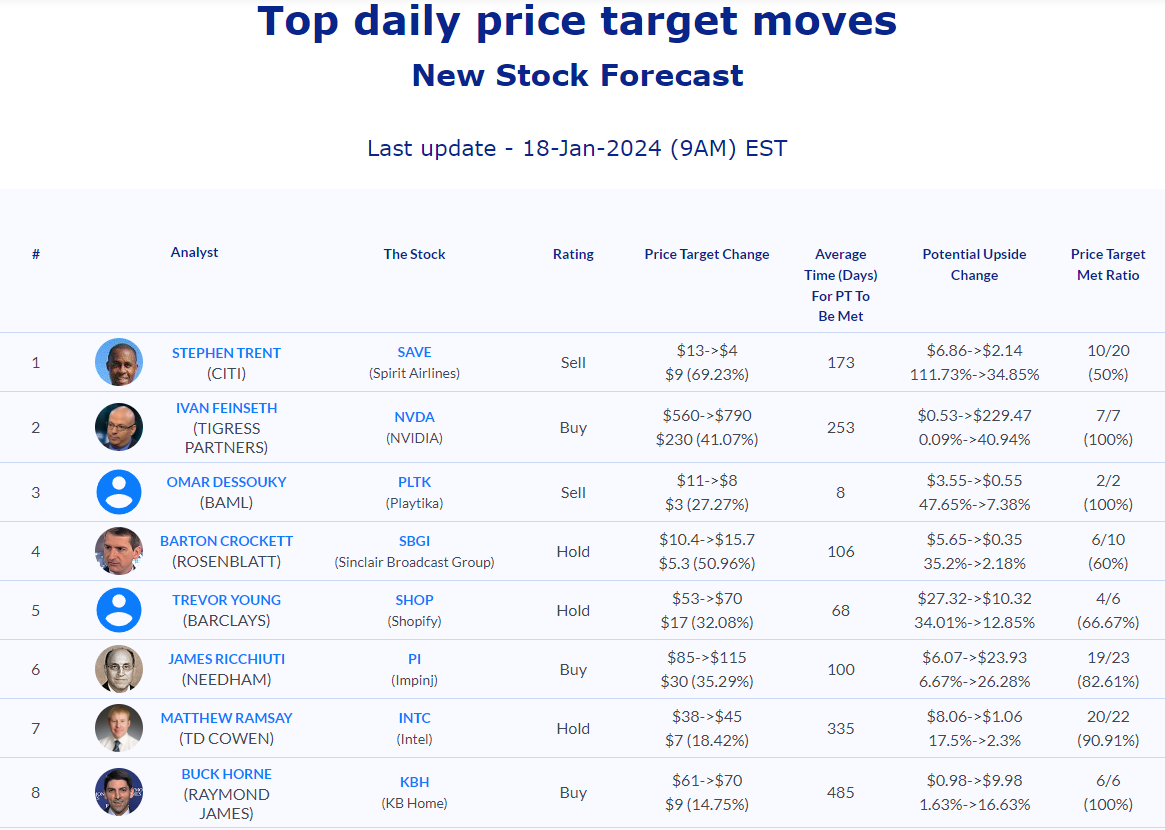
January 19, 2024:
By: Matthew Otto
Variety of Outlooks Surrounds Netflix Ahead of Earnings Report
As Netflix prepares to announce its fiscal fourth-quarter results, analysts are offering varied perspectives. Citi analyst Jason Bazinet takes a cautious stance, maintaining a Neutral rating and a $500 price target. Bazinet raises concerns about potentially overstated 2024 revenue estimates, the likelihood of content investments exceeding expectations in 2025, and the uncertainty surrounding potential acquisitions. Despite a 53% climb in Netflix over the past 12 months, Bazinet suggests that the current risk-reward balance appears relatively neutral.
In contrast, other analysts express optimism about Netflix's future. Seaport analyst David Joyce raised his price target to $541, citing the positive impact of continued growth in ad-tier signups. Netflix recently confirmed a surge in global monthly active users for its ad-based plan, reaching over 23 million. BofA Securities analyst Jessica Reif Ehrlich echoes the positive sentiment, noting that Netflix's success in the streaming wars positions it for further subscriber growth, especially with lower-priced options attracting budget-conscious viewers.
Mixed Analyst Sentiment on Netflix: Bullish and Cautious Views
- Seaport Global analyst David Joyce maintained a Buy rating and raised the price target from $482 to $541.
- Piper Sandler analyst Matt Farrell reiterated a Neutral rating and increased the price target from $400 to $475.
- UBS analyst John Hodulik kept a Buy rating and raised the price target from $500 to $560.
- Benchmark analyst Matthew Harrigan, with a Sell rating, raised the price target from $350 to $425.
- Citi analyst Jason Bazinet maintained a Neutral rating and a $500 price target.
Which Analyst has the best track record to show on NFLX?
Analyst Benjamin Swinburne (MORGAN STANLEY) currently has the highest performing score on NFLX with 40/46 (86.96%) price target fulfillment ratio. His price targets carry an average of $63.88 (13.14%) potential upside. Netflix stock price reaches these price targets on average within 171 days.
Discover Financial Q4 2023: Results and Outlook
Discover Financial Services reported its fourth-quarter 2023 financial results, revealing a net income of $388 million, a decrease from the prior year's $1 billion. The company experienced a 13% revenue growth, driven by a 15% increase in loans, partially offset by slight net interest margin compression. Expenses surged by 19% year-over-year, totaling $280 million, attributed to heightened investments in compliance and risk management, increased marketing expenses to support a national Cashback Debit campaign, and a reserve for customer remediation. Discover's net interest margin for the quarter ended at 10.98%, representing a 29 basis points decline from the previous year but showing a 3 basis points sequential increase. Despite these fluctuations, the full-year net interest margin held steady at 11.07%.
In terms of credit performance, Discover reported total net charge-offs at 4.11%, marking an increase of 198 basis points from the prior year and a 59 basis points rise from the previous quarter. The company bolstered its reserves by $618 million, leading to a 17 basis points increase in the reserve rate, reaching just over 7.2%. Discover's outlook for 2024 anticipates relatively flat end-of-period loan growth, with a net interest margin projected between 10.5% to 10.8%. Operating expenses are expected to rise by a mid-single-digit percent, factoring in compliance-related costs of approximately $500 million. The company aims for a net charge-off range of 4.9% to 5.3%.
Analyst Price Target Adjustments
- RBC Capital's Jon Arfstrom maintained an Outperform rating and lowered the price target from $130 to $117.
- Goldman Sachs analyst Ryan Nash kept a Buy rating and revised down the price target from $139 to $121.
- HSBC analyst Saul Martinez downgraded from Buy to Hold and the price target from $121 to $107.
- Barclays analyst Mark Devries reiterated Equal-Weight rating and decreased the price target from $124 to $112.
- JPMorgan analyst Richard Shane lowered the price target to $110.
- UBS analyst Eric Wasserstrom lowered the price target to $106.
Which Analyst has the best track record to show on DFS?
Analyst James Fotheringham (BMO) currently has the highest performing score on DFS with 13/16 (81.25%) price target fulfillment ratio. His price targets carry an average of $18.47 (22.65%) potential upside. Discover Financial Services stock price reaches these price targets on average within 183 days.
KeyCorp's Q4 2023 Financial Highlights
In KeyCorp's Q4 2023 earnings report, the bank posted net income of $30 million, equivalent to $0.03 per share. Expenses totaling $209 million or $0.22 per share were incurred during the quarter. Despite the challenging financial landscape, KeyCorp successfully reduced loans by $7 billion and achieved a deposit growth of $3 billion in 2023. The common equity Tier 1 ratio concluded the year at 10%, a 90 basis points increase from the previous year and well above the targeted range of 9% to 9.5%. The bank also implemented significant cost-cutting measures, freeing up over $400 million on an annualized basis.
Looking forward to 2024, KeyCorp projects an estimated $500 million net interest income benefit throughout the year as short-term swaps and treasuries reprice. The bank anticipates a decrease of 5-7% in average loans but aims for moderate positive operating leverage, expecting stable non-interest expenses at approximately $4.4 billion. Net charge-offs are expected to modestly increase to the 30-40 basis point range, maintaining a strong credit quality position.
Analysts Mixed Ratings and Price Target Adjustments
- Keefe, Bruyette & Woods analyst David Konrad maintained an Outperform rating and lowered the price target from $17 to $16.
- RBC Capital analyst Gerard Cassidy reiterated an Outperform rating and raised the price target from $13 to $15.
- Wedbush analyst David Chiaverini kept a Neutral rating and lowered the price target from $16 to $14.
- Barclays analyst Jason Goldberg remained with Equal-Weight rating and lowered the price target from $17 to $16.
Which Analyst has the best track record to show on KEY?
Analyst Ken Usdin (JEFFERIES) currently has the highest performing score on KEY with 8/11 (72.73%) price target fulfillment ratio. His price targets carry an average of $2.41 (16.52%) potential upside. KeyCorp stock price reaches these price targets on average within 258 days.
Daily stock Analysts Top Price Moves Snapshot
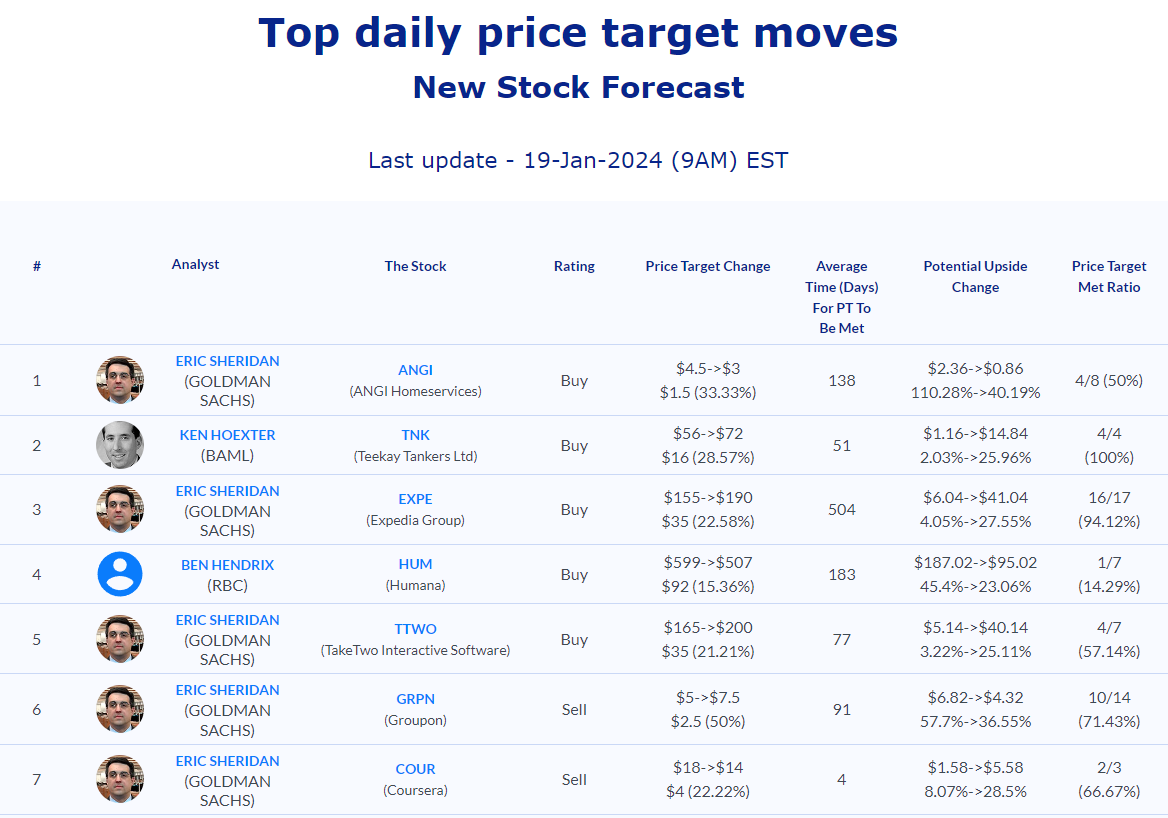
January 22, 2024:
By: Matthew Otto
J.B. Hunt Increase in Intermodal Volumes Amidst Industry Challenges
J.B. Hunt Transport Services shared its financial performance for the fourth quarter of 2023. The company reported a 6% increase in Intermodal volumes during the quarter, showcasing a positive trend for nine consecutive months. However, the financials revealed a substantial impact as the company incurred an additional $53 million in insurance costs due to elevated claims expenses and surpassing coverage limits, reflecting industry-wide challenges with rising insurance rates and litigation settlements.
In the Integrated Capacity Solutions segment, a 25% decline in gross revenue was attributed to a 12% reduction in volume and a 15% decrease in revenue per load. Similarly, the Truckload segment reported a 19% decrease in gross revenue, with a 13% decline in revenue per load and a 7% reduction in volumes. The company outlined its capital expenditure plans for 2024, projecting a range between $800 million and $1 billion, primarily allocated to technology, capacity, and real estate investments.
Analysts Offer Varied Perspectives with Price Target Adjustments
- Stifel analyst J. Bruce Chan reiterated a Hold rating and a $188 price target.
- Baird analyst Benjamin Hartford maintained an Outperform rating and a $215 price target.
- Raymond James analyst Patrick Tyler Brown kept an Outperform rating and raised the price target from $209 to $210.
- Susquehanna analyst Bascome Majors maintained a Neutral rating and lowered the price target from $195 to $194.
- Benchmark analyst Chris Kunh raised the price target to $215.
- UBS analyst Thomas Wadewitz upgraded to a Buy rating.
Which Analyst has the best track record to show on JBHT?
Analyst Ken Hoexter (BAML) currently has the highest performing score on JBHT with 13/14 (92.86%) price target fulfillment ratio. His price targets carry an average of $22.13 (11.41%) potential upside. J.B. Hunt Transport Services stock price reaches these price targets on average within 171 days.
H.B. Fuller's Q4 2023 Success and Optimistic 2024 Outlook
H.B. Fuller reported financial performance for the fourth quarter of 2023. The company achieved a 22% increase in adjusted EBITDA year-on-year, reaching $173 million. The financial results were underpinned by strategic initiatives, including pricing and raw material cost management, synergistic acquisitions, and restructuring actions. The company's adjusted EBITDA margin also soared to 19.1%, marking a 440 basis points increase compared to the same period last year.
The company's fiscal year 2024 outlook anticipates a net revenue growth between 2% and 6%, with organic revenue expected to be flat to up 3%. The projected adjusted EBITDA for 2024 is set to be in the range of $610 million to $640 million, reflecting a 5% to 10% increase year-on-year.
Mixed Analyst Ratings with Varied Price Targets
- Baird analyst Ghansham Panjabi reiterated a Neutral rating and a $80 price target.
- Stifel analyst Vincent Anderson maintained a Buy rating and raised the price target from $110 to $115.
- JPMorgan analyst Jeffrey J. Zekauskas raised the price target to $70.
- Deutsche Bank analyst David Begleiter kept a Buy rating and increased the price target from $84 to $85.
Which Analyst has the best track record to show on FUL?
Analyst Ghansham Panjabi (BAIRD) currently has the highest performing score on FUL with 9/11 (81.82%) price target fulfillment ratio. His price targets carry an average of $3.25 (4.23%) potential upside. H.B. Fuller stock price reaches these price targets on average within 232 days.
M&T Bank Performance in 2023, Fueled by Strategic Growth and Capital Management
M&T Bank reported financial performance for the fourth quarter and full year of 2023. The bank's pre-tax pre-provision revenue for the full year reached $4.2 billion, demonstrating a 22% increase from the previous year. M&T Bank had an operating leverage of 3.9%. The net charge-offs remained in line with long-term historical averages at 33 basis points, and GAAP net income for 2023 amounted to $2.7 billion, resulting in a 37% surge in diluted earnings per share to $15.79. The financial foundation is underscored by the CET1 ratio standing near 11%, emphasizing M&T Bank's commitment to maintaining capital levels. Commercial and Industrial loans saw an 11% increase, surpassing $5 billion in growth.
Analysts Adjusted Price Targets Amid Market Evaluation
- DA Davidson analyst Peter Winter maintained at Neutral rating and lowered the price target from $163 to $159.
- Piper Sandler analyst Frank Schiraldi reiterated an Overweight rating and adjusted the price target down from $156 to $152.
- RBC Capital analyst Gerard Cassidy kept an Outperform rating and the price target at $160.
- Wedbush analyst David J. Chiaverini lowered the price target to $160.
Which Analyst has the best track record to show on MTB?
Analyst Peter Winter (WEDBUSH) currently has the highest performing score on MTB with 5/9 (55.56%) price target fulfillment ratio. His price targets carry an average of $19.61 (14.07%) potential upside. M&T Bank stock price reaches these price targets on average within 268 days.
Daily stock Analysts Top Price Moves Snapshot
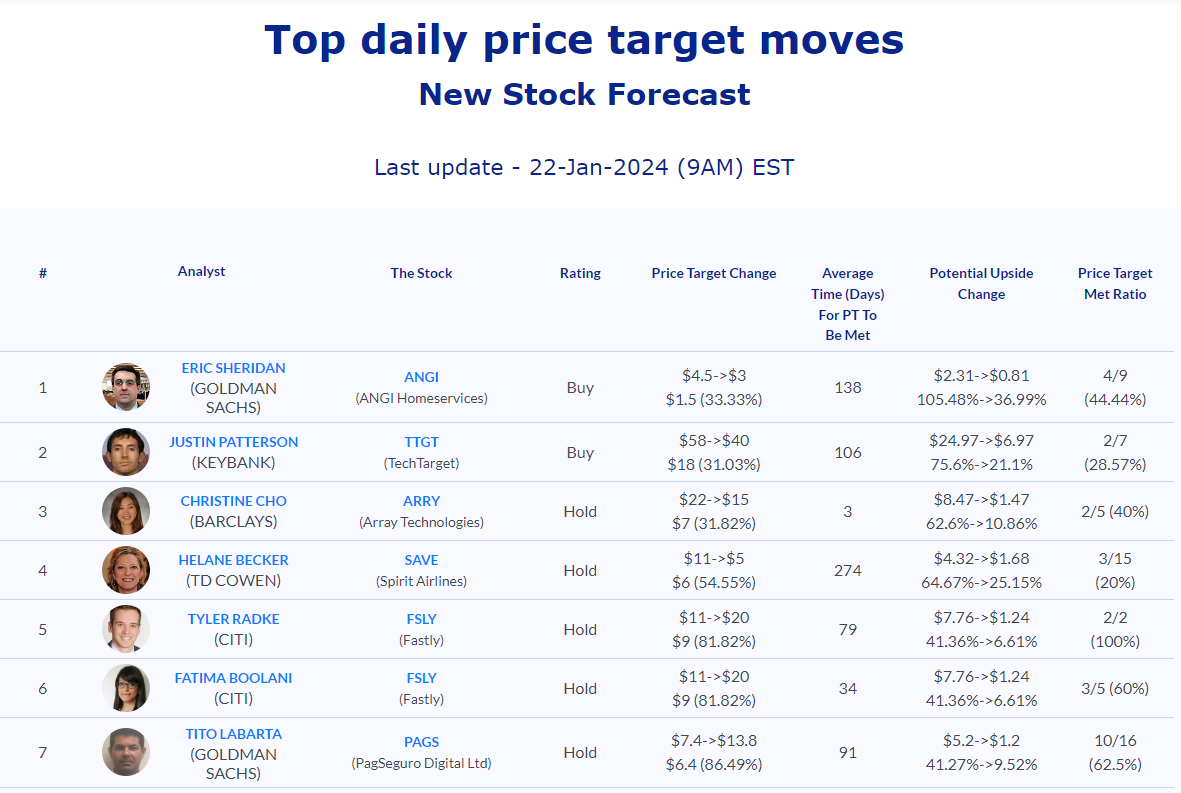
January 23, 2024:
By: Matthew Otto
AMD Faces Uncertainty Amid Surging Demand for AI GPUs
The demand for graphics processing units, particularly those tailored for artificial intelligence applications, has driven gains for AMD, with a surge of nearly 130% in 2023. Investors are optimistic about the potential gains AMD's AI-oriented GPUs could achieve, potentially challenging industry leader Nvidia. However, Northland Capital Markets analyst Gus Richard has tempered these expectations, expressing uncertainty about AMD's future trajectory. Citing what he perceives as irrational exuberance among investors, Richard emphasizes distortions in overall demand signals, with Nvidia acting as an effective sole source for AI chips, leading to supply-demand imbalances and instances of customers double ordering. Additionally, potential challenges, such as recent U.S. moves to restrict certain chip exports to China, are noted as factors that could weigh on future growth.
Despite the optimistic outlook for AI chip revenue, Richard downgrades AMD's stock to a "heck if we know" rating, equivalent to a hold or market perform. He suggests that, even if AMD were to achieve substantial AI chip sales, doubling to $16 billion by 2027, maintaining a 13% market share, the company would need continued robust investments in research and development to stay competitive with Nvidia. Richard believes that the current stock price already factors in expectations of reaching $45 billion in total revenue by 2027.
Analysts Mixed Ratings and Price Targets
- Cantor Fitzgerald analyst C J Muse initiated an Overweight rating and a Price Target of $190.
- Northland Capital Markets analyst Gus Richard downgraded from Outperform to Market Perform.
- Wedbush analyst Matt Bryson raised the Price Target to $200.
Which Analyst has the best track record to show on AMD?
Analyst Timothy Arcuri (UBS) currently has the highest performing score on AMD with 5/5 (100%) price target fulfillment ratio. His price targets carry an average of $27.17 (25.20%) potential upside. Advanced Micro Devices stock price reaches these price targets on average within 95 days.
ADM Faces Investor Concerns and Market Turbulence
Archer-Daniels-Midland faced a setback as it announced a revision to its 2023 profit target. The company's Chief Financial Officer, Vikram Luthar, is presently on administrative leave pending an investigation into accounting practices at ADM's nutrition unit, triggered by a request for information from the US Securities and Exchange Commission. This development resulted in a market reaction, with ADM's plummeting by nearly 24%, equating to a staggering $8.8 billion reduction in market value.
ADM's nutrition business, a key focus of the company's diversification strategy, encountered challenges as its operating earnings for 2023 shrank by approximately 20%, following a period of more modest growth at under 7% in 2022. Despite previous successful acquisitions, including the $3.1 billion purchase of Wild Flavors GmbH in 2014, the nutrition segment struggled to meet the company's optimistic projections.
Analysts Downgrades and Adjust Price Targets
- Goldman Sachs analyst Adam Samuelson maintained a Neutral rating and lowered the price target from $90 to $67.
- Stifel analyst Vincent Anderson downgraded from Buy to Hold and the price target from $116 to $56.
- Barclays analyst Benjamin Theurer downgraded from Overweight to Underweight and announced a $60 price target.
- Roth MKM analyst Brian Wright downgraded from Buy to Neutral and the price target from $98 to $66.
Which Analyst has the best track record to show on ADM?
Analyst Vincent Andrews (MORGAN STANLEY) currently has the highest performing score on ADM with 7/8 (87.5%) price target fulfillment ratio. His price targets carry an average of $5.02 (7.07%) potential upside. Archer-Daniels-Midland stock price reaches these price targets on average within 150 days.
D.R. Horton's Mixed Q1 Results Prompt Market Concerns
D.R. Horton unveils its 2024 fiscal first-quarter results. While the company's quarterly revenue of $7.73 billion surpassed expectations of $7.56 billion, its earnings per share fell short at $2.82, compared to the Wall Street forecast of $2.87. Analysts from Wells Fargo, Sam Reid and Zachary Fadem, anticipate 88,300 deliveries in 2024, slightly exceeding the consensus call of 88,100. However, some analysts, including Jay McCanless and Brian Violino from Wedbush, point to a notable order miss and a gross margin shortfall compared to consensus forecasts, highlighting fluctuating mortgage rates during the builder's first quarter as potential contributing factors.
The company has adjusted its 2024 guidance, projecting revenue in the range of $36 billion to $37.3 billion. The broader impact on the industry is reflected in a 2.25% decline in the iShares U.S. Home Construction exchange-traded fund in premarket trading.
Mixed Analyst Signals on D.R. Horton
- Wedbush analyst Jay McCanless reiterated Neutral rating and a $115 price target.
- Seaport Global analyst Kenneth Zener downgraded from Buy to Neutral.
Which Analyst has the best track record to show on DHI?
Analyst Anthony Pettinari (CITI) currently has the highest performing score on DHI with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $22.4 (19.05%) potential upside. D.R. Horton stock price reaches these price targets on average within 140 days.
Daily stock Analysts Top Price Moves Snapshot
January 24, 2024:
By: Matthew Otto
Verizon Q4 2023 Performance with Growth in Wireless Subscribers
Verizon reported the fourth quarter of 2023 with a revenue for the year reaching $76.7 billion, marking a 3.2% year-over-year increase. This growth was driven by 449,000 postpaid phone net adds in Mobility, with 318,000 of those in the Consumer segment. The launch of myPlan offering, a flexible wireless plan, contributed to Verizon garnering 13.1 million subscribers since its introduction in May. Additionally, Verizon Business demonstrated strength with 131,000 postpaid phone net adds, marking the tenth consecutive quarter of net adds above 125,000. In the broadband segment, Verizon experienced growth with over 1.7 million net broadband additions for the year, including more than 1.5 million from fixed wireless access. The company's financial foundation was reflected in a full-year adjusted EBITDA of $47.8 billion, contributing to a free cash flow of $18.7 billion.
Looking forward to 2024, the company anticipates a 2% to 3.5% growth in wireless service revenue. The adjusted EBITDA is expected to grow by 1% to 3%. The adjusted earnings per share for 2024 is projected to be in the range of $4.50 to $4.70. With capital spending expected to range between $17 billion and $17.5 billion.
Analysts Bullish as Price Targets Soar Amid Positive Ratings
- Raymond James analyst Frank Louthan maintained an Outperform rating and raised the price target from $42 to $46.
- Daiwa Capital analyst Jonathan Kees upgraded from Neutral to Outperform and set a price target of $47.
- Keybanc analyst Brandon Nispel maintained an Overweight rating and raised the price target from $45 to $46.
- JPMorgan analyst Philip Cusick raised the price target to $46.
- BofA analyst David Barden reiterated a Neutral rating with a price target of $41.
- Wells Fargo analyst Eric Luebchow increased the price target to $44.
- TD Cowen analyst Colby Synesael raised the price target to $48.
Which Analyst has the best track record to show on VZ?
Analyst Eric Luebchow (WELLS FARGO) currently has the highest performing score on VZ with 3/6 (50%) price target fulfillment ratio. His price targets carry an average of $3.01 (8.14%) potential upside. Verizon stock price reaches these price targets on average within 195 days.
Webster Q4 2023 Earnings and Strategic Expansion with Ametros Acquisition
Webster Financial reported financial results for the fourth quarter of 2023. The company's adjusted earnings per share saw an increase from $5.62 to $5.99 on a full-year basis. Additionally, Webster maintained capital levels with a common equity Tier 1 ratio of 11.12% and a tangible common equity ratio of 7.73%. The bank's return on assets stood at 1.43%, while the return on tangible common equity reached 20.5%. Loan growth, particularly in strategic commercial categories, increased by approximately 1%. Webster's efficiency ratio closed the year at 42%, underscoring its commitment to operational efficiency.
Furthermore, the acquisition of Ametros, announced in the prior year, is anticipated to add a new dimension to Webster's funding diversity. The bank expects the Ametros transaction to be modestly accretive to earnings in 2024 and 3% accretive in 2025. The outlook for 2024 includes projections for loans and deposits to grow in the range of 5% to 7%.
Analyst Perspectives Diverge on Webster Financial
- JP Morgan analyst Steven Alexopoulos upgraded from Neutral to Overweight and the price target from $60 to $65.
- Raymond James analyst Daniel Tamayo maintained an Outperform rating and raised the price target from $57 to $60.
- Citi analyst Benjamin Gerlinger lowered the price target to $60.
Which Analyst has the best track record to show on WBS?
Analyst Manan Gosalia (MORGAN STANLEY) currently has the highest performing score on WBS with 6/7 (85.71%) price target fulfillment ratio. His price targets carry an average of $3.52 (7.41%) potential upside. Webster Financial stock price reaches these price targets on average within 73 days.
Netflix Surpasses Expectations with 13.1 Million Subscriber Growth in Q4 2023
Netflix's fourth-quarter results exceeded expectations, reporting an addition of 13.1 million subscribers, bringing the total paid subscribers to a record 260.8 million. The company's net income for the quarter was $937.8 million, or $2.11 per share, compared to $55.3 million, or 12 cents per share, in the previous year. With a focus on profitability, Netflix raised its 2024 full-year operating margin forecast to 24% and projected first-quarter 2024 earnings per share at $4.49, surpassing Wall Street estimates of $4.10. The company is poised to invest in an expansive content slate, distinguishing itself from competitors who are cutting back on content spending.
In addition to its subscriber growth, Netflix is actively developing its advertising-based plan, with over 23 million global monthly active users. Netflix's strategic approach involves partnerships with content creators from traditional linear spaces rather than pursuing acquisitions of conventional entertainment companies.
Analysts Diverge on Netflix Ratings and Targets
- Macquarie's Tim Nollen upgraded from Neutral to Outperform and the price target from $410 to $595.
- Wedbush's Michael Pachter maintained an Outperform rating and raised the price target from $525 to $615.
- Deutsche Bank's Bryan Kraft downgraded from Buy to Hold and revised the price target from $460 to $525.
- Keybanc's Justin Patterson kept an Overweight rating and increased the price target from $545 to $580.
- MoffettNathanson's Michael Nathanson reiterated a Neutral rating and increased the price target from $390 to $440.
- Evercore ISI's Mark Mahaney maintained an Outperform rating and a $500 price target.
- Benchmark's Matthew Harrigan kept a Sell rating and raised the price target from $350 to $425.
Which Analyst has the best track record to show on NFLX?
Analyst Benjamin Swinburne (MORGAN STANLEY) currently has the highest performing score on NFLX with 40/46 (86.96%) price target fulfillment ratio. His price targets carry an average of $63.88 (13.14%) potential upside. Netflix stock price reaches these price targets on average within 171 days.
Daily stock Analysts Top Price Moves Snapshot

January 25, 2024:
By: Matthew Otto
Texas Instruments Fourth Quarter 2023 Earnings: Revenue Declines Amid Sector Challenges
Texas Instruments reported its fourth-quarter earnings for 2023, revealing a total revenue of $4.1 billion, a decrease of 10% and a year-over-year decline of 13%. The company's analog revenue dropped by 12%, while embedded processing experienced a 10% decline. Notably, the other segment saw a downturn of 25% from the same quarter in the previous year. Industrial and automotive markets accounting for 74% of its revenue for the year, up from 42% in 2013. Industrial revenue stood at 40%, while automotive contributed 34%.
Texas Instrument's gross profit margin decreased by 650 basis points, attributed to lower revenue, increased manufacturing costs, and reduced factory loading. Operating expenses rose by 4% compared to the previous year, while operating profit saw a 30% decline year-over-year. Net income for the fourth quarter reached $1.4 billion, translating to $1.49 per share, with earnings per share including a $0.03 benefit from unanticipated items.
The company had $1.9 billion cash flow from operations, $1.1 billion in capital expenditures, and $1.2 billion returned to shareholders through dividends. Looking ahead, Texas Instrument projects revenue in the range of $3.45 billion to $3.75 billion for the first quarter of 2024, with earnings per share anticipated to be between $0.96 and $1.16.
Analysts Maintain Varied Ratings and Adjust Price Targets Amid Market Trends
- Barclays analyst Tom O'Malley maintained an Equal-Weight rating and lowered the price target from $160 to $150.
- Morgan Stanley analyst Joseph Moore reiterated an Underweight rating and raised the price target from $138 to $146.
- Susquehanna analyst Christopher Rolland maintained a Positive rating and lowered the price target from $205 to $200.
- Mizuho analyst Vijay Rakesh kept a Neutral rating and lowered the price target from $170 to $164.
- Cantor Fitzgerald analyst C J Muse maintained a Neutral rating and decreased the price target from $180 to $170.
- Truist Securities analyst William Stein kept a Hold rating and decreased the price target from $169 to $168.
- Keybanc analyst John Vinh reiterated an Overweight rating and raised the price target from $180 to $200.
Which Analyst has the best track record to show on TXN?
Analyst Blayne Curtis (BARCLAYS) currently has the highest performing score on TXN with 11/11 (100%) price target fulfillment ratio. His price targets carry an average of $24.5 (17.44%) potential upside. Texas Instrument stock price reaches these price targets on average within 64 days.
Lam Research's Q4 2023 Performance and Growth Outlook
Lam Research showcased its December 2023 quarterly report, reporting EPS of $7.52, better than the analyst estimate of $7.07. Revenue shows an 8% increase from the previous quarter, reaching $3.76 billion, compared to the consensus estimate of $3.7 billion. Despite a 29% decrease in revenue from the same period a year ago, Lam's strategic initiatives and operational efficiency were evident in the gross margin performance, reaching 47.6%, slightly above the midpoint of guidance.
Lam had allocated approximately $640 million to open market share repurchases and $264 million in dividends during the December quarter. Lam ended the year with a cash and short-term investments balance of $5.6 billion. Looking forward, the company provided guidance for the March 2024 quarter, anticipating revenue of $3.7 billion with a gross margin of 48%. Furthermore, Lam has undertaken strategic initiatives, including a planned spending increase in R&D for 2024, and anticipates spending $300 million on improvement activities and headcount reductions.
Analysts Bullish: Price Targets Raised Across the Board
- Goldman Sachs analyst Toshiya Hari maintained a Buy rating and raised the price target from $700 to $912.
- Raymond James analyst Srini Pajjuri reiterated an Outperform rating and increased the price target from $850 to $950.
- Barclays analyst Raimo Lenschow maintained an Equal-Weight rating and raised the price target from $750 to $825.
- Needham analyst Charles Shi kept a Buy rating and upgraded the price target from $800 to $900.
- Stifel analyst Brian Chin kept a Buy rating and increased the price target from $850 to $950.
- Citi analyst Atif Malik maintained a Buy rating and raised the price target from $800 to $975.
Which Analyst has the best track record to show on LRCX?
Analyst Tammy Qiu (BERENBERG) currently has the highest performing score on LRCX with 4/4 (100%) price target fulfillment ratio. Her price targets carry an average of $32.07 (4.60%) potential upside. Lam Research stock price reaches these price targets on average within 232 days.
ServiceNow's Q4 2023: AI Integration Drives Growth
In the fourth quarter of 2023, ServiceNow reported a subscription revenue of $2.365 billion, reflecting a 27% increase compared to the same period in the previous year. Total revenue for the quarter reached $2.437 billion, demonstrating a year-over-year growth of 26%. The company's adjusted profit per share on a fully diluted basis stood at $3.11, outperforming the Street consensus of $2.78 per share according to FactSet. Notably, ServiceNow achieved a non-GAAP operating margin of 29%, surpassing the company's own forecast of 27.5%.
Looking ahead to the first quarter of 2024, ServiceNow projects subscription revenue ranging between $2.510 billion and $2.515 billion, representing a year-over-year growth of 24% to 24.5%. For the full year 2024, the company anticipates subscription revenues between $10.555 billion and $10.575 billion, signaling an increase of 21.5% to 22%. ServiceNow's current remaining performance obligations also experienced growth, reaching $8.6 billion, a 24% increase over the previous year and three percentage points higher than forecast.
Analysts Bullish on Growth Prospects
- BMO Capital's Keith Bachman maintained an Outperform rating and raised the price target from $630 to $850.
- Goldman Sachs' Kash Rangan kept a Buy rating and increased the price target from $800 to $910.
- Piper Sandler's Rob Owens reiterated an Overweight rating and raised the price target from $750 to $830.
- Barclays' Raimo Lenschow maintained an Overweight rating and upgraded the price target from $870 to $890.
- Needham's Mike Cikos reiterated a Buy rating and a $900 price target.
- Truist Securities' Joel Fishbein Jr. reiterated a Hold rating and raised the price target from $700 to $750.
- Jefferies' Samad Samana kept a Buy rating and increased the price target from $775 to $885.
Which Analyst has the best track record to show on NOW?
Analyst Brad Reback (STIFEL) currently has the highest performing score on NOW with 9/9 (100%) price target fulfillment ratio. His price targets carry an average of $13.54 (1.86%) potential upside. ServiceNow stock price reaches these price targets on average within 141 days.
Daily stock Analysts Top Price Moves Snapshot
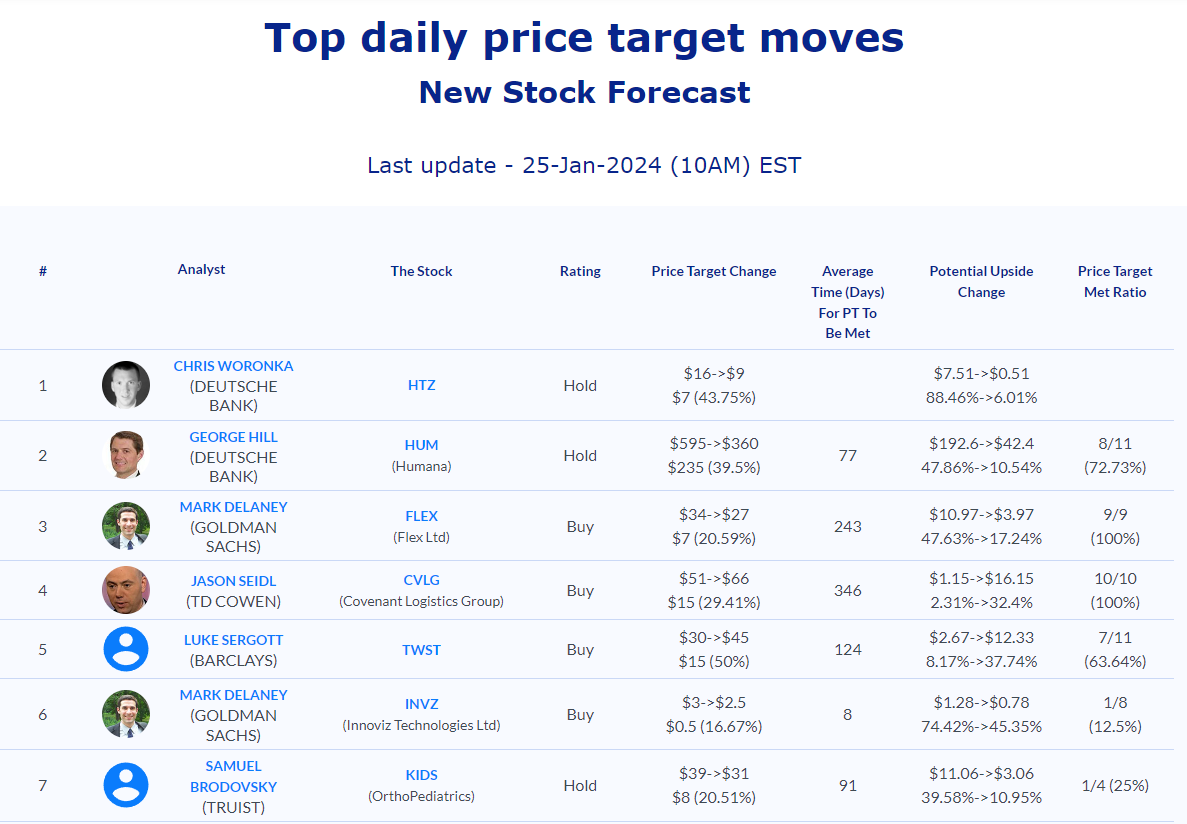
January 26, 2024:
By: Matthew Otto
Intel Reports Fourth Quarter 2023 Results and Upbeat Guidance for Fiscal Year 2024
Intel reported financial results for the fourth quarter of 2023 with a revenue of $15.4 billion, exceeding consensus estimate of $15.16 billion. This marks a 9% sequential increase and a 10% year-over-year rise. Gross margin stood at 48.8%, surpassing guidance by 230 basis points. Additionally, earnings per share for the quarter reached $0.54, surpassing guidance by $0.10. Intel's Client Computing Group notably performed well, achieving revenue of $8.8 billion, up 12% sequentially and 33% year-over-year, buoyed by sustained strength in gaming and commercial segments.
Intel anticipates first-quarter guidance revenue in the range of $12.2 billion to $13.2 billion, with an expected gross margin of approximately 44.5%. The company forecasts a double-digit sequential decline in data center revenue for Q1, followed by gradual improvement throughout the year. Despite temporary headwinds such as inventory corrections in Mobileye and PSG, Intel projects sequential and year-on-year growth in both revenue and EPS for each quarter of fiscal year 2024.
Mixed Analyst Sentiment as Price Targets and Ratings Adjusted
- Raymond James analyst Srini Pajjuri maintained an Outperform rating and lowered the price target from $54 to $52.
- Needham analyst Quinn Bolton downgraded from Buy to Hold.
- Summit Insights Group analyst Kinngai Chan downgraded from Buy to Hold.
- Mizuho Securities analyst Vijay Rakesh reiterated a Buy rating and lowered the price target from 58$ to $55.
- Wedbush analyst Matthew Bryson kept a Neutral rating and decreased the price target from $45 to $40.
- CFRA analyst Angelo Zino maintained a Hold rating and raised the price target from $39 to $50.
Which Analyst has the best track record to show on INTC?
Analyst Srini Pajjuri (JEFFERIES) currently has the highest performing score on INTC with 9/12 (75%) price target fulfillment ratio. His price targets carry an average of $5.85 (12.15%) potential upside. Intel stock price reaches these price targets on average within 221 days.
Levi Strauss Reports Fiscal Year 2023 Results Amidst Retail Challenges
Levi Strauss reported its financial results for the fourth quarter and fiscal year ending November 26, 2023. In the fourth quarter, the company recorded net revenues of $1.6 billion, marking a 3% increase and a 2% rise on a constant-currency basis compared to the same period in 2022. Direct-to-Consumer net revenues surged by 11% with e-commerce sales demonstrating growth of 19% globally. However, wholesale net revenues experienced a slight dip of 2%, reflecting a nuanced performance across different regions. Operating income surged across all segments, with a 50% increase in the Americas segment, while gross margin expanded to 57.8%.
For the full fiscal year, Levi Strauss reported flat net revenues of $6.2 billion. Gross margin at 56.9%, down 70 basis points from the previous fiscal year. Adjusted EBIT margin stood at 9.0%, compared to 11.6% in FY 2022. Net income for the year totaled $250 million, a decline from $569 million in the previous fiscal year, while adjusted net income amounted to $441 million, down from $604 million in FY 2022. Levi Strauss also provided guidance for fiscal 2024, expecting reported net revenues growth of 1% to 3% year-over-year, with adjusted diluted EPS projected to range from $1.15 to $1.25.
Analysts Offer Mixed Views Amidst Adjusted Price Targets
- Wells Fargo analyst Ike Boruchow maintained an Equal-Weight rating and lowered the price target from $18 to $17.
- Telsey Advisory Group analyst Dana Telsey reiterated an Outperform rating and raised the price target from $16 to $18.
- JPMorgan analyst Matthew Boss lowered the price target to $15.
Which Analyst has the best track record to show on LEVI?
Analyst Kimberly Greenberger (MORGAN STANLEY) currently has the highest performing score on LEVI with 8/8 (100%) price target fulfillment ratio. Her price targets carry an average of $-0.16 (-1.13%) potential downside. Levi Strauss stock price reaches these price targets on average within 204 days.
T-Mobile US Reports 2023 Performance and Optimistic Outlook for 2024
T-Mobile US reported financial performance for the Fourth Quarter and Full Year 2023. The telecommunications company reached a postpaid phone net additions of 3.1 million, marking a 2% increase for the year and a 6% surge in Q4. T-Mobile added over 2.1 million customers in 2023, concluding the year with 4.8 million broadband customers. In terms of financials, T-Mobile's consolidated service revenue posted a 6% increase in postpaid service revenue. This translated into core adjusted EBITDA growth of over 10% and a nearly 80% increase in adjusted free cash flow, reaching a total of $17 billion returned to stockholders through the end of 2023.
Looking ahead to 2024, T-Mobile provided guidance, projecting total postpaid net customer additions between 5 million and 5.5 million. The company expects core adjusted EBITDA to range between $31.3 billion and $31.9 billion, reflecting a nearly 9% year-over-year increase at the midpoint. T-Mobile anticipates cash CapEx between $8.6 billion and $9.4 billion. Free cash flow, including merger-related costs, is projected to be in the range of $16.3 billion to $16.9 billion, indicating a 22% growth at the midpoint compared to the previous year. Additionally, T-Mobile aims for a 2% increase in postpaid ARPA in 2024.
Analyst Adjustments in Price Targets and Recommendations
- Raymond James analyst Ric Prentiss reaffirmed a Strong Buy rating and increased the price target from $180 to $185.
- Keybanc analyst Brandon Nispel maintained an Overweight rating and revised the price target downward from $183 to $175.
- TD Cowen analyst Greg Williams lowered the price target to $204.
- Wolfe Research analyst Peter Supino kept an Outperform rating and adjusted the price target from $230 to $200.
Which Analyst has the best track record to show on TMUS?
Analyst Simon Flannery (MORGAN STANLEY) currently has the highest performing score on TMUS with 19/27 (70.37%) price target fulfillment ratio. His price targets carry an average of $40.61 (29.13%) potential upside. T-Mobile US stock price reaches these price targets on average within 307 days.
Daily stock Analysts Top Price Moves Snapshot

January 29, 2024:
By: Matthew Otto
Capital One's Q4 2023: Resilient Domestic Card Growth
Capital One reported its financial results for the fourth quarter of 2023, showcasing a mixed performance across its business segments. The company earned $706 million, equivalent to $1.67 per diluted common share, with full-year earnings reaching $4.9 billion or $11.95 per share. Adjusted for special assessments, earnings per share stood at $2.24 for the quarter and $12.52 for the year. The Domestic Card business witnessed a 4% increase in purchase volume and a $16 billion rise in ending loan balances, reflecting a 12% year-over-year growth. Consumer Banking saw a 9% year-over-year increase in federally insured consumer deposits, yet revenue dipped by approximately 17%, primarily driven by lower auto loan balances and heightened deposit costs.
Capital One observed stabilization in delinquency rates across segments. The charge-off rate for the Domestic Card business, for instance, rose by 213 basis points year-over-year to 5.35%, while the 30-plus delinquency rate increased by 118 basis points to 4.61%. However, the company anticipates a stabilization in charge-off rates, projecting a movement more in line with seasonal patterns over the near term. Operating efficiency also improved by 99 basis points for the full year 2023.
Analysts Mixed Signals as Price Targets and Ratings Adjusts
- Wolfe Research analyst Bill Carcache upgraded from Underperform to Peer Perform.
- Piper Sandler analyst Kevin Barker maintained a Neutral rating and raised the price target from $123 to $126.
- JP Morgan analyst Richard Shane reiterated a Neutral rating and increased the price target from $131 to $134.
- RBC Capital analyst Jon Arfstrom kept a Sector Perform rating and adjusted the price target from $140 to $142.
- BofA Securities analyst Mihir Bhatia maintained a Buy rating and lowered the price target from $149 to $146.
- BMO Capital analyst James Fotheringham raised the price target to $125.
Which Analyst has the best track record to show on COF?
Analyst Mihir Bhatia (BAML) currently has the highest performing score on COF with 3/3 (100%) price target fulfillment ratio. His price targets carry an average of $15.23 (13.39%) potential upside. Capital One stock price reaches these price targets on average within 99 days.
Norfolk Southern Q4 2023: Safety Progress Amid Revenue Challenges
Norfolk Southern Corporation reported its fourth-quarter 2023 earnings with total revenues reaching $3.1 billion, representing a nearly 5% decline compared to the same period in the previous year. The company experienced a 42% reduction in its mainline accident rate for the year. Despite facing challenges such as the Eastern Ohio derailment and network disruptions, Norfolk Southern managed a 3% increase in overall volume during the fourth quarter, with intermodal volume growing by 5%. Additionally, the company revealed a strategic focus on cost efficiency by implementing a program to reduce management headcount by approximately 7%, aligning with its broader transformation initiatives.
In the context of the Eastern Ohio incident, Norfolk Southern incurred $137 million in soil remediation costs during the fourth quarter, with a total cash outflow of $652 million for 2023, partially offset by $76 million in insurance recoveries. Operational expenses for the quarter were up $59 million, excluding fuel, driven by factors such as employment growth, increased technology spend, and repairs in preparation for growth opportunities in 2024. The company's adjusted operating ratio for the quarter was 68.8%, reflecting a sequential improvement of 30 basis points from the third quarter.
Analysts Adjust Ratings and Price Targets Amid Market Shifts
- BMO Capital's Fadi Chamoun maintained a Market Perform rating and lowered the price target from $250 to $245.
- TD Cowen's Jason Seidl downgraded from Outperform to Market Perform and raised the price target from $233 to $236.
- Stifel's Benjamin Nolan downgraded from Buy to Hold and the price target from $250 to $233.
- Morgan Stanley's Ravi Shanker downgraded from Equal-Weight to Underweight and the price target from $185 to $175.
- RBC Capital's Walter Spracklin lowered the price target to $207.
Which Analyst has the best track record to show on NSC?
Analyst Walter Spracklin (RBC) currently has the highest performing score on NSC with 15/15 (100%) price target fulfillment ratio. His price targets carry an average of $17.02 (9.25%) potential upside. Norfolk Southern Corporation stock price reaches these price targets on average within 58 days.
American Airlines Gains Wall Street Favor Following Q4 Earnings
American Airlines is gaining favor on Wall Street after its fourth-quarter earnings report. Citi analysts, Stephen Trent, recently upgraded the stock to Buy from Neutral. Trent pointing out that mainline airlines have positioned themselves in the post pandemic environment. This is due to diversified revenue streams and premium offerings. The airline's ongoing focus on deleveraging, low capital expenditures, and industry capacity constraints have contributed to the positive outlook. Additionally, other analysts, including TD Cowen and Seaport Research, have also upgraded the stock, emphasizing American Airlines' regained momentum, achievable 2024 guidance, and compelling earnings trajectory.
Wall Street sentiment towards American Airlines is notably shifting, with 43% of analysts covering the shares now rating them as Buy, the highest level since November 2019. The sentiment follows the airline's announcement of 2024 results, forecasting full-year earnings between $2.25 and $3.25 based on current demand trends.
Analysts Diverge Amidst Varied Outlooks
- Citigroup analyst Stephen Trent upgraded from Neutral to Buy and the price target from $14 to $20.
- Barclays analyst Brandon Oglenski maintained an Underweight rating and raised the price target from $13 to $14.
- JP Morgan analyst Jamie Baker reiterated an Overweight rating and raised the price target from $19 to $22.
- Seaport Global analyst Daniel McKenzie upgraded from Neutral to Buy.
- TD Cowen analyst Helane Becker upgraded from Market Perform to Outperform and the price target from $14 to $21.
Which Analyst has the best track record to show on AAL?
Analyst Duane Pfennigwerth (EVERCORE) currently has the highest performing score on AAL with 5/7 (71.43%) price target fulfillment ratio. His price targets carry an average of $2.27 (15.41%) potential upside. American Airlines stock price reaches these price targets on average within 6 days.
Daily stock Analysts Top Price Moves Snapshot

January 30, 2024:
By: Matthew Otto
AMD Soars on Musk Endorsement and Analyst Upgrades
Advanced Micro Devices is experiencing a surge in investor confidence after Elon Musk's declaration that Tesla plans to utilize AMD chips for its artificial intelligence initiatives. Susquehanna analyst Christopher Rolland raised his target price to $210, maintaining a Positive rating. He suggests that AMD's software capability has significantly improved its competitiveness against Nvidia's CUDA, a factor that hindered AMD's performance in the past. Rolland anticipates that the MI300 chip, AMD's primary AI hardware offering, could potentially generate over $3 billion, with an outlook of around $6 billion in revenue.
Stifel analysts, led by Ruben Roy, also raised their target price on AMD to $200 while reiterating a Buy rating. Roy emphasizes the potential of the MI300 chip and anticipates meaningful upside in 2024, driven by improving supply and strong ongoing demand. Despite the trailing price-to-earnings multiple of at least 75 times, which implies a hefty valuation, analysts see this as justified given AMD's potential to solidify its position as a chief alternative AI chip supplier to Nvidia. Additionally, Bank of America analyst Vivek Arya raises the target price on AMD to $195, citing the possibility of AMD gaining market share from Intel, potentially achieving a 29% annual sales growth.
Analysts Issue Mixed Ratings and Price Target Adjustments
- Raymond James analyst Srini Pajjuri downgraded from Strong Buy to Outperform and raised the price target from $190 to $195.
- Cantor Fitzgerald analyst C J Muse reiterated an Overweight and $190 price target.
- Morgan Stanley analyst Joseph Moore maintained an Overweight and raised the price target from $128 to $193.
- B of A Securities analyst Vivek Arya kept a Buy rating and increased the price target from $165 to $195.
- Stifel analyst Ruben Roy maintained a Buy rating and raised the target price from $170 to $200.
- Susquehanna analyst Christopher Rolland reiterated a Positive rating and increased the price target from $170 to $210.
Which Analyst has the best track record to show on AMD?
Analyst Matthew Bryson (WEDBUSH) currently has the highest performing score on AMD with 10/10 (100%) price target fulfillment ratio. His price targets carry an average of $21.96 (20.33%) potential upside. Advanced Micro Devices stock price reaches these price targets on average within 131 days.
GM Exceeds Q4 2023, Sets 2024 Outlook Amid Industry Challenges
General Motors reported adjusted earnings per share of $1.24 for Q4 2023, exceeding analysts' estimates of $1.16. Furthermore, GM's revenue for the quarter reached $42.98 billion, outpacing the anticipated $38.67 billion. Looking ahead, GM's 2024 guidance projects net income attributable to stockholders in the range of $9.8 billion to $11.2 billion, with corresponding earnings per share expected to be between $8.50 and $9.50. The company also forecasts adjusted earnings before interest and taxes of $12 billion to $14 billion, along with adjusted automotive free cash flow estimated to be between $8 billion and $10 billion.
Despite challenges in key markets such as China, where GM's equity income for the year declined by 34%, the company remains steadfast in its commitment to innovation and growth. GM's proactive measures include plans to reduce spending on its majority-owned autonomous vehicle subsidiary, Cruise, by approximately $1 billion in 2024. Additionally, GM aims to capitalize on the evolving automotive landscape by expanding its electric vehicle lineup, with plans to add 1 million units worth of EV production capacity in North America by 2025. Despite facing headwinds such as slower-than-expected EV adoption in the U.S., GM projected industry sales of approximately 16 million units in 2024.
Analysts Mixed Views as Price Targets Diverge
- CFRA analyst Garrett Nelson maintained a Hold rating and raised the price target from $34 to $38.
- Barclays analyst Dan Levy reiterated an Overweight rating and increased the price target from $37 to $44.
- Redburn Atlantic analyst Adrian Yanoshik initiated a Neutral rating and a Price Target of $40.
Which Analyst has the best track record to show on GM?
Analyst Mark Delaney (GOLDMAN) currently has the highest performing score on GM with 5/9 (55.56%) price target fulfillment ratio. His price targets carry an average of $13.07 (45.18%) potential upside. General Motors stock price reaches these price targets on average within 58 days.
F5 Networks Surpasses Q1 Earnings, Forecasts Growth
F5 Networks reported fiscal first-quarter earnings, with earnings per share at $3.43 better than the analyst estimate of $3.04. Revenue came in at $693 million, outperforming analysts' expectations of $684.77 million. Looking ahead, the company provided revenue guidance for the fiscal second quarter in the range of $675 million to $695 million, exceeding Wall Street estimates. However, the projected earnings per share for the second quarter fell slightly below consensus expectations at $2.79 to $2.91. F5's raised fiscal 2024 earnings guidance, anticipating growth between 6% to 8%, up from the previous range of 5% to 7%, reflects optimism driven by a lower expected tax rate for the year.
While some analysts express concerns about muted growth prospects, Needham analyst Alex Henderson remains bullish, upgrading the stock to a Buy rating and increasing the price target to $220 from $200, citing signs of customer stabilization and demand for F5's networking and security solutions.
Mixed Analyst Ratings as Price Targets Adjust
- Piper Sandler analyst James Fish maintained a Neutral rating and raised the price target from $170 to $187.
- Goldman Sachs analyst Michael Ng reiterated a Neutral rating and increased the price target from $156 to $179.
- Barclays analyst Tim Long kept an Equal-Weight rating and upgraded the price target from $163 to $206.
- Needham analyst Alex Henderson maintained a Buy rating and raised the price target from $200 to $220.
Which Analyst has the best track record to show on FFIV?
Analyst Matthew Hedberg (RBC) currently has the highest performing score on FFIV with 15/16 (93.75%) price target fulfillment ratio. His price targets carry an average of $8.32 (5.49%) potential upside. F5 Networks stock price reaches these price targets on average within 133 days.
Daily stock Analysts Top Price Moves Snapshot

January 31, 2024:
By: Matthew Otto
Microsoft Beats Analyst Expectations, Market Reacts Cautiously
Microsoft's fiscal second-quarter earnings reported $2.93 earnings per share on a revenue of $62 billion for the quarter ending in December. This performance surpassed analysts' expectations, who had forecasted earnings of $2.77 per share on revenue totaling $61.1 billion. Azure and other cloud services witnessed a 30% increase in revenue on an annual basis, propelling the Intelligent Cloud segment's overall sales growth to 20%, reaching $25.9 billion.
Despite the performance, the company's outlook for Intelligence Cloud revenue in the upcoming quarter fell slightly short of $25.9 billion analysts expectations, with guidance ranging between $26 billion and $26.3 billion. This marks a quarter-over-quarter growth rate of just 1.5%, in contrast to the previous quarter's 6.6% growth.
Analysts Raise Price Targets Amid Optimistic Outlook
- Wells Fargo's Michael Turrin maintained an Overweight rating and increased the price target from $435 to $460.
- Raymond James's Andrew Marok reiterated an Outperform rating and raised the price target from $400 to $450.
- Macquarie's Sarah Hindlian also maintained an Outperform rating and raised the price target from $430 to $450.
- Barclays's Raimo Lenschow kept an Overweight rating and lifted the price target from $421 to $475.
- Wedbush's Daniel Ives reiterated an Outperform rating and a $450 price target.
- Wolfe Research's Alex Zukin reiterated an Outperform rating and upgraded the price target from $480 to $510.
- CFRA's Angelo Zino maintained a Strong Sell rating and increased the price target from $420 to $455.
- DA Davidson's Gil Luria kept a Buy rating and raised the price target from $415 to $500.
- UBS's Karl Kierstead kept a Buy rating and lifted the price target from $400 to $480.
- BofA Securities's Brad Sills reiterated a Buy rating and raised the price target from $450 to $480.
Which Analyst has the best track record to show on MSFT?
Analyst Mark Murphy (JPMORGAN) currently has the highest performing score on MSFT with 24/24 (100%) price target fulfillment ratio. His price targets carry an average of $68.63 (21.69%) potential upside. Microsoft stock price reaches these price targets on average within 97 days.
Starbucks Reports Mixed Quarter with Revenue Miss and Growth Challenges
In its recent quarterly report, Starbucks revealed an increase in net income from $855.2 million to $1.02 billion compared to the previous year. Adjusted earnings per share fell slightly short of expectations at 90 cents, while analysts had anticipated 93 cents.
The company's revenue of $9.43 billion also missed estimates of $9.59 billion.Starbucks witnessed a 5% rise in global same-store sales, trailing StreetAccount's forecast of 7.2%. In North America, where same-store sales similarly increased by 5%, Starbucks experienced a decline in foot traffic from mid-November onward, with CEO Laxman Narasimhan attributing this downturn to misperceptions surrounding the company's stance on the Israel-Hamas conflict.
Despite these challenges, Starbucks set a record with $3.6 billion loaded onto gift cards during the quarter. Internationally, while the Middle East market faced headwinds due to the conflict, China saw a 10% growth in same-store sales, although the average ticket size declined by 9%. Looking ahead, Starbucks revised its full-year revenue growth forecast to between 7% and 10%, down from the previously projected 10% to 12%.
Analysts Offer Varied Outlooks Amidst Market Challenges
- Stephens & Co. analyst Joshua Long reiterated an Equal-Weight rating and a $110 price target.
- Wedbush analyst Nick Setyan reiterated a Neutral rating and a $95 price target.
- Citigroup analyst Jon Tower maintained a Neutral rating and raised the price target from $102 to $103.
- Barclays analyst Jeffrey Bernstein maintained an Overweight rating and lowered the price target from $116 to $112.
- JPMorgan analyst John Ivankoe kept an Overweight rating and lowered the price target from $108 to $107.
- Baird analyst David Tarantino kept a Neutral rating and decreased the price target from $110 to $106.
Which Analyst has the best track record to show on SBUX?
Analyst Jon Tower (CITI) currently has the highest performing score on SBUX with 11/17 (64.71%) price target fulfillment ratio. His price targets carry an average of $8.13 (8.85%) potential upside. Starbucks stock price reaches these price targets on average within 79 days.
Alphabet's Earnings: Surpasses Expectations Yet Faces Market Skepticism
Alphabet released its fourth-quarter earnings report. The company surpassed analysts' expectations in key financial metrics, including earnings per share at $1.64 compared to the projected $1.59, and revenue reaching $86.31 billion versus the estimated $85.33 billion. While Google Cloud showcased a revenue hitting $9.19 billion, surpassing the expected $8.94 billion, YouTube ads fell slightly short, generating $9.2 billion compared to the anticipated $9.21 billion. Additionally, Alphabet's traffic acquisition costs came in lower than expected at $13.9 billion, compared to the estimated $14.1 billion, reflecting a mixed performance across its various revenue streams.
Moreover, Alphabet's financial report revealed restructuring costs, with severance and related charges totaling $2.1 billion for 2023, in addition to expenses associated with office closures amounting to $1.2 billion for the quarter and $1.8 billion for the year. Net income surged by 52% to $20.7 billion compared to $13.6 billion a year earlier, and operating margin expanded from 24% to 27%, investors remain wary. CFO Ruth Porat projected further severance-related expenses of approximately $700 million in the upcoming quarter.
Analysts Mixed Outlook with Price Target Adjustments
- Wedbush analyst Scott Devitt reiterated an Outperform rating and a $160 price target.
- Redburn Atlantic analyst James Cordwell maintained a Buy rating and raised the price target from $150 to $165.
- Wolfe Research analyst Deepak Mathivanan maintained an Outperform rating and increased the price target from $170 to $180.
- Needham analyst Laura Martin reiterated a Buy rating and a $160 price target.
- Barclays analyst Ross Sandler kept an Overweight rating and lowered the price target from $180 to $173.
- BofA Securities analyst Justin Post maintained a Buy rating and lowered the price target from $175 to $173.
Which Analyst has the best track record to show on GOOGL?
Analyst Scott Devitt (STIFEL) currently has the highest performing score on GOOGL with 16/19 (84.21%) price target fulfillment ratio. His price targets carry an average of $34.39 (27.38%) potential upside. Alphabet stock price reaches these price targets on average within 253 days.
Daily stock Analysts Top Price Moves Snapshot